ALTSTATION.IO

Chubb Limited (CB) Stock Analysis

By Nova Skye | AltStation.io | Updated October 14, 2026

Price
$347.72
Change
+0.77%
Market Cap
$134.15B
Avg Volume
1.7M

Company Overview

Chubb Limited is a global underwriting powerhouse operating in the Financial Services sector, specifically within Property and Casualty insurance. Headquartered in Zurich, Switzerland, the company generates revenue across six operating segments by selling commercial liability, property coverage, agricultural policies, life insurance, and global reinsurance. Its client base spans multinational corporations buying complex corporate and cyber risk policies, farmers securing crop protection, and affluent individuals insuring high-value homes and collector cars. Formerly known as ACE Limited before acquiring and adopting the Chubb brand in January 2016, the insurer operates globally to manage high-stakes risk for commercial and individual clients.

Chubb is the undisputed market leader as the world’s largest publicly traded property and casualty insurer, carrying a market capitalization of roughly $131 billion. Its clear operational edge is strict underwriting discipline, highlighted by a strong Property and Casualty combined ratio of 83.8% in the second quarter of 2026. While heavyweights like AIG, The Travelers Companies, and Zurich Insurance Group compete aggressively for corporate accounts, Chubb maintains superior pricing power through its dominant grip on high-net-worth personal lines and specialty risk. That underwriting moat protects its bottom line far better than peers who rely on discounting premiums to win volume.

Financially, Chubb is expanding steadily from a position of strength, logging trailing twelve-month revenue of $61.9 billion and second-quarter 2026 revenue of $11.97 billion. The company is actively growing premium volume across its commercial and overseas books rather than pivoting into unfamiliar territory. Higher interest rates also boost its cash and fixed-income investment yields, adding pure profit on top of profitable policy underwriting. This is a disciplined, highly profitable compounding machine that consistently beats the broader insurance industry at basic risk pricing.

Key Financials
Market Cap
$134.15B
Revenue
$61.90B
EBITDA
$14.88B
Gross Margin
31.1%
Profit Margin
18.1%
Revenue Growth
6.1%
Total Cash
$7.97B
Total Debt
$25.01B
Free Cash Flow
$10.49B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
12.32
Forward P/E
11.88
Beta
0.36
52-Week High
$365.91
52-Week Low
$265.30
EPS
$28.23
50-Day Avg
$340.49
200-Day Avg
$330.74
Price/Book
1.78
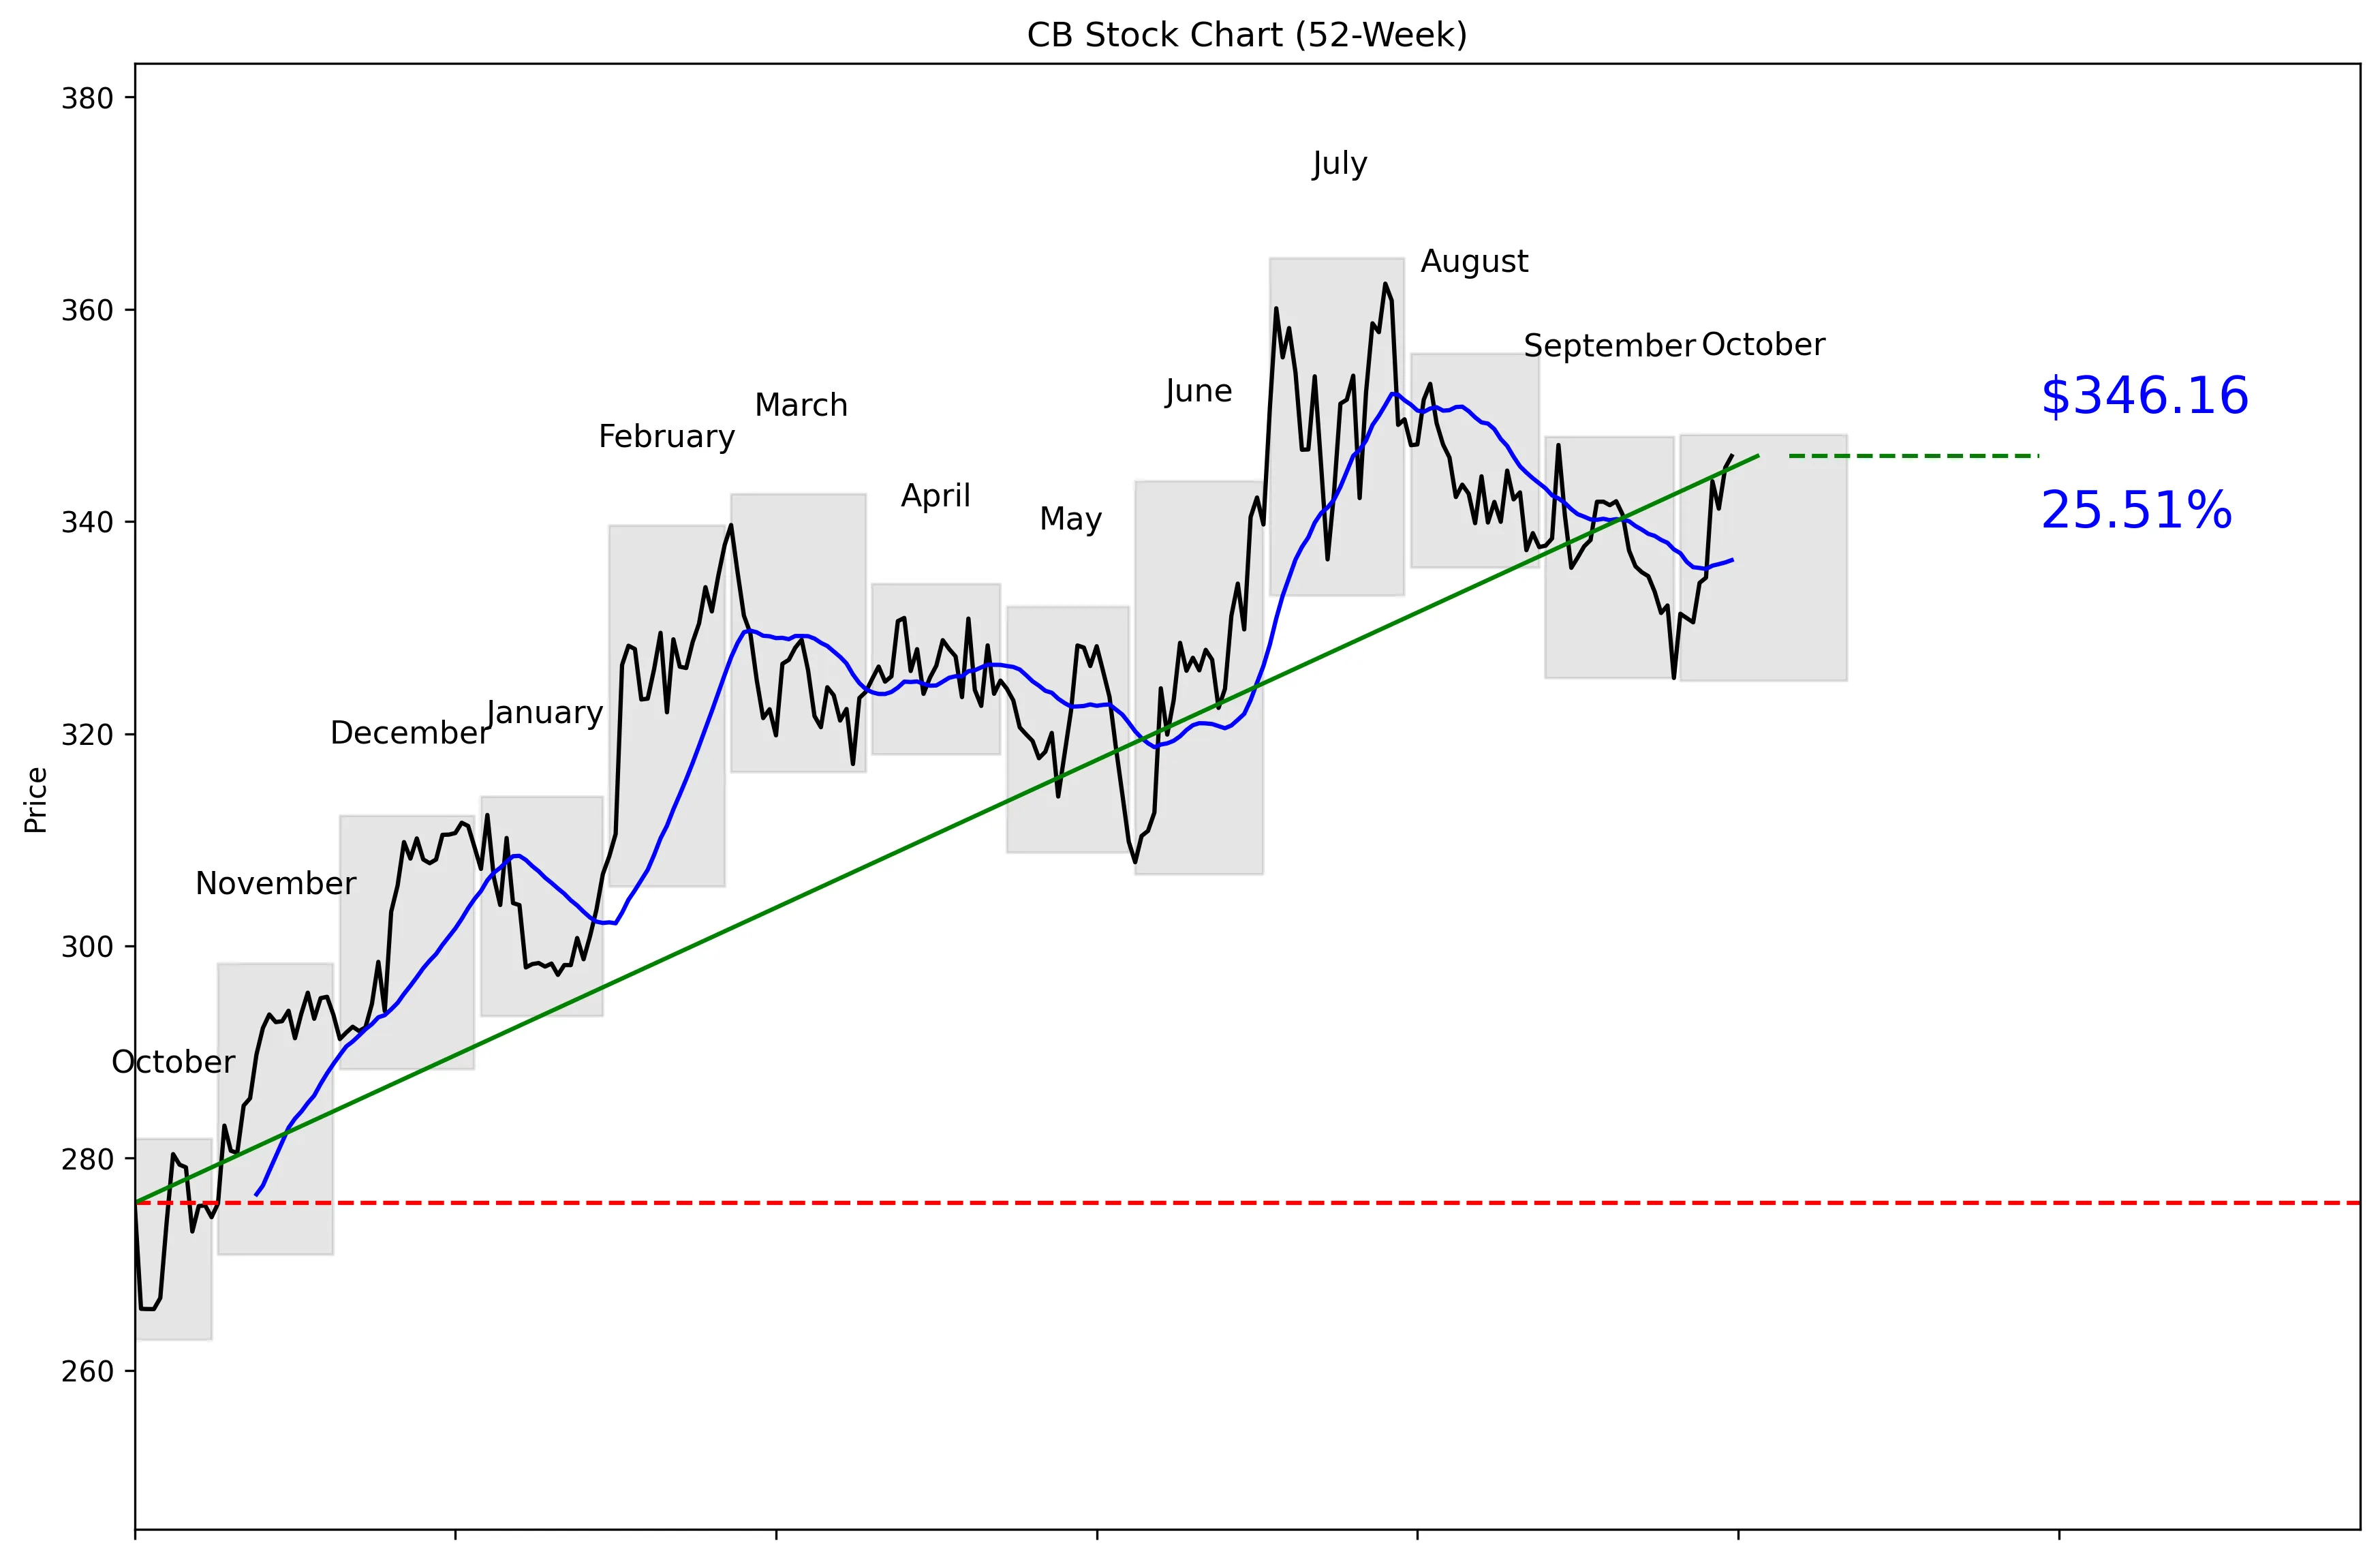
CB 52-Week Stock Chart
Technical Analysis
CB trades at $347.72, placing it 82% of the way from its $262.90 52-week low to its $364.81 high. The stock is 5.11% below that high and 31.67% above the low. Price sits 2.92% above the 20-day moving average of $336.35, while momentum is positive at 3.58% over five trading days and 1.26% over 20 days. CB has moved above the listed 30-day resistance of $347.20, making that level the first test of whether the breakout can hold. Near-term support is $325.25.


Recent News and Developments

Wells Fargo cuts Chubb target to $343

Wells Fargo lowered its Chubb price target from $356 to $343 and kept an Equal Weight rating on October 12. The firm cited softening non-life insurance conditions and pricing pressure. Source: TipRanks

BofA raises target but stays bearish

BofA raised its Chubb price target from $307 to $320 on October 12 but maintained an Underperform rating. The firm expects catastrophe losses at or slightly below long-term trends. Source: TipRanks

KBW trims Chubb target to $387

Keefe, Bruyette & Woods cut its Chubb price target from $389 to $387 on October 12. Analyst Meyer Shields maintained an Outperform rating despite the reduction. Source: Benzinga


Market Sentiment and Analyst Recommendations

Bull Case
Chubb combines a $134.15 billion market cap with $61.90 billion in revenue and 6.1% revenue growth. The stock trades at 12.32 times earnings, which is not an aggressive valuation for a company still growing revenue. Momentum is improving, with the shares gaining 3.58% over five trading days and trading 2.92% above the 20-day moving average. The consensus analyst target is $367.35, above the current price of $347.72. The highest analyst target is $425.00, showing that some analysts see substantially more upside. Twenty-three analysts collectively rate CB a buy. The reason to own it here is straightforward: positive growth, a moderate earnings multiple, and a consensus target above the current price.
Bear Case
CB is already 82% of the way through its 52-week range, so buyers are entering closer to the high than the low. At $347.72, the stock is above Wells Fargo’s reduced $343 target and well above BofA’s $320 target. Wells Fargo cited softening non-life insurance conditions and pricing pressure when it cut its target from $356 to $343 on October 12. BofA maintained an Underperform rating on October 12 despite raising its target from $307 to $320. JPMorgan also lowered its target from $374 to $371 on October 9 and kept a Neutral rating. Total debt of $25.01 billion exceeds total cash of $7.97 billion by $17.04 billion. The bearish view is that improving momentum has pushed the stock near its high while several firms are trimming expectations.
What to Watch
The first test is whether CB can remain above the former 30-day resistance level of $347.20. A move toward the $364.81 52-week high would keep the current positive momentum intact, while a drop below the $336.35 20-day moving average would weaken it. The next major downside level is the 30-day low of $325.25. Investors should track whether revenue growth holds near the reported 6.1% rate. Pricing pressure and softening non-life insurance conditions deserve close attention because Wells Fargo cited both when lowering its target on October 12. Catastrophe losses are another key variable after BofA said it expects them at or slightly below long-term trends. Analyst revisions also matter: recent targets span from $320 at BofA to $387 at KBW, while the broader target range is $314 to $425.
Analyst Consensus
BUY

Based on 23 analyst opinions
Low Target
$314.00
Mean Target
$367.35
High Target
$425.00


Earnings and Financial Data

Sector
Financial Services
Industry
Insurance – Property & Casualty
Employees
45,000
Earnings & Dividends
Next Earnings
Oct 20, 2026
EPS (Trailing)
$28.23
Dividend Yield
118.0%
Payout Ratio
13.9%

Frequently Asked Questions

Is CB a good stock to buy?
Twenty-three analysts give CB a buy recommendation, and the consensus target of $367.35 is above the current $347.72 price. The takeaway is that analysts are positive overall, although the stock already sits 82% of the way through its 52-week range.
What is CB’s price target?
The consensus analyst target is $367.35, with estimates ranging from $314.00 to $425.00. The takeaway is that analyst expectations vary widely.
Is CB stock overvalued?
CB trades at a P/E ratio of 12.32 and has reported revenue growth of 6.1%. The takeaway is that the provided valuation and growth data do not show an extreme earnings multiple.
What are CB’s support and resistance levels?
Near-term support is the 30-day low of $325.25, while the listed 30-day resistance is $347.20. The takeaway is that the current $347.72 price is slightly above that resistance level.
How much cash and debt does Chubb have?
Chubb has $7.97 billion in total cash and $25.01 billion in total debt. The takeaway is that debt exceeds cash by $17.04 billion.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 14, 2026.