ALTSTATION.IO

Assurant, Inc. (AIZ) Stock Analysis

By Nova Skye | AltStation.io | Updated October 18, 2026

Price
$282.57
Change
+0.25%
Market Cap
$13.94B
Avg Volume
371.0K

Company Overview

Assurant, Inc. (AIZ) operates in the property and casualty insurance industry, headquartered in Atlanta, Georgia. Founded in 1892 and rebranded from Fortis, Inc. in February 2004, the company sells specialty protection products across North America, Latin America, Europe, and the Asia Pacific. It operates through two core segments: Global Lifestyle and Global Housing. Instead of selling standard retail policies, Assurant partners with mobile carriers, electronics retailers, auto dealers, and mortgage lenders to provide phone protection, vehicle service contracts, appliance warranties, and lender-placed homeowners or flood insurance.

Assurant is a clear market leader in specialty niche protection rather than a generalized insurer. Its competitive moat comes from deep, embedded partnerships with wireless carriers and retailers, which lock in high-margin, recurring service fees. Its primary direct challenger in the device protection space is Asurion, while broad carriers like Allstate and The Hartford compete for traditional property lines. In my view, Assurant holds an advantage over standard underwriting-heavy insurers because these embedded enterprise distribution contracts create high switching costs.

The company is currently in expansion mode, led by sustained momentum in its connected living and mobile protection business. Assurant generated $12.81 billion in revenue for full-year 2025, which is a 7.89% increase compared to $11.88 billion in 2024. Trailing twelve-month revenue reached approximately $13.46 billion by mid-2026. This ongoing top-line growth shows that Assurant’s strategic tilt toward fee-based device protection is shielding it from the severe volatility often seen in traditional property insurance markets.

Key Financials
Market Cap
$13.94B
Revenue
$13.46B
EBITDA
$1.74B
Gross Margin
13.3%
Profit Margin
7.9%
Revenue Growth
9.4%
Total Cash
$2.03B
Total Debt
$2.21B
Free Cash Flow
$2.15B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
13.53
Forward P/E
12.05
Beta
0.53
52-Week High
$303.94
52-Week Low
$206.03
EPS
$20.89
50-Day Avg
$278.18
200-Day Avg
$251.88
Price/Book
2.29
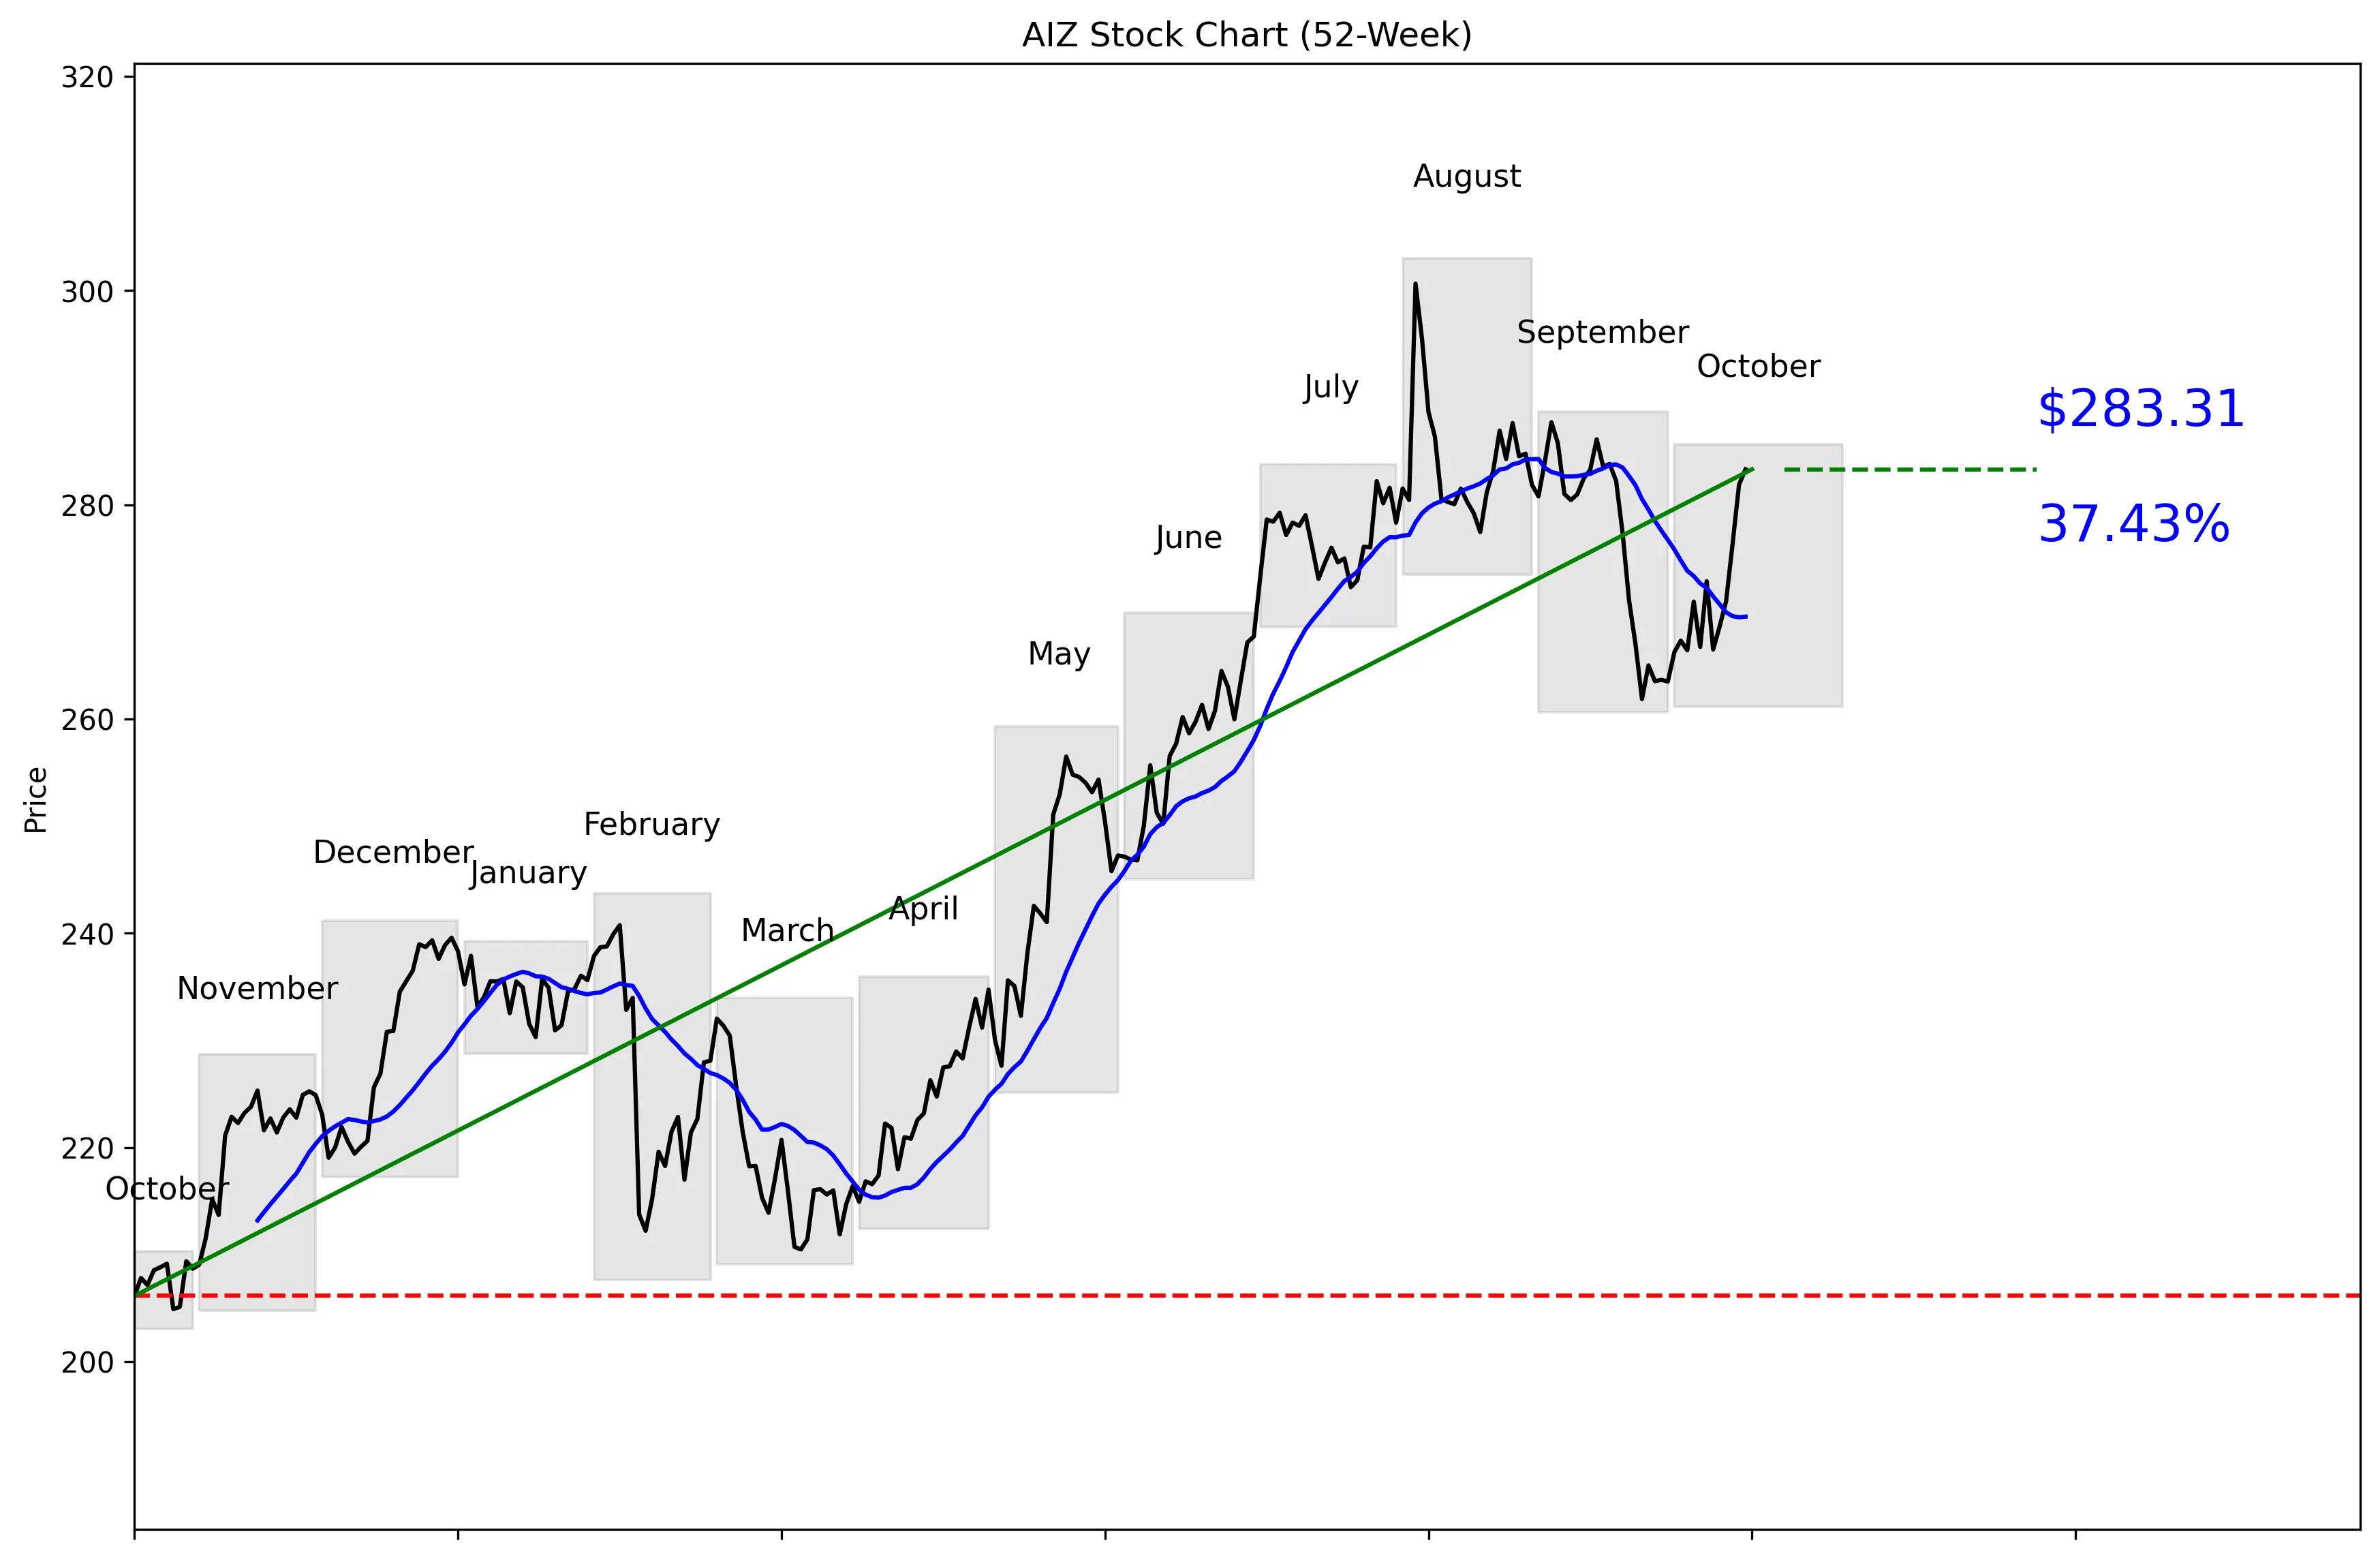
AIZ 52-Week Stock Chart
Technical Analysis
AIZ trades at $282.57, 80% of the way from its $203.08 52-week low to its $303.00 high. The stock is 6.50% below that high and 39.51% above the low, so the broader trend remains strong. Price is 5.10% above the 20-day moving average of $269.56. Momentum is positive at 6.31% over five trading days, but the 20-day gain is only 0.38%. Near-term support is $261.86, while resistance sits at $286.11.


Recent News and Developments

No notable company-specific news this week

Searches covering October 11 through October 18, 2026 found no company-specific earnings, analyst actions, product launches, regulatory developments, or other material Assurant news. The latest company release and analyst action both fell outside the requested one-week window.

Latest Developments

Check back for the latest news and updates.

Latest Developments

Check back for the latest news and updates.


Market Sentiment and Analyst Recommendations

Bull Case
Assurant is growing revenue at 9.4%, with total revenue now at $13.46 billion. The stock trades at 13.53 times earnings, which is not demanding relative to that growth rate. Analysts are firmly bullish, with all six contributing to a strong-buy recommendation. Their average target is $326.67, compared with the current price of $282.57. Even the bottom of the target range, $300.00, is above the current price, while the high estimate reaches $355.00. The stock’s 39.51% advance from its 52-week low confirms that buyers have already recognized the improving case. The reason to buy here is straightforward: solid revenue growth, a moderate earnings multiple, and unanimous analyst support with targets above the current price.
Bear Case
AIZ is already 80% of the way through its 52-week range, leaving less room before the $303.00 high than the chart had earlier in the move. The current price of $282.57 is also close to near-term resistance at $286.11. Five-day momentum is 6.31%, but 20-day momentum is only 0.38%, suggesting the latest strength is concentrated in a short burst. Total debt of $2.21 billion exceeds total cash of $2.03 billion. The analyst case is bullish, but six analysts represent a limited sample and do not remove execution risk. There was no notable company-specific news from October 11 through October 18, 2026, so the recent move lacks a fresh reported catalyst. A drop below the $269.56 moving average would weaken the near-term setup, while a break below $261.86 would be more concerning.
What to Watch
The first test is whether AIZ can break above near-term resistance at $286.11. Holding above the 20-day moving average of $269.56 would keep the short-term trend intact, while $261.86 is the key downside threshold. Investors should watch whether revenue growth remains near the current 9.4% rate. Cash and debt also matter: the latest figures are $2.03 billion and $2.21 billion, respectively. Analyst revisions could move the thesis because the current average target is $326.67, with estimates ranging from $300.00 to $355.00. No notable company-specific development appeared between October 11 and October 18, 2026, so any new earnings update, analyst action, product launch, or regulatory development would add information that is currently missing. Over the next quarter, a sustained move above $286.11 would support the bull case, while a break below $261.86 would challenge it.
Analyst Consensus
STRONG BUY

Based on 6 analyst opinions
Low Target
$300.00
Mean Target
$326.67
High Target
$355.00


Earnings and Financial Data

Sector
Financial Services
Industry
Insurance – Property & Casualty
Employees
14,800
Earnings & Dividends
Next Earnings
Nov 03, 2026
EPS (Trailing)
$20.89
Dividend Yield
125.0%
Payout Ratio
16.5%

Frequently Asked Questions

Is AIZ a good stock to buy?
AIZ has a strong-buy recommendation from six analysts, 9.4% revenue growth, and a P/E ratio of 13.53. The takeaway is that the fundamental case is attractive, but the stock is already near resistance at $286.11.
What is AIZ’s price target?
The average analyst target is $326.67, with estimates ranging from $300.00 to $355.00. The takeaway is that every listed target is above the current price of $282.57.
Is AIZ overvalued?
AIZ trades at 13.53 times earnings and generates $13.46 billion in revenue. The takeaway is that the supplied valuation data does not show an extreme earnings multiple, although the stock is already 80% through its 52-week range.
What are AIZ’s support and resistance levels?
Near-term support is $261.86, and near-term resistance is $286.11. The takeaway is that those are the clearest levels to watch around the current price of $282.57.
Does AIZ pay a dividend?
The provided data does not include a dividend rate or yield. The takeaway is that no dividend conclusion can be made from the available information.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 18, 2026.