ALTSTATION.IO

W. R. Berkley Corporation (WRB) Stock Analysis

By Nova Skye | AltStation.io | Updated October 12, 2026

Price
$73.19
Change
+1.77%
Market Cap
$27.17B
Avg Volume
2.5M

Company Overview

W. R. Berkley Corporation is a commercial property and casualty insurer headquartered in Greenwich, Connecticut, operating in the financial services sector since 1967. The company makes its money through two distinct units: standard and specialty commercial Insurance, and Reinsurance & Monoline Excess. They underwrite hard-to-place policies that mass-market carriers avoid, covering risks like cyber liability, directors and officers exposure, workers’ compensation, medical malpractice, and high-value collectibles. Their customers range from small and mid-sized enterprises to public institutions and other insurers seeking risk transfer.

Berkley operates as an elite niche player focused on specialty lines and excess and surplus coverage rather than commoditized insurance. Its main edge is a decentralized network of autonomous operating units, which lets specialized underwriters price messy risks accurately while corporate giants stall. The company goes toe-to-toe with specialty peers like Markel Group and Arch Capital, along with diversified heavyweight Chubb. Rising catastrophe losses and litigation inflation remain constant industry headwinds, but Berkley manages risk effectively by pulling back capital whenever market pricing turns soft.

The company is in an aggressive growth phase, increasing annual revenue by 6.9% to $14.63 billion in 2025 from $13.69 billion in 2024. Profitability is outstanding, generating $1.78 billion in 2025 net income alongside a disciplined 90.7% consolidated GAAP combined ratio. Because any combined ratio under 100% represents pure underwriting profit, maintaining an underwriting margin above 9% proves strong pricing power across its book. Berkley is not pivoting or wasting capital on flashy acquisitions, opting instead to compound returns by staying loyal to core risk discipline.

Key Financials
Market Cap
$27.17B
Revenue
$14.90B
EBITDA
$2.58B
Gross Margin
43.8%
Profit Margin
12.9%
Revenue Growth
1.2%
Total Cash
$3.90B
Total Debt
$3.10B
Free Cash Flow
$3.05B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
15.03
Forward P/E
14.98
Beta
0.27
52-Week High
$78.96
52-Week Low
$62.87
EPS
$4.87
50-Day Avg
$69.63
200-Day Avg
$68.93
Price/Book
2.89
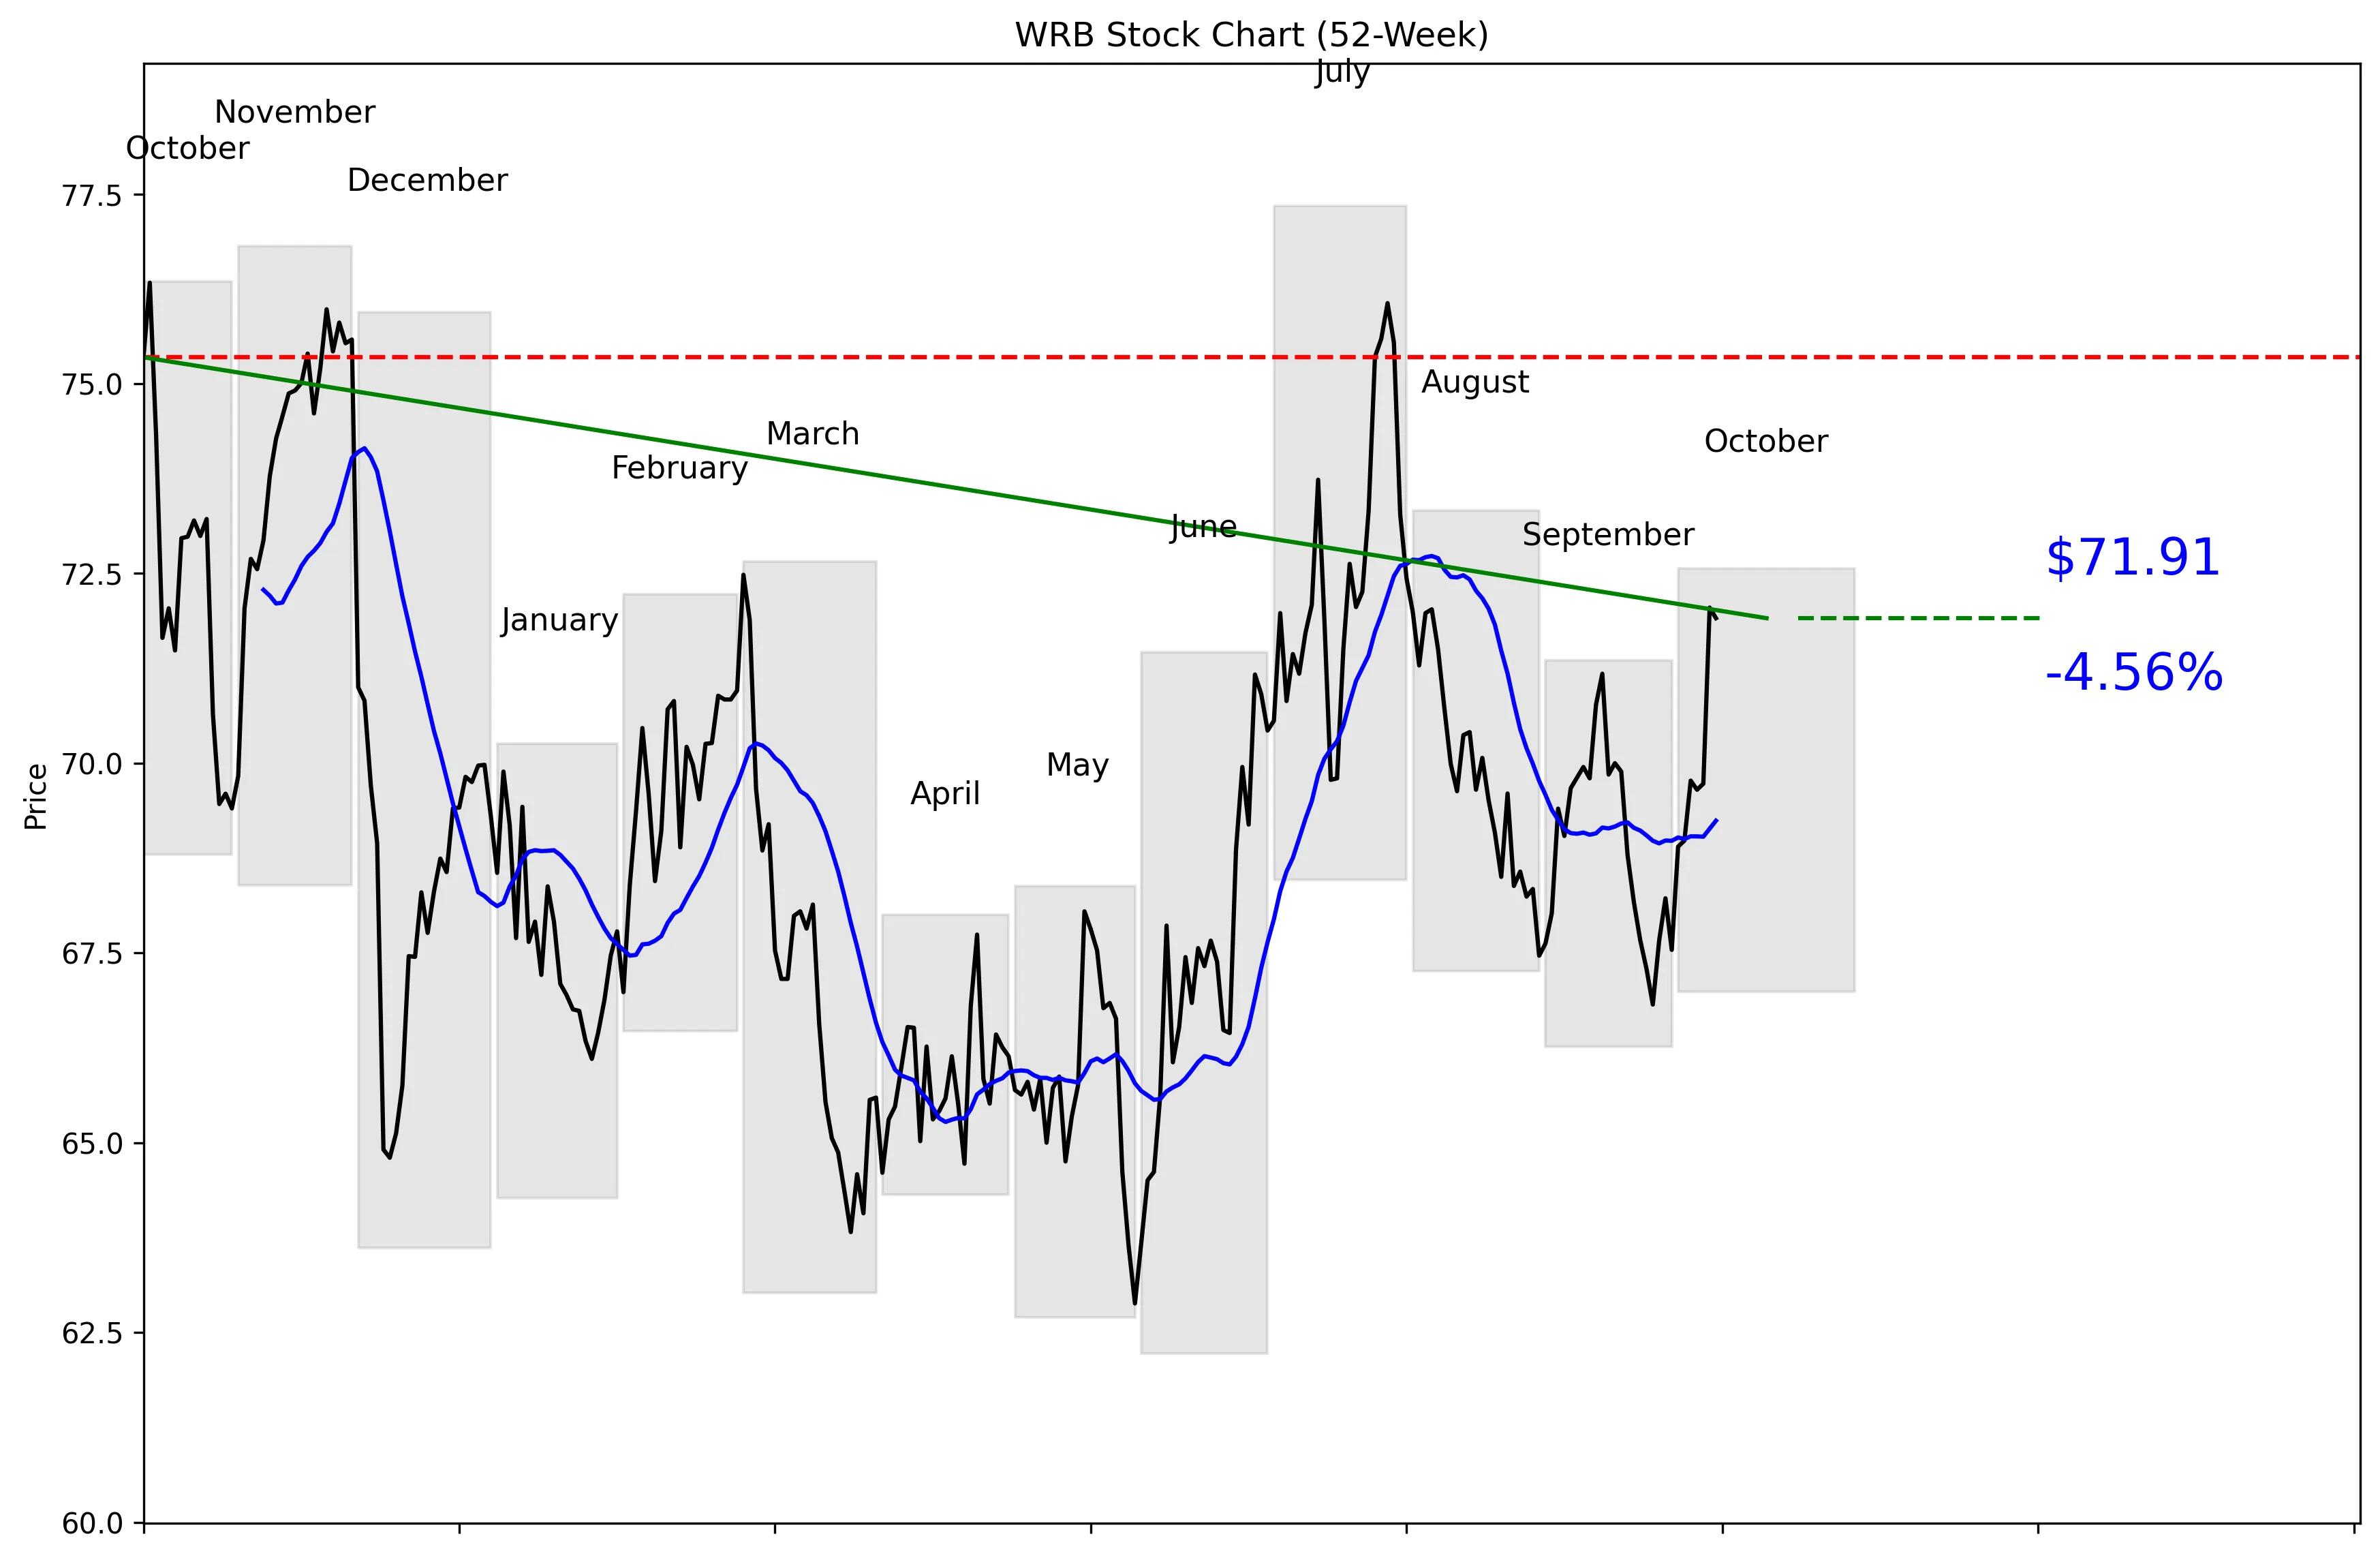
WRB 52-Week Stock Chart
Technical Analysis
WRB trades at $73.19, 64% of the way from its technical 52-week low of $62.22 to its $77.34 high. The stock is 7.02% below that high and 15.58% above the low. Price is 3.85% above the 20-day moving average of $69.24, backed by gains of 4.25% over five trading days and 3.02% over 20 days. WRB has moved above the listed near-term resistance of $72.05, while the 30-day low of $66.82 is the key support level.


Recent News and Developments

Wells Fargo cuts WRB target while BofA raises its target

Wells Fargo maintained its Sell rating on October 12 and cut its price target from $68 to $65. Bank of America Securities also maintained Sell but raised its target from $66 to $69. Source: Stock Analysis

Analysts split on WRB valuation

On October 7, Cantor Fitzgerald raised its WRB target from $73 to $74 while maintaining Hold. Mizuho cut its target from $72 to $70 with a Hold rating, while Barclays maintained Sell with a $62 target. Source: Stock Analysis

TD Cowen assigns WRB a $51 target

TD Cowen assigned WRB a Sell rating and $51 price target on October 6. Morgan Stanley maintained Hold the same day but reduced its target from $75 to $70. Source: TipRanks


Market Sentiment and Analyst Recommendations

Bull Case
WRB has positive momentum, with the stock up 4.25% over five trading days and 3.02% over 20 days. Trading 3.85% above the $69.24 moving average strengthens the near-term setup. The company has $3.90 billion in cash against $3.10 billion in debt, giving it more cash than debt. Its P/E of 15.03 is not demanding if earnings continue growing. Zacks expects third-quarter earnings of $1.14 per share, up 3.6% year over year, with revenue of $3.8 billion, up 3.1%. Cantor Fitzgerald’s $74 target is close to the current price, while the broader analyst range reaches $83. The reason to buy here is straightforward: a solid balance sheet, positive momentum, and a near-term earnings catalyst.
Bear Case
The clearest problem is valuation upside: the average analyst target of $69.12 is below the current $73.19 price. The consensus recommendation is hold across 17 analysts, not buy. Revenue growth is only 1.2%, which gives investors little room to tolerate disappointing results. Several analysts are openly bearish: Wells Fargo has a $65 target, Bank of America Securities has a $69 target, Barclays has a $62 target, and TD Cowen has a $51 target. Morgan Stanley reduced its target from $75 to $70, while Mizuho cut its target from $72 to $70. The stock has also moved above the listed $72.05 near-term resistance, so recent momentum may already reflect optimism ahead of earnings. If price loses the $69.24 moving average, the next listed support is materially lower at $66.82.
What to Watch
The immediate catalyst is the October 19 third-quarter earnings report. Zacks expects earnings of $1.14 per share, up 3.6%, and revenue of $3.8 billion, up 3.1%. Investors should compare those figures with the company’s broader revenue growth rate of 1.2%. The $69.24 moving average is the first technical level to monitor after earnings, followed by support at $66.82. On the upside, holding above the former $72.05 resistance would keep the recent breakout intact, while $77.34 is the technical 52-week high. Analyst revisions also matter because current targets range from $51 to $83, showing a sharp disagreement over valuation. Results strong enough to push estimates and targets above the current $73.19 price would improve the thesis; a miss combined with a break below $69.24 would weaken it.
Analyst Consensus
HOLD

Based on 17 analyst opinions
Low Target
$51.00
Mean Target
$69.12
High Target
$83.00


Earnings and Financial Data

Sector
Financial Services
Industry
Insurance – Property & Casualty
Employees
8,804
Earnings & Dividends
Next Earnings
Oct 19, 2026
EPS (Trailing)
$4.87
Dividend Yield
56.0%
Payout Ratio
7.6%

Frequently Asked Questions

Is WRB a good stock to buy?
WRB has positive momentum and trades 3.85% above its 20-day moving average, but the consensus recommendation from 17 analysts is hold. The takeaway is that the current data supports patience more than an aggressive purchase.
What is WRB’s price target?
The average analyst target is $69.12, with estimates ranging from $51.00 to $83.00. The takeaway is that the average target sits below the current $73.19 price.
What is WRB’s 52-week range?
The reported 52-week range is $62.87 to $78.96, while the technical price series produced a low of $62.22 and a high of $77.34. The takeaway is that WRB currently sits toward the upper portion of its yearly range.
What are WRB’s support and resistance levels?
The provided near-term support is the 30-day low of $66.82, and the listed resistance is the 30-day high of $72.05. With WRB at $73.19, the takeaway is that price has moved above the listed resistance.
Does WRB pay a dividend?
The provided data does not include dividend information, so no dividend amount or yield can be confirmed. The takeaway is to verify WRB’s current dividend separately before making an income-focused decision.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 12, 2026.