ALTSTATION.IO

Salesforce, Inc. (CRM) Stock Analysis

By Nova Skye | AltStation.io | Updated October 19, 2026

Price
$239.19
Change
-3.06%
Market Cap
$196.85B
Avg Volume
12.9M

Company Overview

Salesforce builds cloud software that helps businesses find, sell to, and support customers across the United States, Europe, and the Asia Pacific. Operating in the application software sector and headquartered in San Francisco since its 1999 incorporation, the company sells core platforms like Agentforce for sales and service automation, Slack for workplace collaboration, and Data 360 for unifying customer records. Its broader lineup covers marketing platforms, commerce services, field service dispatching tools, and Salesforce Starter for small businesses. Target customers span small firms to major institutions across financial services, healthcare, manufacturing, automotive, and government sectors.

Salesforce is the established market leader in customer relationship management software, but defending that position requires constant execution. The company’s primary competitive edge is its massive enterprise footprint, connecting front-office operations directly into centralized data systems across hybrid and multi-cloud setups. The ongoing threat comes from competing application software providers pushing lower-cost alternatives or rival enterprise suites. Salesforce’s moat depends on keeping clients locked into its broader platform rather than letting them migrate to standalone specialized tools.

Salesforce is currently executing a strategic pivot toward autonomous AI, positioning software agents as its primary growth driver. The centerpiece of this push is Agentforce, which lets organizations deploy autonomous agents to handle sales pipelines, customer inquiries, and employee service alongside human staff. By integrating Slack as the communication layer and Data 360 as the context engine, the company is attempting to automate routine workflows across entire enterprises. This shift represents an aggressive push to monetize autonomous agents and protect its core enterprise software franchise.

Key Financials
Market Cap
$196.85B
Revenue
$43.94B
EBITDA
$12.90B
Gross Margin
77.3%
Profit Margin
22.0%
Revenue Growth
10.8%
Total Cash
$11.40B
Total Debt
$42.38B
Free Cash Flow
$17.73B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
21.88
Forward P/E
14.93
Beta
1.26
52-Week High
$269.11
52-Week Low
$146.32
EPS
$10.93
50-Day Avg
$229.04
200-Day Avg
$199.18
Price/Book
5.13
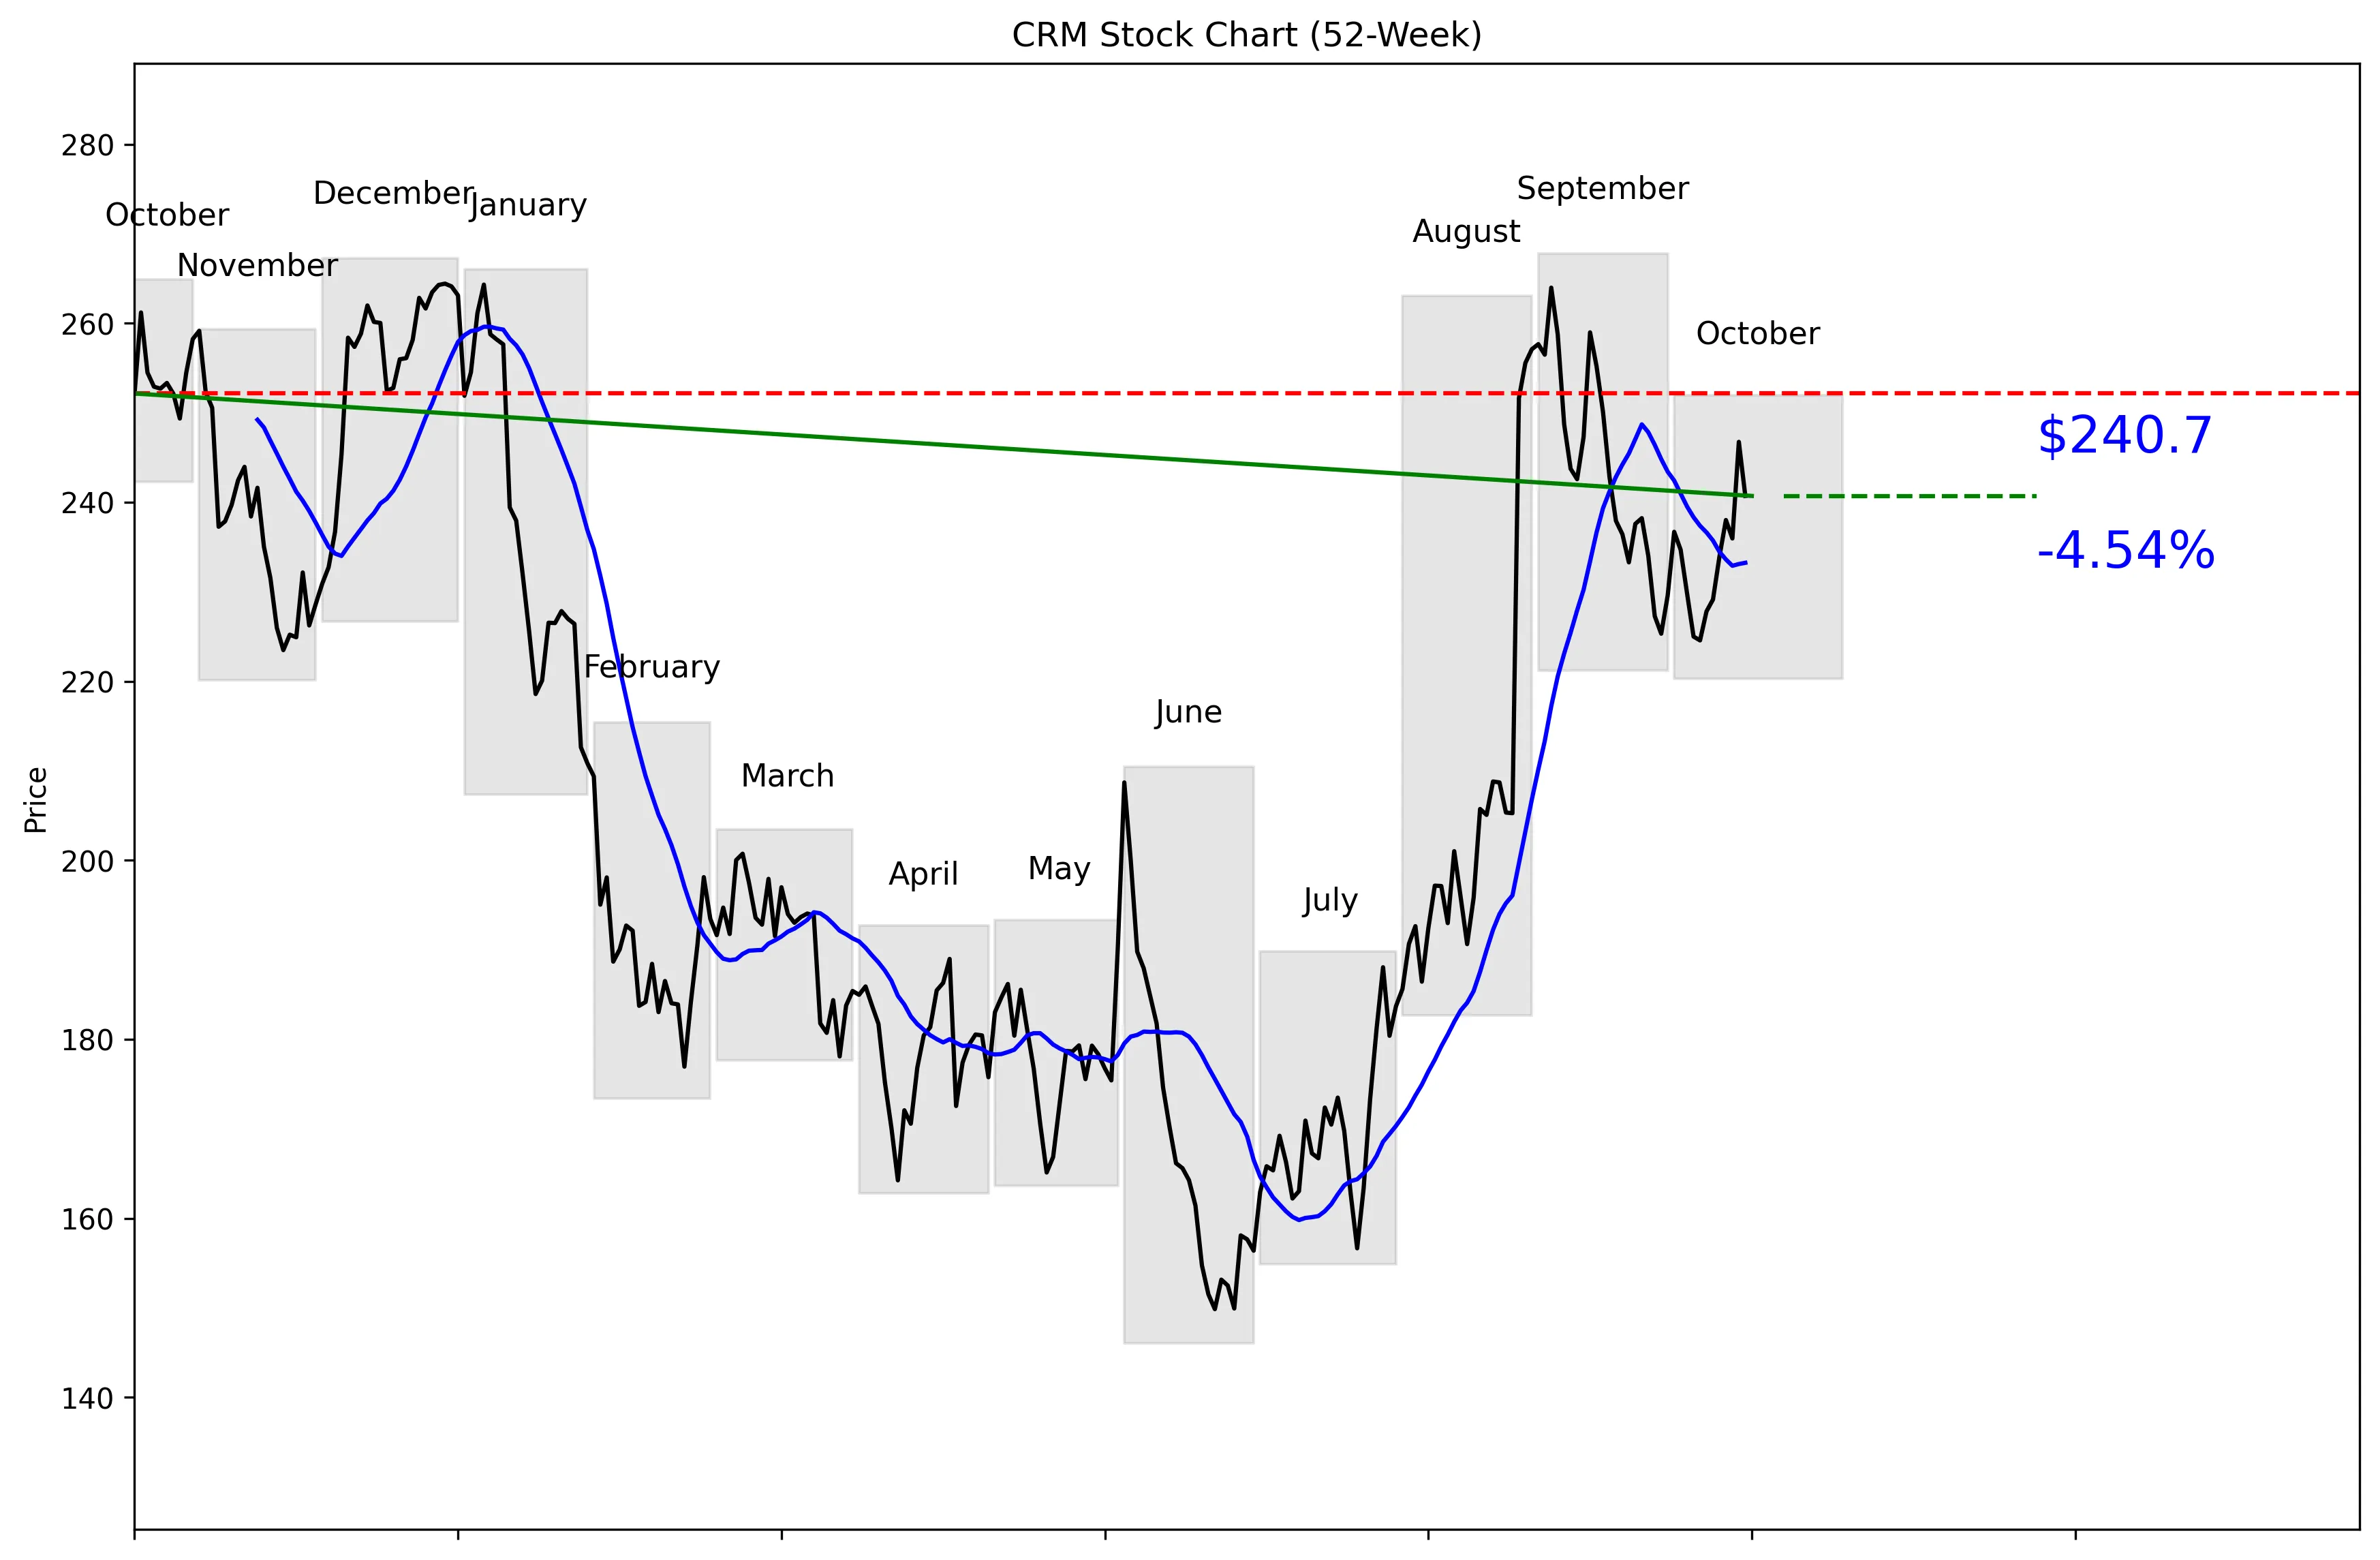
CRM 52-Week Stock Chart
Technical Analysis
CRM trades at $239.19, 78% of the way from its 52-week low of $146.06 to its high of $267.80. The stock is 10.12% below that high and 64.79% above the low, so the broader trend remains strong despite the pullback. Price is 3.20% above the 20-day moving average of $233.23. Momentum is positive at 5.05% over five trading days and 1.17% over 20 trading days. Near-term support is $224.56, while resistance sits at $258.97.


Recent News and Developments

BofA flips Salesforce from Sell to Buy

Bank of America analyst Tal Liani double-upgraded Salesforce from Underperform to Buy and raised the price target from $160 to $285. CRM gained 2.1% after the call, which argued that AI should deepen enterprise dependence on Salesforce rather than displace it. Source: Kiplinger

Salesforce agrees to acquire Loops

Salesforce signed a definitive agreement to acquire Loops, an AI analytics platform that monitors business performance and explains changes in key metrics. Salesforce plans to integrate the technology and specialized talent into Tableau, with closing expected in early November of fiscal 2027. Source: Salesforce

Docusign expands its Salesforce integration

Docusign is bringing its Intelligent Agreement Management platform natively into Salesforce, Agentforce and Slack. The expanded integration lets users generate agreements, review contracts, track renewals and manage approvals without leaving Salesforce workflows. Source: PR Newswire


Market Sentiment and Analyst Recommendations

Bull Case
Salesforce has $43.94 billion in revenue and is still growing that figure by 10.8%. The stock trades at 21.88 times earnings, a defensible valuation if double-digit revenue growth holds. Analysts rate CRM a buy, with 54 analysts setting an average target of $285.68 versus the current $239.19 price. Bank of America strengthened that case by double-upgrading the stock from Underperform to Buy and lifting its target from $160 to $285. The 15-year HMRC agreement is worth up to £2 billion, or about $2.65 billion, and will support services for more than 39 million individuals and businesses. Salesforce is also expanding its AI position through Loops, Agentforce and deeper workflow integration with Docusign, giving customers more reasons to stay inside its platform.
Bear Case
Salesforce carries $42.38 billion in total debt against $11.40 billion in cash, which limits the strength of the balance-sheet argument. The 21.88 P/E is not cheap enough to protect investors if the 10.8% revenue growth rate weakens. CRM is already 64.79% above its 52-week low and sits 78% of the way through its annual range, so buyers are not entering near a depressed price. Analyst targets range from $165 to $475, an unusually wide spread that signals major disagreement about the company’s outlook. The stock’s reversal from a 4.57% gain on October 15 to a 2.45% decline on October 16 shows how quickly enthusiasm can fade. The Loops acquisition and Agentforce push add execution risk because Salesforce must turn new technology into durable revenue rather than another layer of products and costs.
What to Watch
The first technical test is whether CRM can remain above its 20-day moving average of $233.23. A break below $224.56 would weaken the near-term setup, while a move above $258.97 would clear the current 30-day resistance level. Investors should watch whether revenue growth holds at 10.8%, because the 21.88 P/E becomes harder to defend if growth slows. The Loops transaction is expected to close in early November of fiscal 2027, making its integration into Tableau a specific execution checkpoint. Watch for evidence that the HMRC project is progressing toward its goal of supporting more than 39 million users and helping deliver 90% digital service by 2030. The bull case strengthens if CRM advances toward the $285.68 average analyst target; it weakens if the stock loses $224.56 and growth falls below the reported 10.8%.
Analyst Consensus
BUY

Based on 54 analyst opinions
Low Target
$165.00
Mean Target
$285.68
High Target
$475.00


Earnings and Financial Data

Sector
Technology
Industry
Software – Application
Employees
83,334
Earnings & Dividends
Next Earnings
Dec 02, 2026
EPS (Trailing)
$10.93
Dividend Yield
71.0%
Payout Ratio
15.7%

Frequently Asked Questions

Is CRM a good stock to buy?
CRM has a buy recommendation from 54 analysts and an average analyst target of $285.68 compared with its $239.19 price. The takeaway: analyst sentiment is bullish, but investors still need to weigh the valuation and balance sheet.
What is CRM’s price target?
The average analyst target is $285.68, with estimates ranging from $165 to $475. The takeaway: analysts see upside on average, but the wide range shows substantial disagreement.
Is CRM stock overvalued?
CRM trades at a P/E of 21.88 while revenue is growing 10.8%. The takeaway: the valuation requires continued growth and does not offer much protection if that growth slows.
What are CRM’s support and resistance levels?
Near-term support is the 30-day low of $224.56, and near-term resistance is the 30-day high of $258.97. The takeaway: those are the key levels defining the current trading range.
Does CRM pay a dividend?
The provided key and technical data do not include dividend information. The takeaway: no dividend conclusion can be made from the available data.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 19, 2026.