ALTSTATION.IO

Cadence Design Systems, Inc. (CDNS) Stock Analysis

By Nova Skye | AltStation.io | Updated October 20, 2026

Price
$327.20
Change
+2.41%
Market Cap
$90.11B
Avg Volume
2.4M

Company Overview

Cadence Design Systems, incorporated in 1987 and headquartered in San Jose, California, operates within the application software sector. The company builds computational, AI-driven software, hardware, and silicon IP that semiconductor and electronic systems manufacturers buy to design, simulate, and verify microchips. Its core software lineup includes the Innovus platform for digital chip signoff and Virtuoso for custom analog IC design. For testing and verification, customers rely on Xcelium logic simulation and Jasper formal verification, coupled with dedicated Palladium emulation and Protium prototyping hardware.

Cadence holds a commanding position as a core electronic design automation provider, functioning as an indispensable utility for the semiconductor industry. Its primary competitive advantage comes from a deep silicon IP portfolio spanning Tensilica digital signal processors, standard interface protocols like PCIe and USB, and Secure-IC embedded security. The business faces constant demands from soaring chip complexity, forcing continuous upgrades in computational speed and scale. Cadence defends its territory by embedding generative AI through tools like Verisium to automate verification and cut client design cycles.

Cadence is actively pivoting beyond traditional chip design toward comprehensive System Design and Analysis across packaging, boards, and full electronic systems. The company is aggressively targeting multi-chiplet and advanced packaging demands with tools like Integrity 3D-IC, Celsius thermal analysis, and the Millennium multiphasic platform. Its strategic collaboration with NVIDIA anchors a broader push into accelerated computing, digital twins with Reality, and intelligent system exploration with Optimality. This transition into multidisciplinary physics and molecular modeling broadens Cadence from a legacy chip design toolmaker into an end-to-end computational software powerhouse.

Key Financials
Market Cap
$90.11B
Revenue
$5.84B
EBITDA
$2.16B
Gross Margin
85.9%
Profit Margin
23.6%
Revenue Growth
24.2%
Total Cash
$1.53B
Total Debt
$2.65B
Free Cash Flow
$1.61B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
65.05
Forward P/E
34.20
Beta
1.13
52-Week High
$416.69
52-Week Low
$262.75
EPS
$5.03
50-Day Avg
$319.78
200-Day Avg
$326.99
Price/Book
13.14
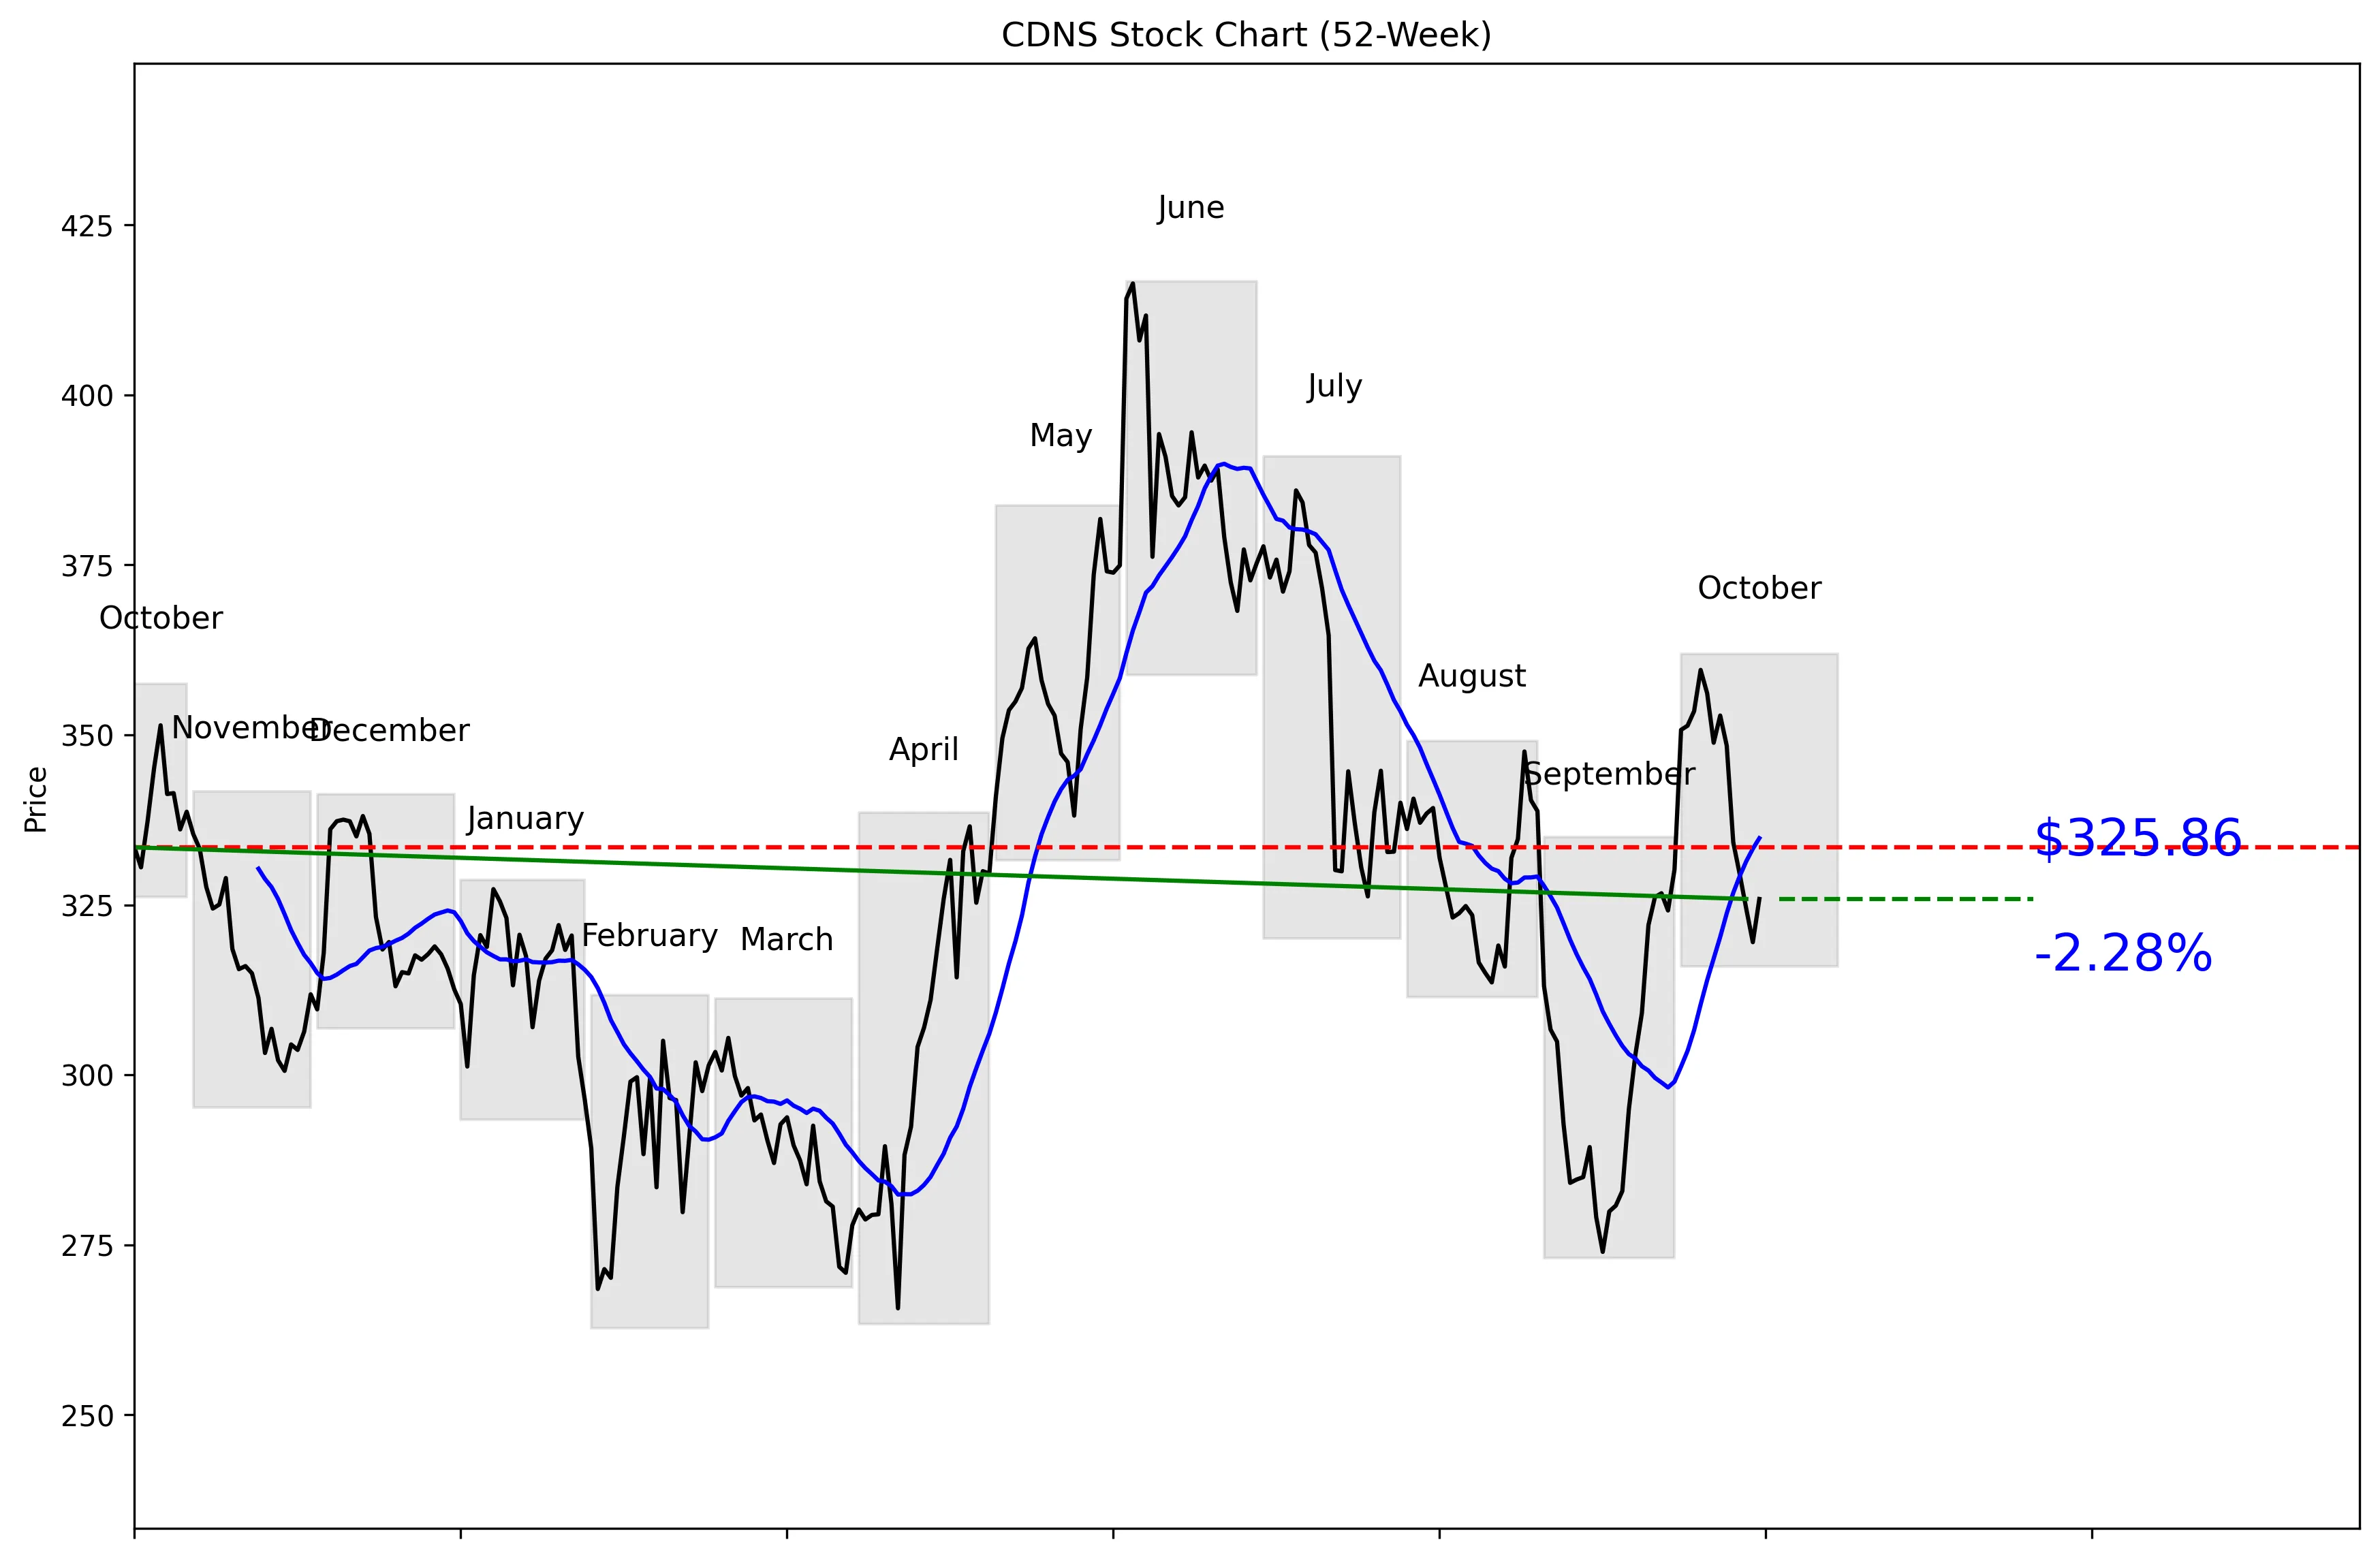
CDNS 52-Week Stock Chart
Technical Analysis
CDNS trades at $327.20, 41% of the way from its 52-week low of $262.75 to its 52-week high of $416.69. The stock is 21.80% below that high but remains 24.02% above the low. Price is 2.67% below the 20-day moving average of $334.80, while five-day momentum is negative 6.47%. The 20-day return is still positive at 10.50%, showing that the broader rebound has not fully broken. Near-term support is $273.96, and resistance is $359.55.


Recent News and Developments

Wall Street Zen cuts Cadence to Hold

Wall Street Zen downgraded Cadence Design Systems from Buy to Hold on October 20. The broader consensus remained Moderate Buy, with 18 Buy ratings, one Strong Buy, three Holds and a $404.14 average price target. Source: MarketBeat

CDNS rebounds 1.99% ahead of earnings

Cadence shares closed at $325.86 on October 19, up $6.35 or 1.99%. The stock traded between $321.58 and $329.84 on volume of 1,854,742 shares. Source: Stock Analysis

Wall Street expects 20.27% revenue growth

Cadence is scheduled to report earnings on October 26. The Zacks consensus estimate calls for $1.61 billion in revenue, up 20.27% from the year-ago quarter. Source: Zacks


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is growing 24.2%, which supports the case that Cadence is still expanding at a strong rate. The next test comes on October 26, when the company is scheduled to report earnings. Wall Street expects quarterly revenue of $1.61 billion, representing 20.27% year-over-year growth. The analyst target is $406.24, well above the current $327.20 price, with the highest target at $470.00. The overall recommendation is strong buy across 26 analysts, while the separate consensus cited in recent news includes 18 Buy ratings, one Strong Buy and three Holds. CDNS also remains 21.80% below its 52-week high, giving buyers room for upside if growth and earnings expectations hold.
Bear Case
The P/E ratio of 65.05 leaves little room for weak growth or disappointing guidance. CDNS has $1.53 billion in cash against $2.65 billion in debt, so the balance sheet does not provide a net-cash cushion. Short-term price action is unstable: the stock lost 9.5% across five sessions before closing at $319.51 on October 16. Five-day momentum remains negative 6.47%, and the current price is 2.67% below the 20-day moving average. Wall Street Zen downgraded the stock from Buy to Hold on October 20, showing that not every analyst views the valuation as attractive. The lowest analyst target is $300.00, below the current price of $327.20, and a break toward the $273.96 support level would materially weaken the chart.
What to Watch
The October 26 earnings report is the immediate catalyst. Revenue needs to be judged against the $1.61 billion consensus estimate and the expected 20.27% year-over-year growth rate. Investors should compare that result with the company’s current 24.2% revenue growth rate to see whether momentum is accelerating or slowing. On the chart, $334.80 is the first threshold because it is the 20-day moving average and currently sits above the stock. A move through $359.55 would clear the 30-day high, while a decline toward $273.96 would test near-term support. Watch whether analyst sentiment stays near the $406.24 target and strong-buy recommendation or shifts toward the recent Hold downgrade. The thesis strengthens if growth holds and price retakes resistance; it weakens if revenue disappoints and support fails.
Analyst Consensus
STRONG BUY

Based on 26 analyst opinions
Low Target
$300.00
Mean Target
$406.24
High Target
$470.00


Earnings and Financial Data

Sector
Technology
Industry
Software – Application
Employees
15,445
Earnings & Dividends
Next Earnings
Oct 26, 2026
EPS (Trailing)
$5.03
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is CDNS a good stock to buy?
CDNS has 24.2% revenue growth and a strong-buy recommendation from 26 analysts. The tradeoff is its high P/E of 65.05, so the takeaway is that CDNS offers strong growth but carries substantial valuation risk.
What is CDNS’s price target?
The analyst target is $406.24, with estimates ranging from $300.00 to $470.00. The takeaway is that analysts see upside overall, but the wide range signals meaningful uncertainty.
Is CDNS overvalued?
CDNS trades at a P/E ratio of 65.05 while revenue is growing 24.2%. The takeaway is that the valuation is demanding and requires sustained growth.
What are the key support and resistance levels for CDNS?
Near-term support is the 30-day low of $273.96, while resistance is the 30-day high of $359.55. The takeaway is that those are the clearest technical levels to monitor.
Does CDNS pay a dividend?
The provided data does not include dividend information. The takeaway is that no dividend conclusion can be made from these figures alone.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 20, 2026.