ALTSTATION.IO

Abbott Laboratories (ABT) Stock Analysis

By Nova Skye | AltStation.io | Updated October 05, 2026

Price
$97.24
Change
+0.57%
Market Cap
$168.26B
Avg Volume
9.6M

Company Overview

Headquartered in Abbott Park, Illinois, Abbott Laboratories operates across the healthcare sector with its strongest focus on medical devices. Founded in 1888, the company generates revenue across four distinct divisions: Medical Devices, Diagnostic Products, Nutritional Products, and Established Pharmaceuticals. It sells generic medications, point-of-care diagnostic testing systems, adult and infant nutrition formulas, and specialized cardiovascular and neuromodulation hardware. Buyers include global hospital networks, clinical laboratories, blood banks, and individual consumers managing chronic illnesses.

Abbott is an established market leader whose primary competitive edge lies in scale and product breadth. Its crown jewel is the FreeStyle Libre continuous glucose monitor, which drove the Diabetes Care segment to 6.8 billion dollars in revenue in 2024. Medtronic, Boston Scientific, and Dexcom give Abbott fierce competition across structural heart, rhythm management, and diabetes sensors. Even with persistent pricing pressure and device iteration cycles from rivals, Abbott’s mix of high-margin devices and staple consumer nutrition provides a cash flow floor that pure-play medtech rivals cannot match.

The business is growing steadily, generating 42.0 billion dollars in total revenue in 2024, up from 40.1 billion dollars in 2023. Medical Devices is the company’s clear growth engine, accounting for 19 billion dollars in 2024 sales behind double-digit gains in electrophysiology and diabetes care. Abbott has fully moved past the drop in pandemic-era rapid testing demand and is actively directing capital into automated insulin delivery partnerships and cardiovascular pipelines. It is one of the most reliable large-cap plays in healthcare, provided it keeps defending its diabetes turf against Dexcom.

Key Financials
Market Cap
$168.26B
Revenue
$46.58B
EBITDA
$11.68B
Gross Margin
56.8%
Profit Margin
11.6%
Revenue Growth
13.0%
Total Cash
$5.60B
Total Debt
$32.72B
Free Cash Flow
$7.21B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
31.47
Forward P/E
16.03
Beta
0.59
52-Week High
$135.37
52-Week Low
$81.97
EPS
$3.09
50-Day Avg
$106.90
200-Day Avg
$104.17
Price/Book
3.29
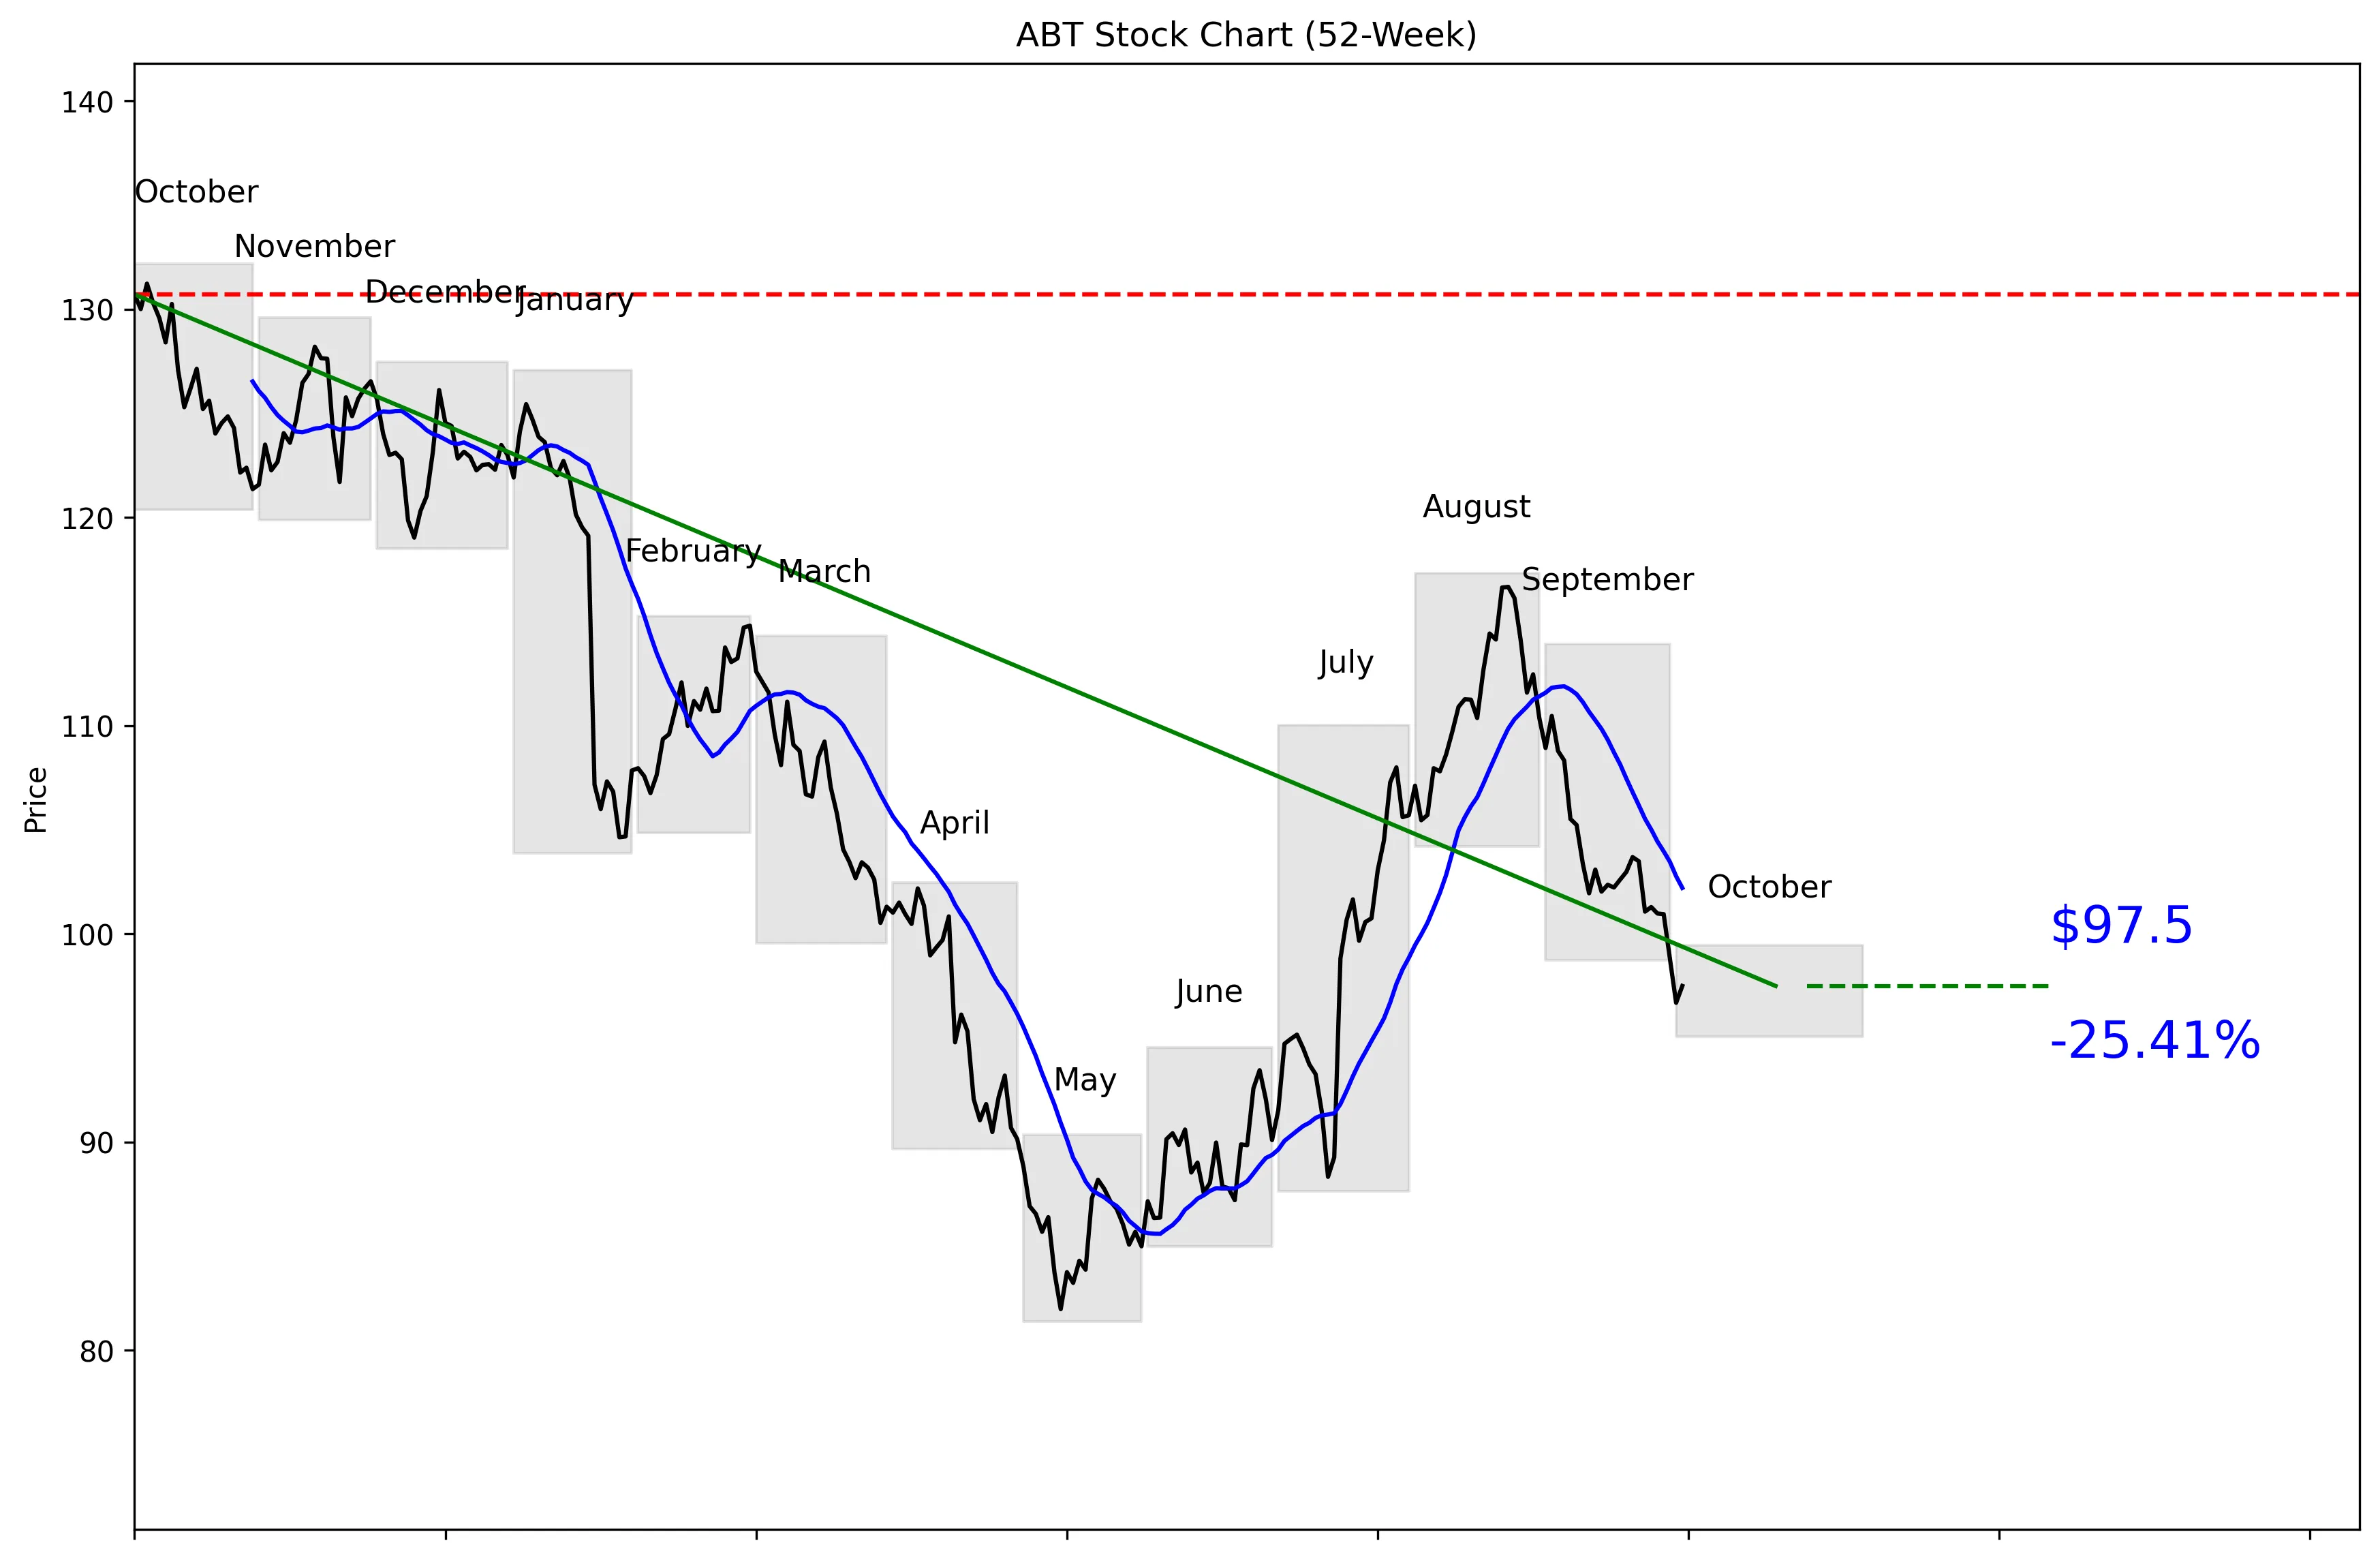
ABT 52-Week Stock Chart
Technical Analysis
ABT trades at $97.24, just 32% of the way from its $81.39 52-week low to its $132.18 high. The stock is 26.24% below that high and 19.79% above the low. Price sits 4.61% below the 20-day moving average of $102.21. Momentum is negative, with declines of 3.74% over five trading days and 10.38% over 20 trading days. Near-term support is $96.69, while resistance stands at $116.67.


Recent News and Developments

Rothschild upgrades Abbott to Buy

Rothschild & Co Redburn upgraded ABT from Neutral to Buy and raised its price target from $119 to $127. The firm expects 10.6% organic growth from Medical Devices and 11.7% growth from diabetes technology in fiscal 2026. Source: Investing.com

Abbott launches SimpleScreen CRC blood test

Abbott launched SimpleScreen CRC, an FDA-approved blood test for average-risk adults age 45 and older. The test delivered 81.1% colorectal-cancer sensitivity and 90.4% specificity for advanced colorectal neoplasia in a study of more than 48,000 adults. Source: Abbott

Abbott sets October 21 earnings date

Abbott will release third-quarter 2026 results before the market opens on October 21. Its earnings call starts at 8 a.m. Central time. Source: Abbott


Market Sentiment and Analyst Recommendations

Bull Case
Abbott generated $46.58 billion in revenue, with revenue growth running at 13.0%. Rothschild & Co Redburn upgraded ABT from Neutral to Buy and raised its target from $119 to $127. The firm expects 10.6% organic growth from Medical Devices and 11.7% growth from diabetes technology in fiscal 2026. Abbott also launched SimpleScreen CRC, an FDA-approved blood test for average-risk adults age 45 and older. The test delivered 81.1% colorectal-cancer sensitivity and 90.4% specificity for advanced colorectal neoplasia in a study of more than 48,000 adults. With ABT at $97.24 and the consensus analyst target at $120.58, the case for buying here rests on continued double-digit growth and recovery from a 26.24% drop below the 52-week high.
Bear Case
ABT is not obviously cheap at 31.47 times earnings. The balance sheet carries $32.72 billion in total debt against $5.60 billion in cash. Price action is weak, with the stock down 10.38% over the last 20 trading days and trading 4.61% below its 20-day moving average. ABT is also only $0.55 above near-term support at $96.69, so another decline could break an important 30-day level. The stock remains 19.79% above its 52-week low, leaving room for further downside if growth disappoints. Abbott needs its 13.0% revenue growth and Medical Devices momentum to justify the valuation.
What to Watch
Abbott reports third-quarter 2026 results before the market opens on October 21, with its earnings call scheduled for 8 a.m. Central time. Revenue growth is the central metric, with the current figure at 13.0%. Investors should also watch whether Medical Devices and diabetes technology support Rothschild’s fiscal 2026 growth expectations of 10.6% and 11.7%, respectively. On the chart, $96.69 is the immediate downside threshold; a break would put the recent 30-day support behind the stock. A recovery above the $102.21 moving average would be the first sign that short-term momentum is improving. Clearing $116.67 resistance would strengthen the recovery thesis, while continued trading below the moving average would keep the technical picture weak.
Analyst Consensus
BUY

Based on 25 analyst opinions
Low Target
$103.00
Mean Target
$120.58
High Target
$135.00


Earnings and Financial Data

Sector
Healthcare
Industry
Medical Devices
Employees
122,000
Earnings & Dividends
Next Earnings
Oct 21, 2026
EPS (Trailing)
$3.09
Dividend Yield
261.0%
Payout Ratio
79.0%

Frequently Asked Questions

Is ABT a good stock to buy?
The analyst recommendation is buy based on 25 analysts, and revenue growth is 13.0%. The takeaway is that Wall Street is positive, but the 31.47 P/E demands continued growth.
What is ABT’s price target?
The consensus analyst target is $120.58, with estimates ranging from $103.00 to $135.00. The takeaway is that every listed target is above the current $97.24 price.
Is ABT stock overvalued?
ABT trades at a P/E of 31.47 while revenue growth is 13.0%. The takeaway is that investors are paying a premium valuation for double-digit growth.
What are ABT’s support and resistance levels?
Near-term support is $96.69, and near-term resistance is $116.67. The takeaway is that ABT is trading close to support and well below resistance.
How strong is Abbott’s balance sheet?
Abbott has $5.60 billion in total cash and $32.72 billion in total debt. The takeaway is that debt materially exceeds cash.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 05, 2026.