ALTSTATION.IO

Edwards Lifesciences Corporation (EW) Stock Analysis

By Nova Skye | AltStation.io | Updated September 19, 2026

Price
$84.30
Change
-2.85%
Market Cap
$48.54B
Avg Volume
4.1M

Company Overview

Edwards Lifesciences (EW) is a medical device company in the healthcare sector, headquartered in Irvine, California, and founded in 1958. They build and sell specialized technologies to treat advanced cardiovascular disease, primarily focusing on damaged heart valves. Their core product portfolio includes transcatheter aortic valve replacements under the Edwards SAPIEN brand, transcatheter mitral and tricuspid therapies under the PASCAL and EVOQUE brands, and surgical structural heart lines including INSPIRIS RESILIA, KONECT RESILIA, and MITRIS RESILIA. They distribute these devices directly and through independent distributors to hospital networks, cardiac surgeons, and interventional cardiologists across the United States, Europe, Japan, and international markets.

Edwards holds the position of an established market leader in structural heart therapies rather than a niche player. Their primary technological edge lies in proprietary engineering like RESILIA tissue and VFit technology, which provide durability advantages and drive high clinical adoption. Competitive pressure in the medical device sector centers on competing catheter delivery systems and alternative surgical repair devices. Edwards defends its market position by leveraging its direct global sales force and maintaining comprehensive clinical coverage across aortic, mitral, and tricuspid conditions.

The company is actively executing a strategic pivot to expand beyond its traditional aortic valve core into transcatheter mitral and tricuspid interventions. Scaling therapies like EVOQUE and PASCAL represents a major milestone to capture high-unmet-need valve repair and replacement procedures worldwide. Concurrently, Edwards continues anchoring its surgical structural heart segment with specialized products like the pre-assembled KONECT RESILIA conduit for complex combined surgeries. This decisive transition into multi-valve transcatheter solutions sets up Edwards to drive long-term procedure volume growth across international cardiovascular care.

Key Financials
Market Cap
$48.54B
Revenue
$6.51B
EBITDA
$2.00B
Gross Margin
77.8%
Profit Margin
15.4%
Revenue Growth
13.6%
Total Cash
$4.25B
Total Debt
$704.40M
Free Cash Flow
$1.23B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
50.18
Forward P/E
24.96
Beta
0.85
52-Week High
$96.29
52-Week Low
$72.30
EPS
$1.68
50-Day Avg
$89.38
200-Day Avg
$84.98
Price/Book
4.58
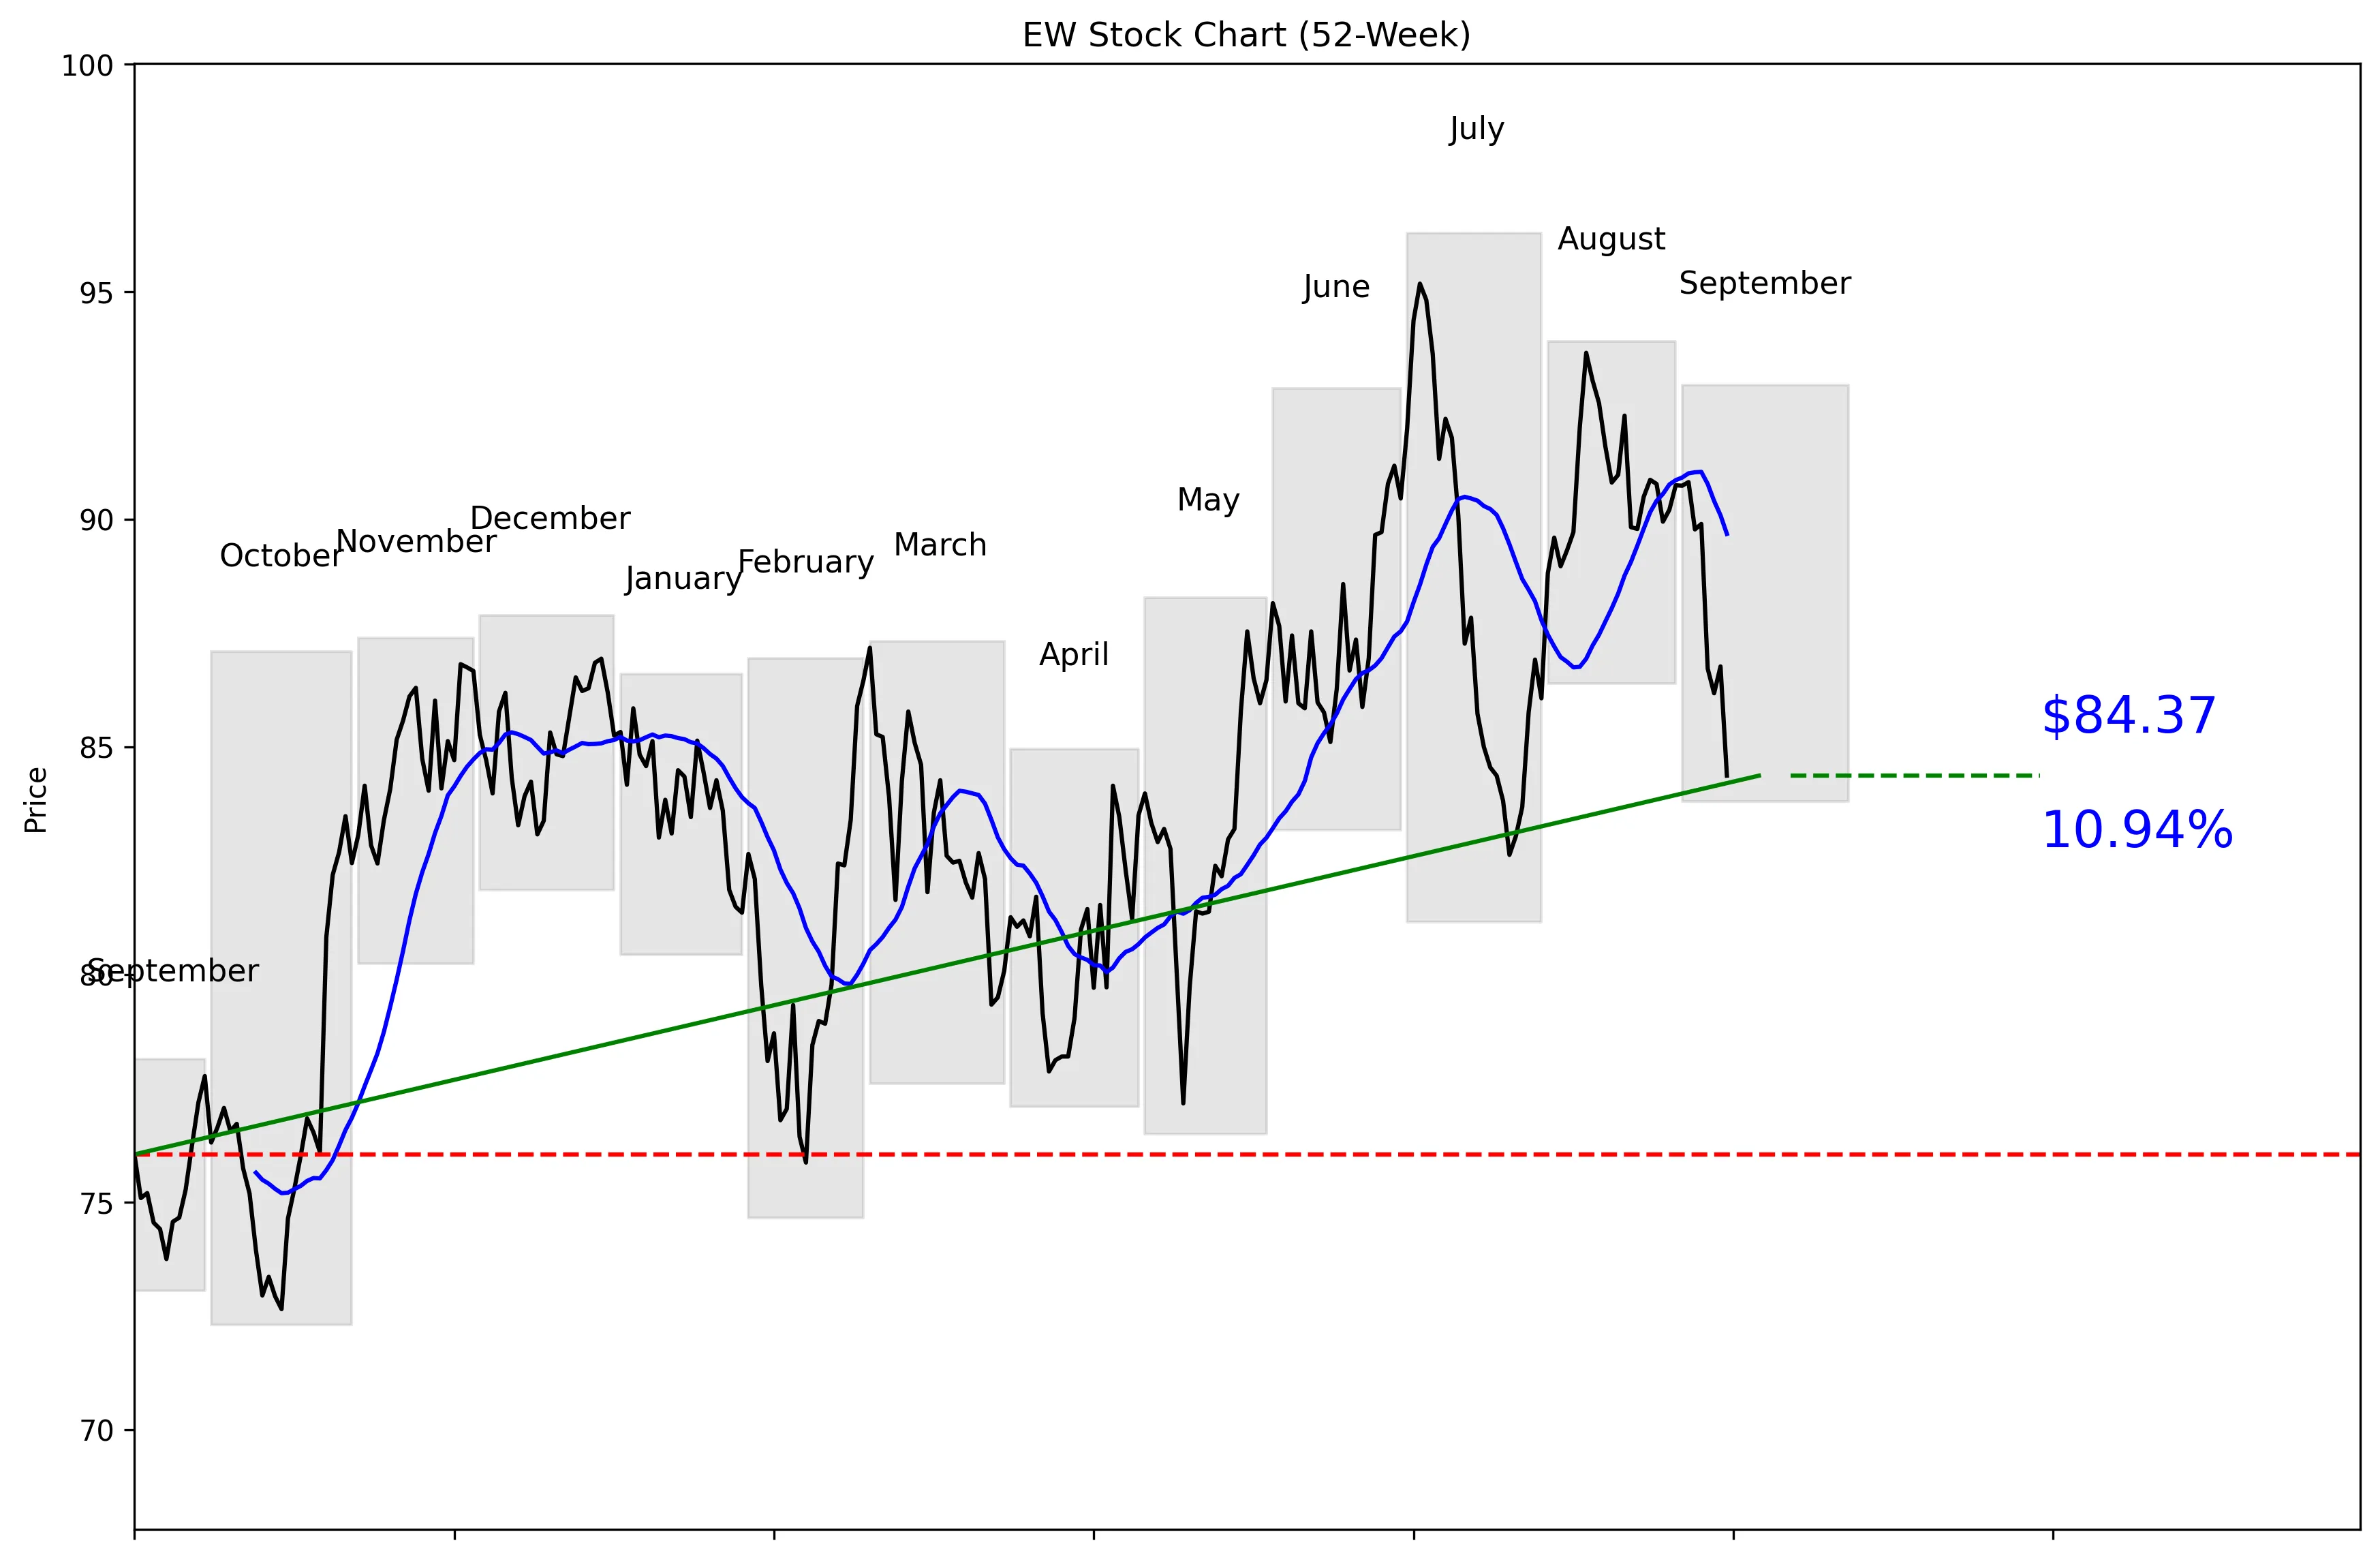
EW 52-Week Stock Chart
Technical Analysis
EW trades at $84.30 within a 52-week range of $72.30 to $96.29. The stock is 50% of the way from its 52-week low to its high, sitting 12.38% below the high and 16.69% above the low. Price is 5.92% below the 20-day moving average of $89.68. Momentum is negative, with declines of 6.03% over five trading days and 8.85% over 20 trading days. Near-term support is $84.37, while resistance is $93.66.


Recent News and Developments

CMS expands Medicare coverage for TAVR

CMS issued an updated Medicare National Coverage Determination on September 10. It adds conditional coverage for TAVR in asymptomatic severe aortic stenosis and ends evidence-development requirements for symptomatic severe aortic stenosis and non-FDA-approved uses. Source: Centers for Medicare & Medicaid Services

Edwards reaffirms 2026 financial outlook

Edwards maintained its 2026 financial outlook following the updated Medicare coverage decision. Management said implementation will take time and plans to provide 2027 and longer-term guidance at its December investor conference. Source: MT Newswires

Stifel calls TAVR decision positive for Edwards

Stifel said the final CMS decision is constructive for Edwards because of its leadership in the TAVR market. The firm estimates TAVR is a global market exceeding $7 billion and generates roughly 75% of Edwards’ revenue. Source: Investing.com


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is growing 13.6%, supported by a latest-quarter increase of 13.6% year over year. That quarter also beat expectations, with adjusted earnings of $0.78 per share versus $0.74 expected and revenue of $1.74 billion versus $1.70 billion expected. CMS expanded Medicare coverage for TAVR, including conditional coverage for asymptomatic severe aortic stenosis. Stifel estimates TAVR exceeds $7 billion globally and accounts for roughly 75% of Edwards’ revenue, making broader coverage a meaningful demand catalyst. The balance sheet is strong, with $4.25 billion in cash against $704.40 million in debt. The average analyst target is $100.96 versus an $84.30 share price, and 26 analysts collectively rate EW a buy. The buy case is straightforward: solid growth, substantial net cash, stronger TAVR coverage, and analyst targets above the current price.
Bear Case
A P/E of 50.18 is demanding for a company growing revenue at 13.6%. Investors are already paying heavily for continued execution, leaving little room for slower growth or disappointing guidance. Edwards also has major concentration risk because TAVR generates roughly 75% of revenue. Canaccord maintained a Hold rating and an $85 target, arguing that the Medicare coverage catalyst is largely reflected in the stock. The chart confirms weak sentiment: EW is 5.92% below its 20-day moving average after falling 6.03% over five trading days and 8.85% over 20 trading days. At $84.30, the stock is also below the stated near-term support of $84.37. Management warned that implementation of the CMS decision will take time, so the catalyst may not produce an immediate financial boost.
What to Watch
The first test is how quickly the September 10 CMS coverage decision translates into additional TAVR demand. Management has maintained its 2026 outlook, so any change to that guidance would materially affect the thesis. The December investor conference is the next major event because Edwards plans to provide 2027 and longer-term guidance there. Investors should track whether revenue growth holds near 13.6% and whether future results continue beating benchmarks like the latest quarter’s $0.78 adjusted earnings per share and $1.74 billion in revenue. On the chart, $84.37 is the immediate threshold to reclaim, followed by the $89.68 moving average and $93.66 resistance. Failure to recover $84.37 would leave the stock exposed to further weakness within its $72.30 to $96.29 annual range. The analyst split also matters: Canaccord’s $85 target supports limited upside, while BTIG’s $110 target reflects a much stronger growth outlook.
Analyst Consensus
BUY

Based on 26 analyst opinions
Low Target
$84.00
Mean Target
$100.96
High Target
$110.00


Earnings and Financial Data

Sector
Healthcare
Industry
Medical Devices
Employees
16,000
Earnings & Dividends
Next Earnings
Oct 29, 2026
EPS (Trailing)
$1.68
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is EW a good stock to buy?
EW has a buy recommendation from 26 analysts and an average target of $100.96 versus its current price of $84.30. The takeaway is that analysts see upside, but the 50.18 P/E makes execution critical.
What is EW’s price target?
The average analyst target is $100.96, with estimates ranging from $84.00 to $110.00. The takeaway is that the low end sits below the current $84.30 price while the average and high-end targets point higher.
Is EW stock overvalued?
EW trades at a P/E of 50.18 while revenue is growing 13.6%. The takeaway is that the valuation is expensive and requires sustained growth.
What are EW’s support and resistance levels?
Near-term support is $84.37, and near-term resistance is $93.66. The takeaway is that the current $84.30 price is below support and remains 5.92% under the $89.68 moving average.
Does Edwards Lifesciences have a strong balance sheet?
Edwards has $4.25 billion in cash and $704.40 million in total debt. The takeaway is that cash substantially exceeds debt.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated September 19, 2026.