ALTSTATION.IO

Agilent Technologies, Inc. (A) Stock Analysis

By Nova Skye | AltStation.io | Updated November 01, 2026

Price
$174.87
Change
-3.47%
Market Cap
$49.31B
Avg Volume
2.2M

Company Overview

Agilent Technologies, headquartered in Santa Clara, California, is an established fixture in the Healthcare sector focusing on Diagnostics & Research. The company sells analytical instruments, software, consumables, and laboratory services to life science research labs, clinical diagnostics facilities, and chemical testing centers worldwide. Their core hardware portfolio centers on chromatography and mass spectrometry systems, which scientists use to separate, identify, and quantify chemical and biological compounds. Through its CrossLab and Applied Markets divisions, Agilent also generates steady business from maintenance services, columns, custom chemistries, and OpenLab workflow software.

Agilent operates as a tier-one market leader in analytical lab equipment, competing directly against major rivals like Thermo Fisher Scientific, Danaher, and Waters Corporation. Its primary competitive advantage is high customer switching costs; once a pharmaceutical lab validates its workflows on Agilent hardware and OpenLab software, ripping and replacing that setup is costly and risky. Furthermore, its CrossLab consumables and services segment creates a dependable recurring revenue base, generating over 25% of total sales. The primary vulnerability is cyclical customer spending, as biopharma budget pullbacks hit new instrument orders quickly.

The company is navigating a cyclical slump in lab instrument purchases, reporting $6.51 billion in revenue for fiscal 2024, down 4.7% year-over-year. To manage softer equipment sales, Agilent streamlined operations across three reportable segments—Life Sciences and Diagnostics, Agilent CrossLab, and Applied Markets—aiming to expand high-margin service contracts and recurring consumables. The business is also directing capital toward faster-growing niches like clinical diagnostics, pathology, and automated liquid handling. Agilent is fundamentally sound with sticky customer relationships, but real acceleration will require global biopharma capital spending to turn back positive.

Key Financials
Market Cap
$49.31B
Revenue
$7.37B
EBITDA
$2.08B
Gross Margin
53.6%
Profit Margin
19.5%
Revenue Growth
8.1%
Total Cash
$1.76B
Total Debt
$4.15B
Free Cash Flow
$1.06B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
34.49
Forward P/E
25.99
Beta
1.21
52-Week High
$182.99
52-Week Low
$108.35
EPS
$5.07
50-Day Avg
$164.09
200-Day Avg
$136.06
Price/Book
6.70
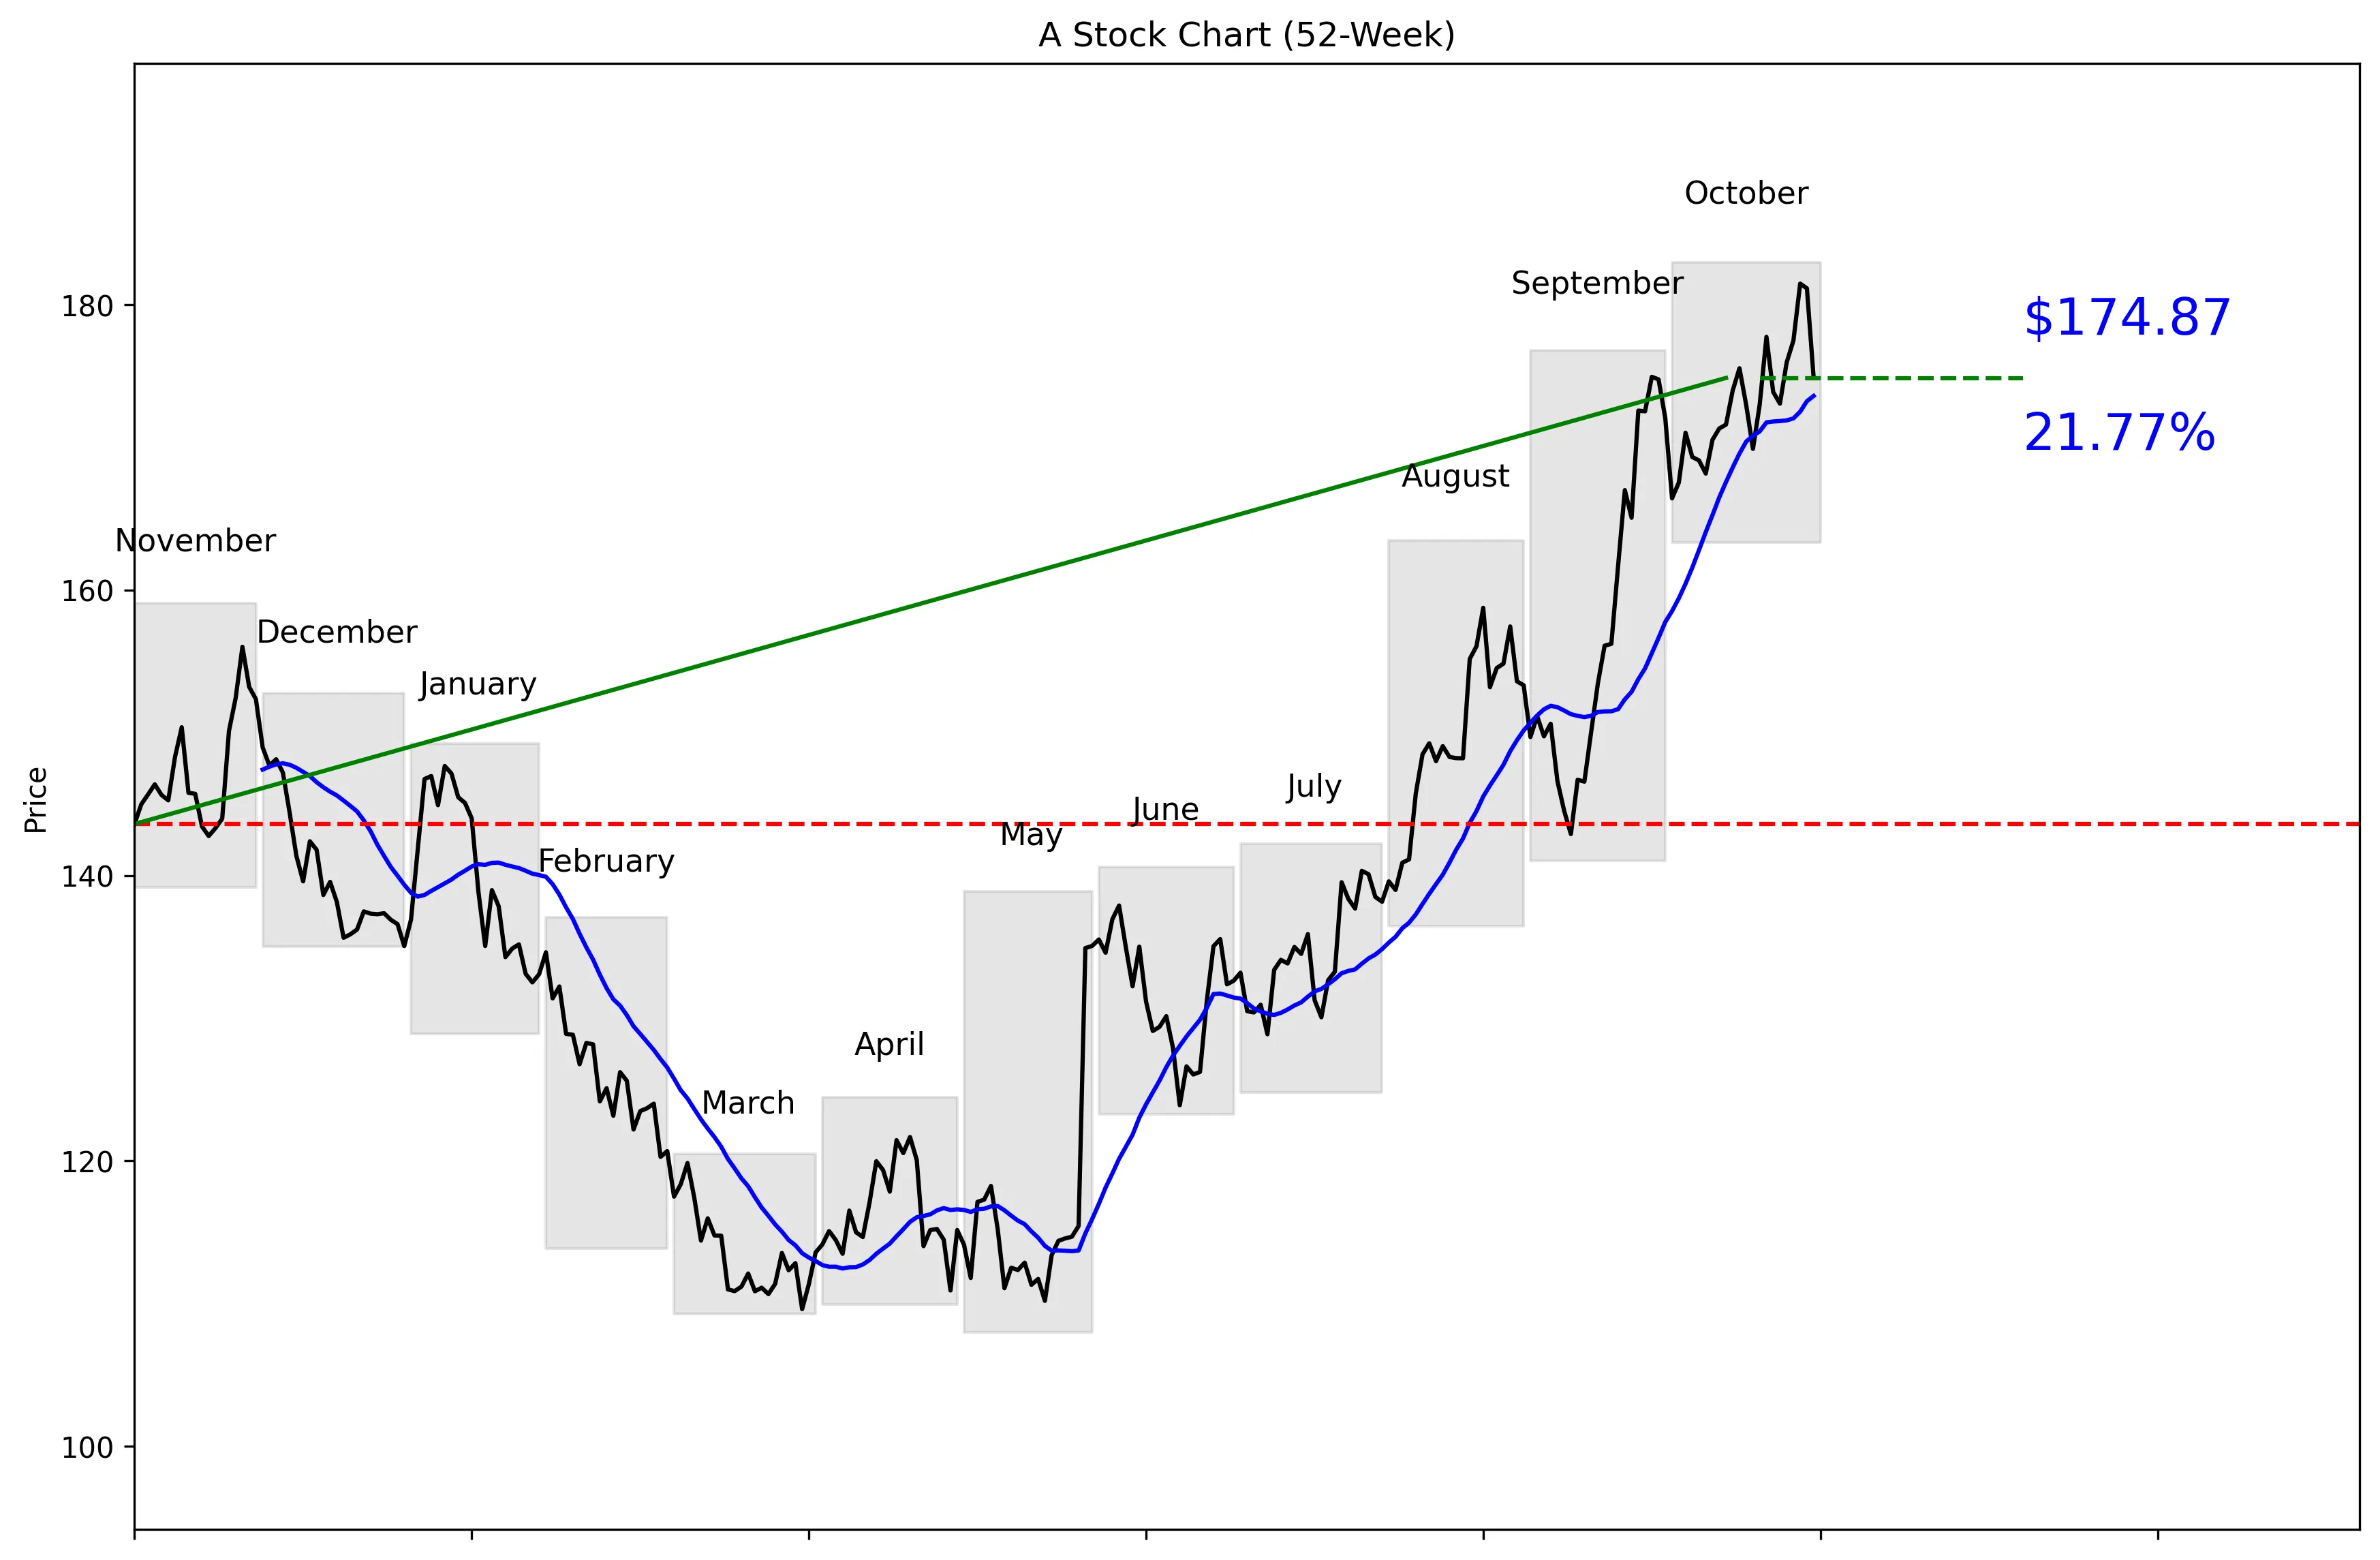
A 52-Week Stock Chart
Technical Analysis
Agilent trades at $174.87, putting it 89% of the way from its 52-week low of $107.98 to its high of $182.99. The stock is 4.44% below that high and 61.95% above the low. Price sits 0.73% above the 20-day moving average of $173.61. Momentum remains positive at 1.04% over five trading days and 4.38% over 20 trading days. Near-term support is $161.70, while resistance is $181.48.


Recent News and Developments

Deutsche Bank starts Agilent at Buy with $190 target

Deutsche Bank analyst Justin Bowers initiated coverage of Agilent on October 26 with a Buy rating and a $190 price target. It was the only new major analyst action found during the past week. Source: PriceTargets.com

Agilent and University of Chicago launch battery research center

Agilent and the University of Chicago announced a Center of Excellence for Energy Materials Research on October 27. Researchers will use Agilent mass spectrometry and atomic spectroscopy equipment to study materials for electric-vehicle, connected-device and grid-storage batteries. Source: StockTitan

Agilent sets November 23 earnings date

Agilent will report fourth-quarter fiscal 2026 results after the market closes on November 23. Management will hold its conference call at 1:30 p.m. PST, and the recording will remain available for 90 days. Source: Agilent Technologies


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is growing 8.1%, giving Agilent a measurable fundamental growth driver. The company generated $7.37 billion in revenue and holds $1.76 billion in cash. Deutsche Bank initiated coverage with a Buy rating and a $190 target on October 26. That target sits above the broader analyst consensus of $182.05, while the high target reaches $200.00. Agilent’s battery research center with the University of Chicago could expand the use of its mass spectrometry and atomic spectroscopy equipment in electric-vehicle, connected-device, and grid-storage research. The stock also has positive five-day and 20-day momentum, so buyers have both operating growth and a near-term catalyst in the November 23 earnings report.
Bear Case
Agilent is priced at 34.49 times earnings, which leaves little room for weak execution. The stock already sits 89% of the way through its 52-week range and only 4.44% below its high. The consensus analyst target of $182.05 is just $7.18 above the current price of $174.87. Debt of $4.15 billion exceeds cash of $1.76 billion by $2.39 billion. Friday’s 3.47% decline from $181.15 to $174.87 shows that selling pressure can appear quickly near the top of the range. A break below the $173.61 moving average would weaken the short-term setup, while a drop toward $161.70 would erase a meaningful portion of the recent advance.
What to Watch
Agilent reports fourth-quarter fiscal 2026 results after the market closes on November 23, followed by a conference call at 1:30 p.m. PST. Revenue growth is currently 8.1%, so the earnings report needs to show whether that pace is holding. Investors should also track whether the stock can reclaim the $181.48 near-term resistance level and challenge the $182.99 52-week high. A sustained move above those levels would support the bullish targets of $190 and $200. On the downside, watch the $173.61 moving average first and the $161.70 near-term support level next. The thesis improves if revenue growth remains firm and price clears resistance; it weakens if growth slows while the stock still commands a 34.49 P/E.
Analyst Consensus
BUY

Based on 20 analyst opinions
Low Target
$155.00
Mean Target
$182.05
High Target
$200.00


Earnings and Financial Data

Sector
Healthcare
Industry
Diagnostics & Research
Employees
18,200
Earnings & Dividends
Next Earnings
Nov 23, 2026
EPS (Trailing)
$5.07
Dividend Yield
58.0%
Payout Ratio
20.0%

Frequently Asked Questions

Is A a good stock to buy?
The analyst recommendation is buy based on 20 analysts, and revenue is growing 8.1%. The takeaway is that Wall Street is positive, but the 34.49 P/E makes valuation important.
What is A’s price target?
The analyst target is $182.05, with estimates ranging from $155.00 to $200.00. The takeaway is that the target range includes both downside and upside from the current $174.87 price.
How close is A stock to its 52-week high?
A trades at $174.87, which is 4.44% below its $182.99 52-week high. The takeaway is that the stock is already near the top of its annual range.
What are the support and resistance levels for A stock?
Near-term support is $161.70, and near-term resistance is $181.48. The takeaway is that these are the key 30-day levels to track.
Does A pay a dividend?
The provided key and technical data do not include dividend information. The takeaway is that dividend status cannot be determined from these figures.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated November 01, 2026.