
GE HealthCare Technologies Inc. (GEHC) Stock Analysis
By Nova Skye | AltStation.io | Updated October 07, 2026
Company Overview
GE HealthCare Technologies Inc. is a Chicago-based medical device company that builds the essential hardware and software hospital systems rely on to diagnose and treat patients. The business operates across four main divisions: Imaging, Advanced Visualization Solutions, Patient Care Solutions, and Pharmaceutical Diagnostics. They sell heavy-duty clinical hardware like CT scanners, MRI machines, and X-ray systems, alongside bedside patient monitors, anesthesia devices, and ultrasound equipment. They also manufacture the proprietary contrast agents and radiopharmaceuticals that radiology clinics inject into patients to make diagnostic scans readable. Their customer base is direct and institutional, spanning hospitals, diagnostic centers, and healthcare providers globally.
GE HealthCare is an entrenched top-tier player in medical devices, competing head-to-head with Siemens Healthineers and Philips. The company holds a distinct operational edge because it sells both the multi-million-dollar imaging hardware and the recurring consumable contrast agents and servicing contracts required to run them. That massive global footprint creates high switching costs for hospitals that cannot easily swap complex imaging workflows. Even so, competition is intense; Siemens Healthineers generated roughly 24 billion dollars in fiscal 2024 revenue, staying ahead of GE HealthCare’s 19.67 billion dollars and pressuring the firm to defend its market share.
Since completing its corporate separation in December 2022, GE HealthCare has performed like a steady cash-flow engine looking for its next gear. Revenue moved from 19.55 billion dollars in 2023 to 19.67 billion dollars in 2024, which translates to a sluggish top-line growth rate of under 1%. To drive higher-margin growth, the company is pivoting toward embedded healthcare software and artificial intelligence, backed by moves like its strategic collaboration with DeepHealth. GE HealthCare is a defensive powerhouse with sticky institutional revenue, but management needs to translate its digital and diagnostic pipeline into faster organic growth to keep pace with the competition.
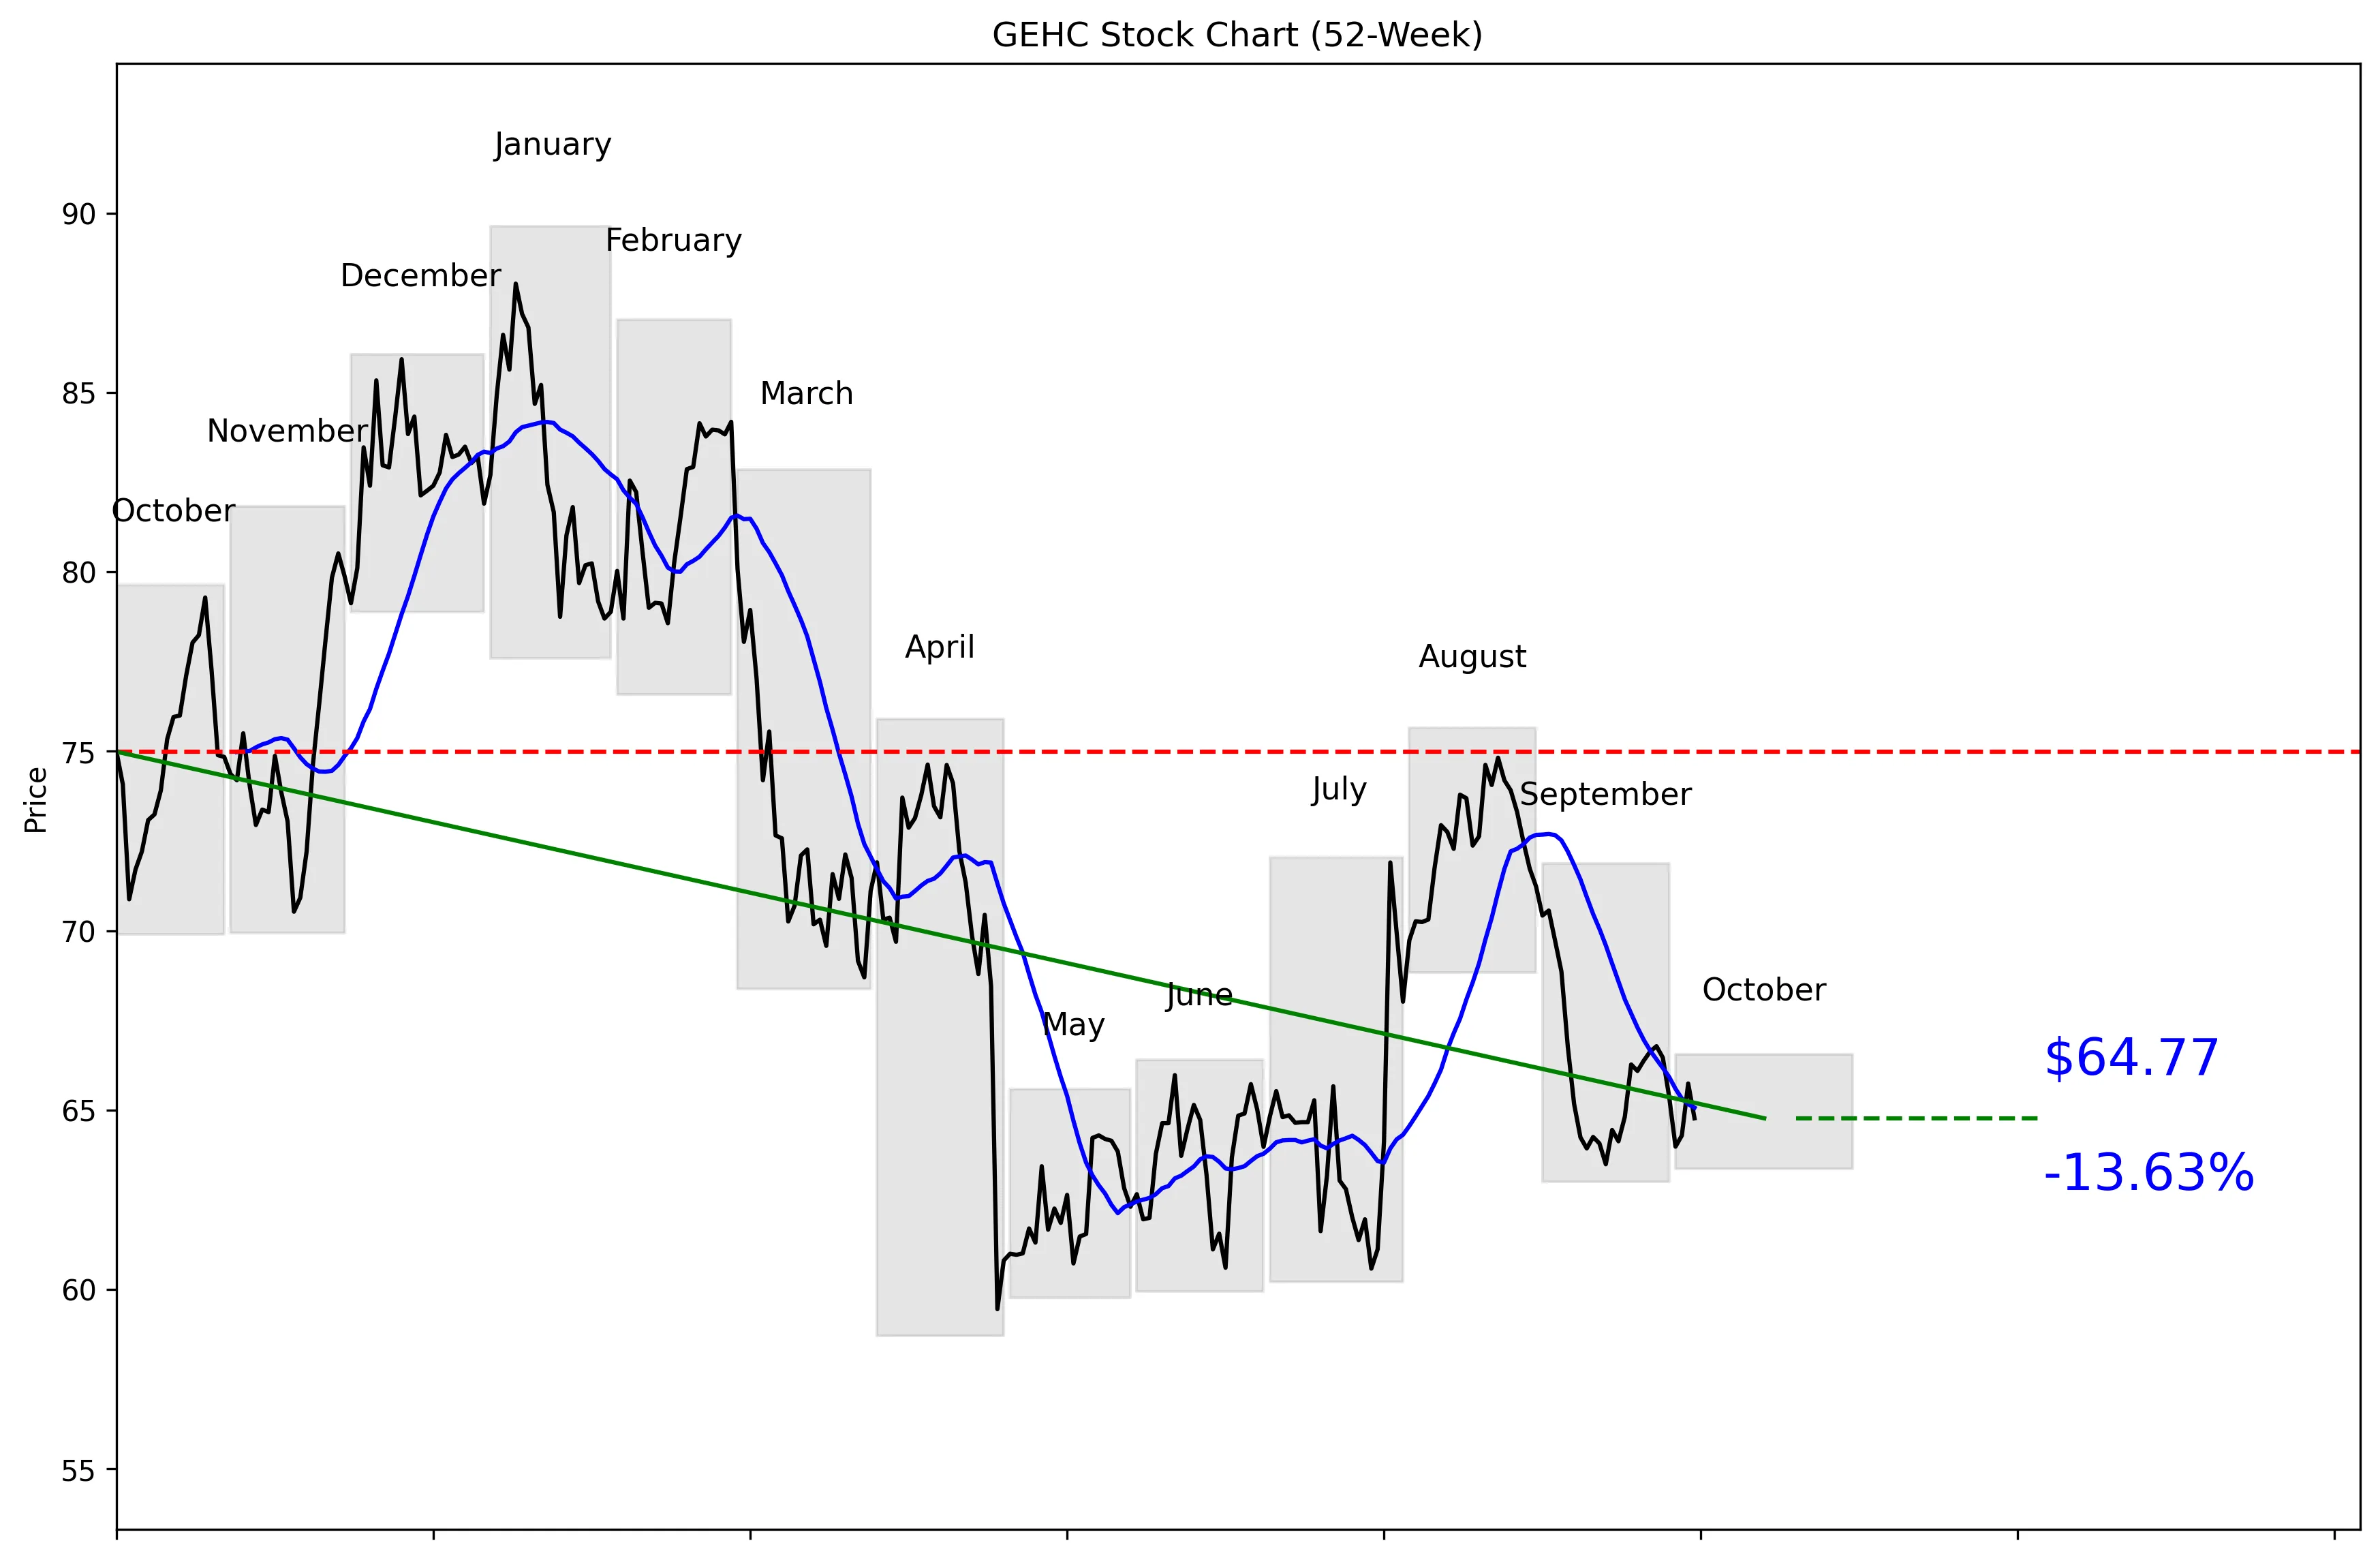
52-Week Price Performance Analysis
Recent News and Developments
GE HealthCare will release third-quarter 2026 results before the market opens on October 28. Management will hold its conference call at 8:30 a.m. Eastern Time the same day. Source: Business Wire
GE HealthCare will pay $945 million in cash for SOFIE Biosciences, adding 15 U.S. manufacturing sites, 21 cyclotrons and U.S. rights to the Phase III FAPI-74 cancer-imaging tracer. The deal is expected to close in the first half of 2027, subject to regulatory approval. Source: GE HealthCare
Citi lowered its GE HealthCare target from $75 to $71, a 5.3% reduction, while keeping a Neutral rating. The firm cited low expectations for the third quarter but sees pockets of growth and a possible recovery in 2027. Source: TipRanks
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports