ALTSTATION.IO

Quest Diagnostics Incorporated (DGX) Stock Analysis

By Nova Skye | AltStation.io | Updated September 09, 2026

Price
$237.08
Change
-0.03%
Market Cap
$26.17B
Avg Volume
957.3K

Company Overview

Quest Diagnostics runs one of the largest clinical laboratory networks in the United States, operating out of Secaucus, New Jersey within the Healthcare sector’s Diagnostics and Research industry. Founded in 1967, the company sells routine blood work, advanced anatomic pathology, neurology testing, and workplace toxicology across brands like AmeriPath, Dermpath Diagnostics, and ExamOne. Their customer base spans physicians, hospital systems, commercial health insurers, government agencies, employers, and retail consumers. They fulfill this volume through a nationwide network of patient service centers, hospital laboratories, and mobile phlebotomy professionals.

Quest operates as an established market leader in clinical testing, using its massive physical network to process high-volume orders at scale. That infrastructure creates a strong competitive edge because hospital systems and health plans contract with large national networks to keep per-test costs down. The primary operational threat comes from pricing pressure and margin compression driven by health plan reimbursement terms. Quest counters that risk by expanding higher-value specialty testing in oncology, genetics, and digital health connectivity through its Quanum platform.

The company is actively shifting its mix toward high-complexity specialty diagnostics and employer population health rather than relying only on routine blood work. Strategic focus has shifted toward advanced disease categories, including prenatal genetic profiling, oncology, and neurology testing for conditions like Alzheimer’s disease. Quest is also broadening non-clinical commercial revenue through workplace drug screenings, employer flu shot programs, and life insurance risk assessments. This multi-channel expansion keeps Quest deeply embedded as the core diagnostic engine for American healthcare providers and corporate clients.

Key Financials
Market Cap
$26.17B
Revenue
$11.56B
EBITDA
$2.27B
Gross Margin
33.2%
Profit Margin
9.2%
Revenue Growth
10.2%
Total Cash
$626.00M
Total Debt
$6.40B
Free Cash Flow
$909.63M


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
25.19
Forward P/E
19.66
Beta
0.55
52-Week High
$247.19
52-Week Low
$171.18
EPS
$9.41
50-Day Avg
$227.54
200-Day Avg
$201.08
Price/Book
3.47
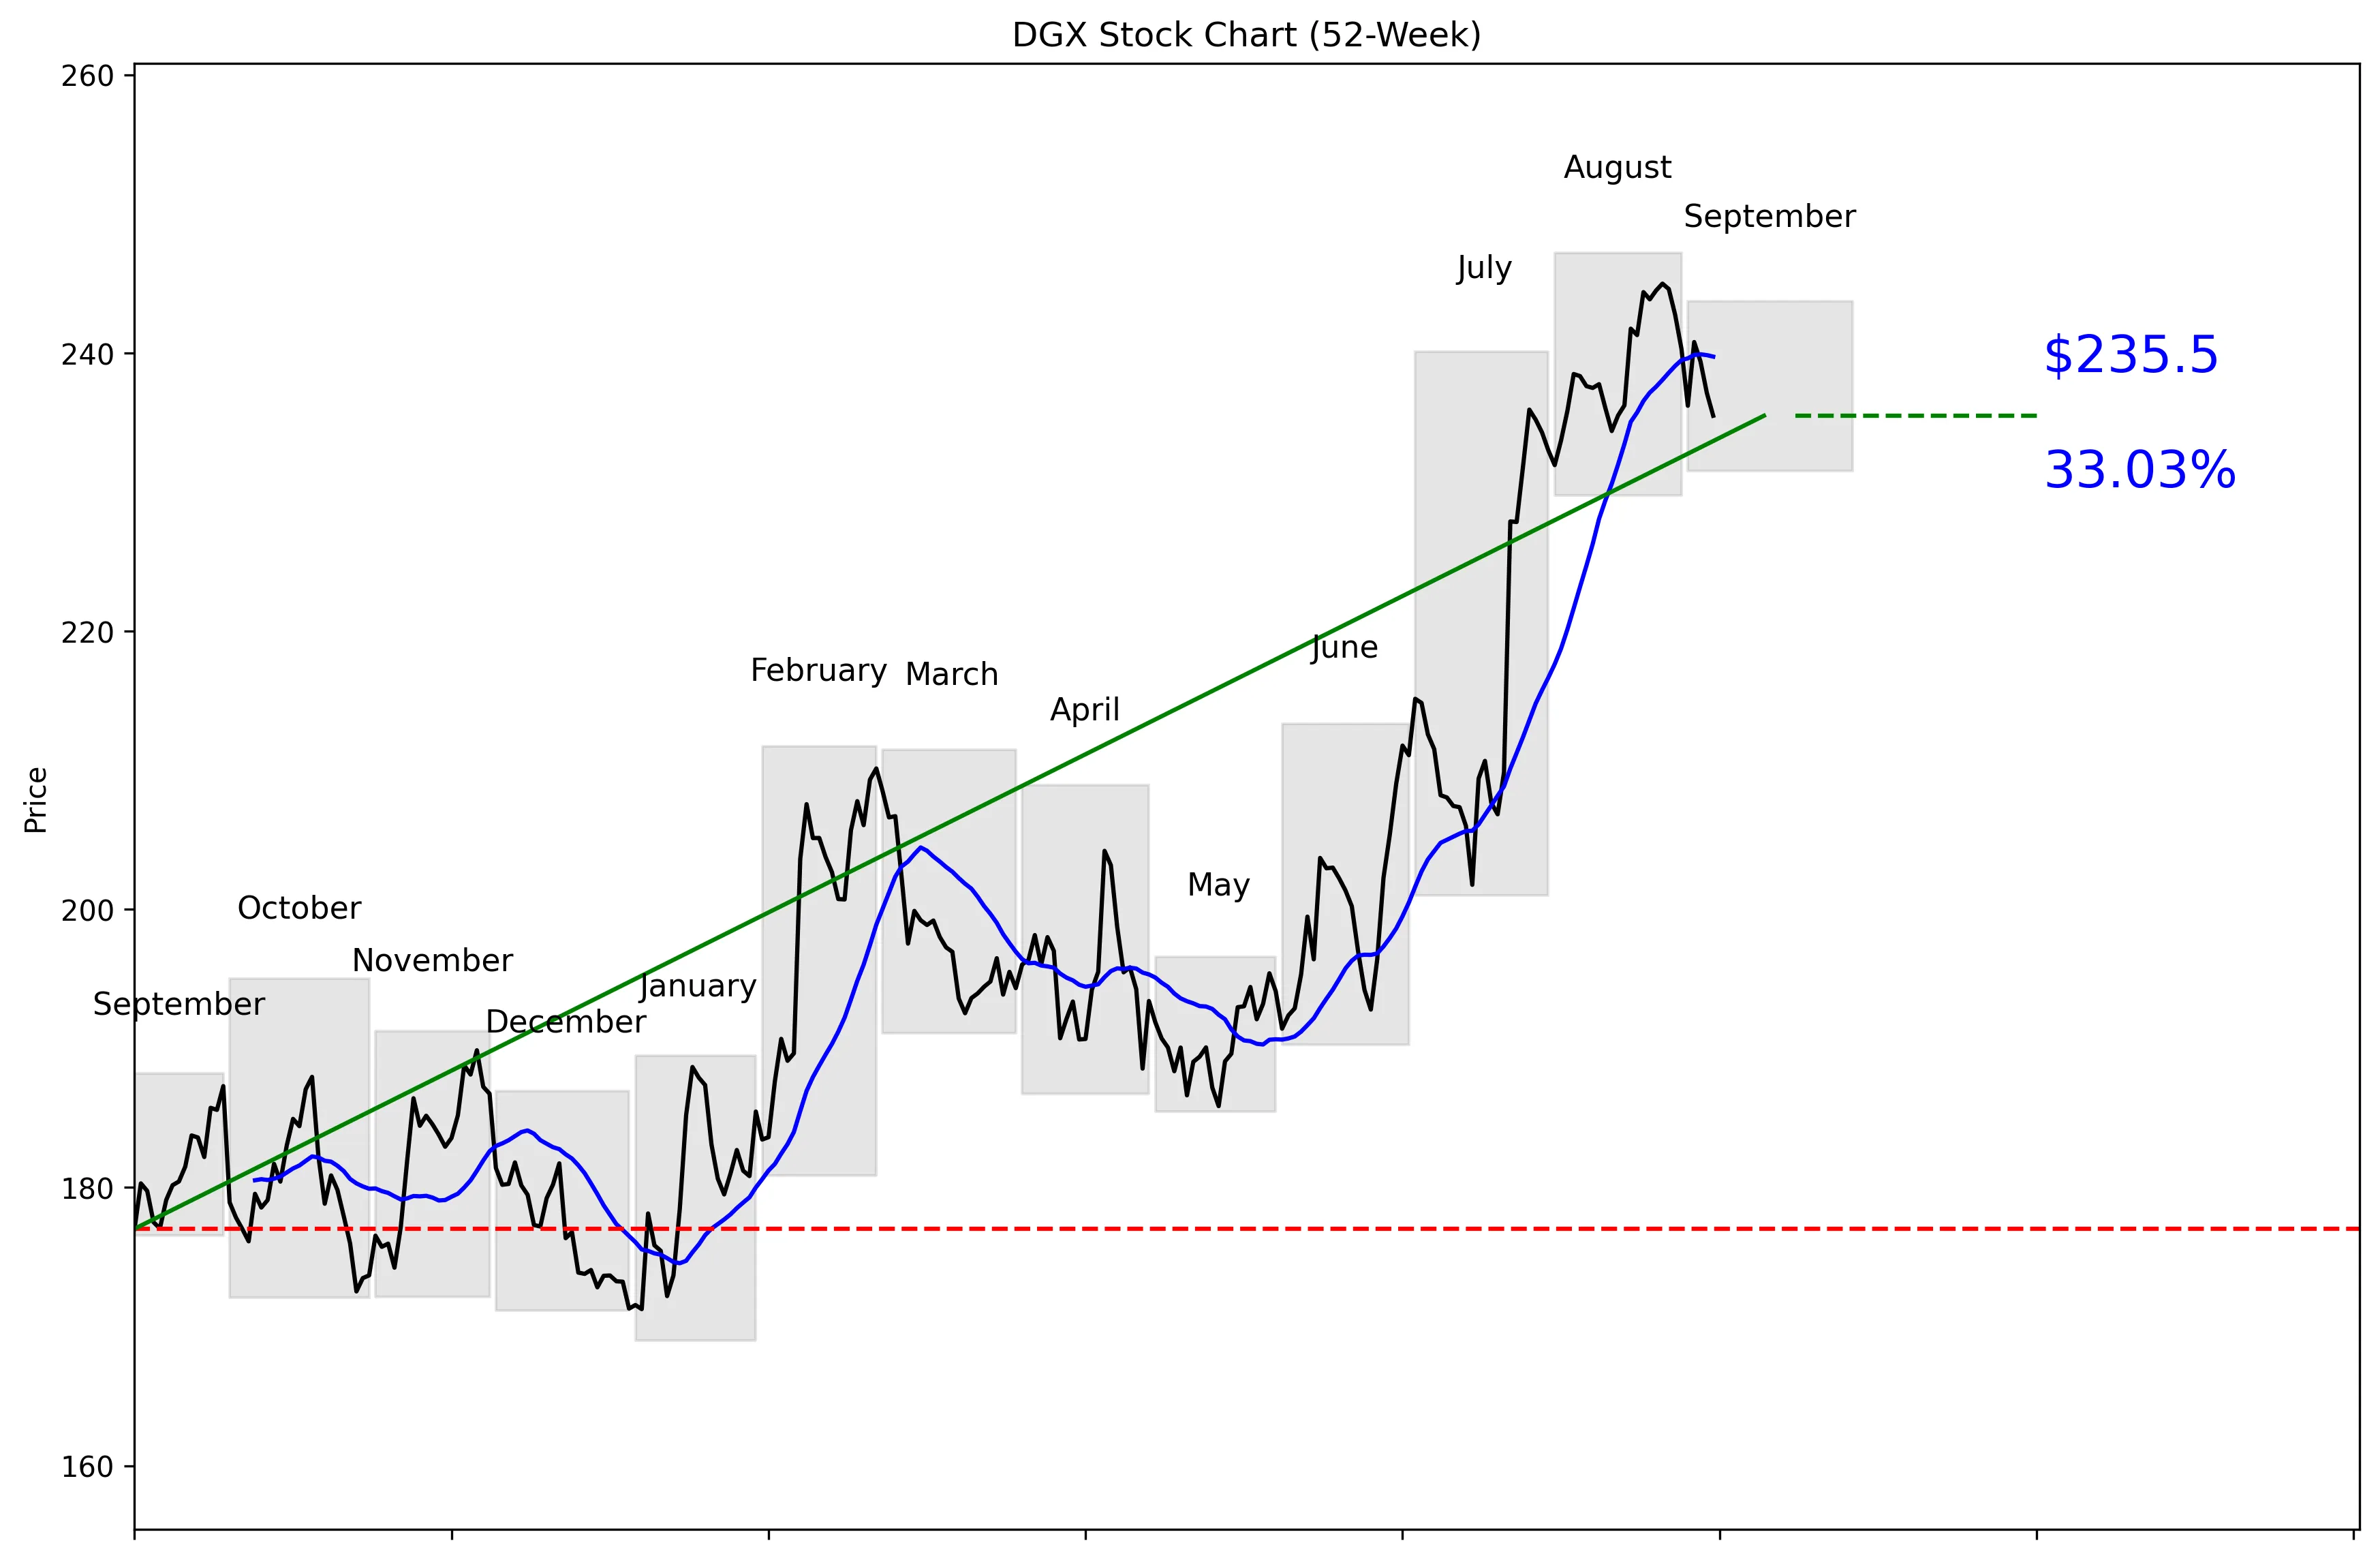
DGX 52-Week Stock Chart
Technical Analysis
DGX trades at $237.08, placing it 85% of the way from its $168.97 52-week low to its $247.19 high. The stock is 4.73% below that high and 39.37% above the low, so the longer-term trend remains strong. Short-term momentum has weakened, with shares down 2.00% over five trading days and 0.90% over 20 days. The price is also 1.77% below its $239.75 20-day moving average. Near-term support sits at $231.95, while $245.00 is the resistance level buyers need to break.


Recent News and Developments

UBS lifts DGX target to $245

UBS raised its Quest Diagnostics price target from $232 to $245, a 5.6% increase, while keeping a Neutral rating. The firm called testing volumes and mix durable after meeting with Quest management. Source: Investing.com

CEO reports $2.43 million planned stock sale

CEO James Davis disclosed the sale of 10,000 DGX shares at $242.72 each, worth $2.43 million, in a Form 4 filed September 3. The September 1 transaction occurred under a prearranged 10b5-1 plan and left him holding 122,423 shares. Source: EdgarHawk

DGX drops 2.20% across three sessions

DGX closed at $235.50 on September 8, down 2.20% from its $240.80 close on September 2. Shares fell 0.58% on September 3, 0.94% on September 4 and 0.69% on September 8, showing that the bullish UBS update did not stop the short-term pullback. Source: FinanceCharts


Market Sentiment and Analyst Recommendations

Bull Case
Quest Diagnostics is growing revenue at 10.2%, with total revenue reaching $11.56 billion. That growth gives investors a solid fundamental reason to look past the recent pullback. The analyst consensus is buy across 15 analysts, with a $245.87 target compared with the current $237.08 price. The upper analyst target of $265.00 shows that some analysts see room beyond the current 52-week high of $247.19. UBS also raised its target from $232 to $245 after describing testing volumes and mix as durable following a meeting with management. DGX remains only 4.73% below its 52-week high despite negative five-day and 20-day momentum. The bull case is straightforward: revenue is growing, analysts remain positive, and a move above $245.00 could put the stock back near its high.
Bear Case
DGX trades at 25.19 times earnings, which leaves less room for operational disappointment. The stock is already 85% of the way through its 52-week range and sits 39.37% above its low. The consensus target of $245.87 is only modestly above the current $237.08 price, limiting the obvious valuation upside. UBS raised its target to $245 but maintained a Neutral rating, which is not a strong endorsement at the current price. Quest holds $626.00 million in cash against $6.40 billion in total debt, making the debt load a real balance-sheet concern. CEO James Davis sold 10,000 shares at $242.72 under a prearranged plan, leaving him with 122,423 shares; the planned nature matters, but the sale does not strengthen sentiment. With the stock below its $239.75 moving average and short-term momentum negative, a break under $231.95 would weaken the setup.
What to Watch
The first threshold is $239.75, the 20-day moving average that DGX currently trails by 1.77%. A recovery above that level would show that the recent pullback is losing force. The next test is $245.00 resistance, followed by the $247.19 52-week high. On the downside, investors should monitor $231.95 support because a break would confirm further near-term weakness. Revenue growth needs to remain close to the reported 10.2% rate to support a 25.19 P/E. Investors should also track whether testing volumes and mix continue to match the durable conditions cited by UBS. The analyst target range of $204.00 to $265.00 shows wide disagreement, so future target changes could materially shift the thesis.
Analyst Consensus
BUY

Based on 15 analyst opinions
Low Target
$204.00
Mean Target
$245.87
High Target
$265.00


Earnings and Financial Data

Sector
Healthcare
Industry
Diagnostics & Research
Employees
46,000
Earnings & Dividends
Next Earnings
Oct 20, 2026
EPS (Trailing)
$9.41
Dividend Yield
145.0%
Payout Ratio
26.1%

Frequently Asked Questions

Is DGX a good stock to buy?
DGX has a buy recommendation from 15 analysts, 10.2% revenue growth, and a consensus target of $245.87. The takeaway is that the fundamental outlook is positive, but the target offers limited room above the current $237.08 price.
What is DGX’s price target?
The analyst target is $245.87, with estimates ranging from $204.00 to $265.00. The takeaway is that analysts disagree significantly about DGX’s upside and downside.
Is DGX stock near its 52-week high?
DGX is 4.73% below its $247.19 52-week high and sits 85% of the way from its $168.97 low to that high. The takeaway is that the stock is trading near the upper end of its annual range.
What are DGX’s support and resistance levels?
Near-term support is $231.95, while near-term resistance is $245.00. The takeaway is that these are the key levels to watch for the next directional move.
Does DGX pay a dividend?
The provided data does not include dividend information. The takeaway is that no dividend conclusion can be made from the available figures.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated September 09, 2026.