
Global Payments Inc. (GPN) Stock Analysis
By Nova Skye | AltStation.io | Updated October 18, 2026
Company Overview
Headquartered in Atlanta, Georgia, Global Payments Inc. operates in the Industrials sector under Specialty Business Services, handling the back-end plumbing for card, check, and digital transactions. Founded in 1967, the company sells payment processing, point-of-sale hardware, authorization, settlement, payroll, and billing software across the Americas, Europe, and the Asia-Pacific. Its buyers range from small local storefronts to large enterprise merchants and financial institutions looking for turnkey transaction security and dispute management. Distribution relies on a direct sales force alongside software partners, independent sales organizations, and financial institution referral networks.
Global Payments is an established market leader in payment infrastructure, but it is constantly defending turf against legacy peers like Fiserv and FIS, as well as agile fintechs like Block and Stripe. Its competitive edge lies in vertical software integration—bundling payroll, analytics, and point-of-sale tools directly into payment processing to keep customer churn low. The primary threat is that baseline payment processing is largely commoditized, putting steady pressure on processing fees. Scale keeps Global Payments deeply entrenched with institutional clients, but accelerating growth against tech-first disruptors remains an ongoing challenge.
Global Payments is currently a mature, cash-generative business growing at a modest single-digit pace. The company delivered $3.16 billion in adjusted net revenue in the second quarter of 2026 and projects full-year normalized constant-currency revenue growth between 4% and 5%. Management is actively pivoting toward a pure-play commerce model, prioritizing adoption of its Genius platform and operational cost discipline to boost margins. It is not an explosive growth stock, but it serves as a stable, high-volume transaction utility as long as software cross-selling stays on track.
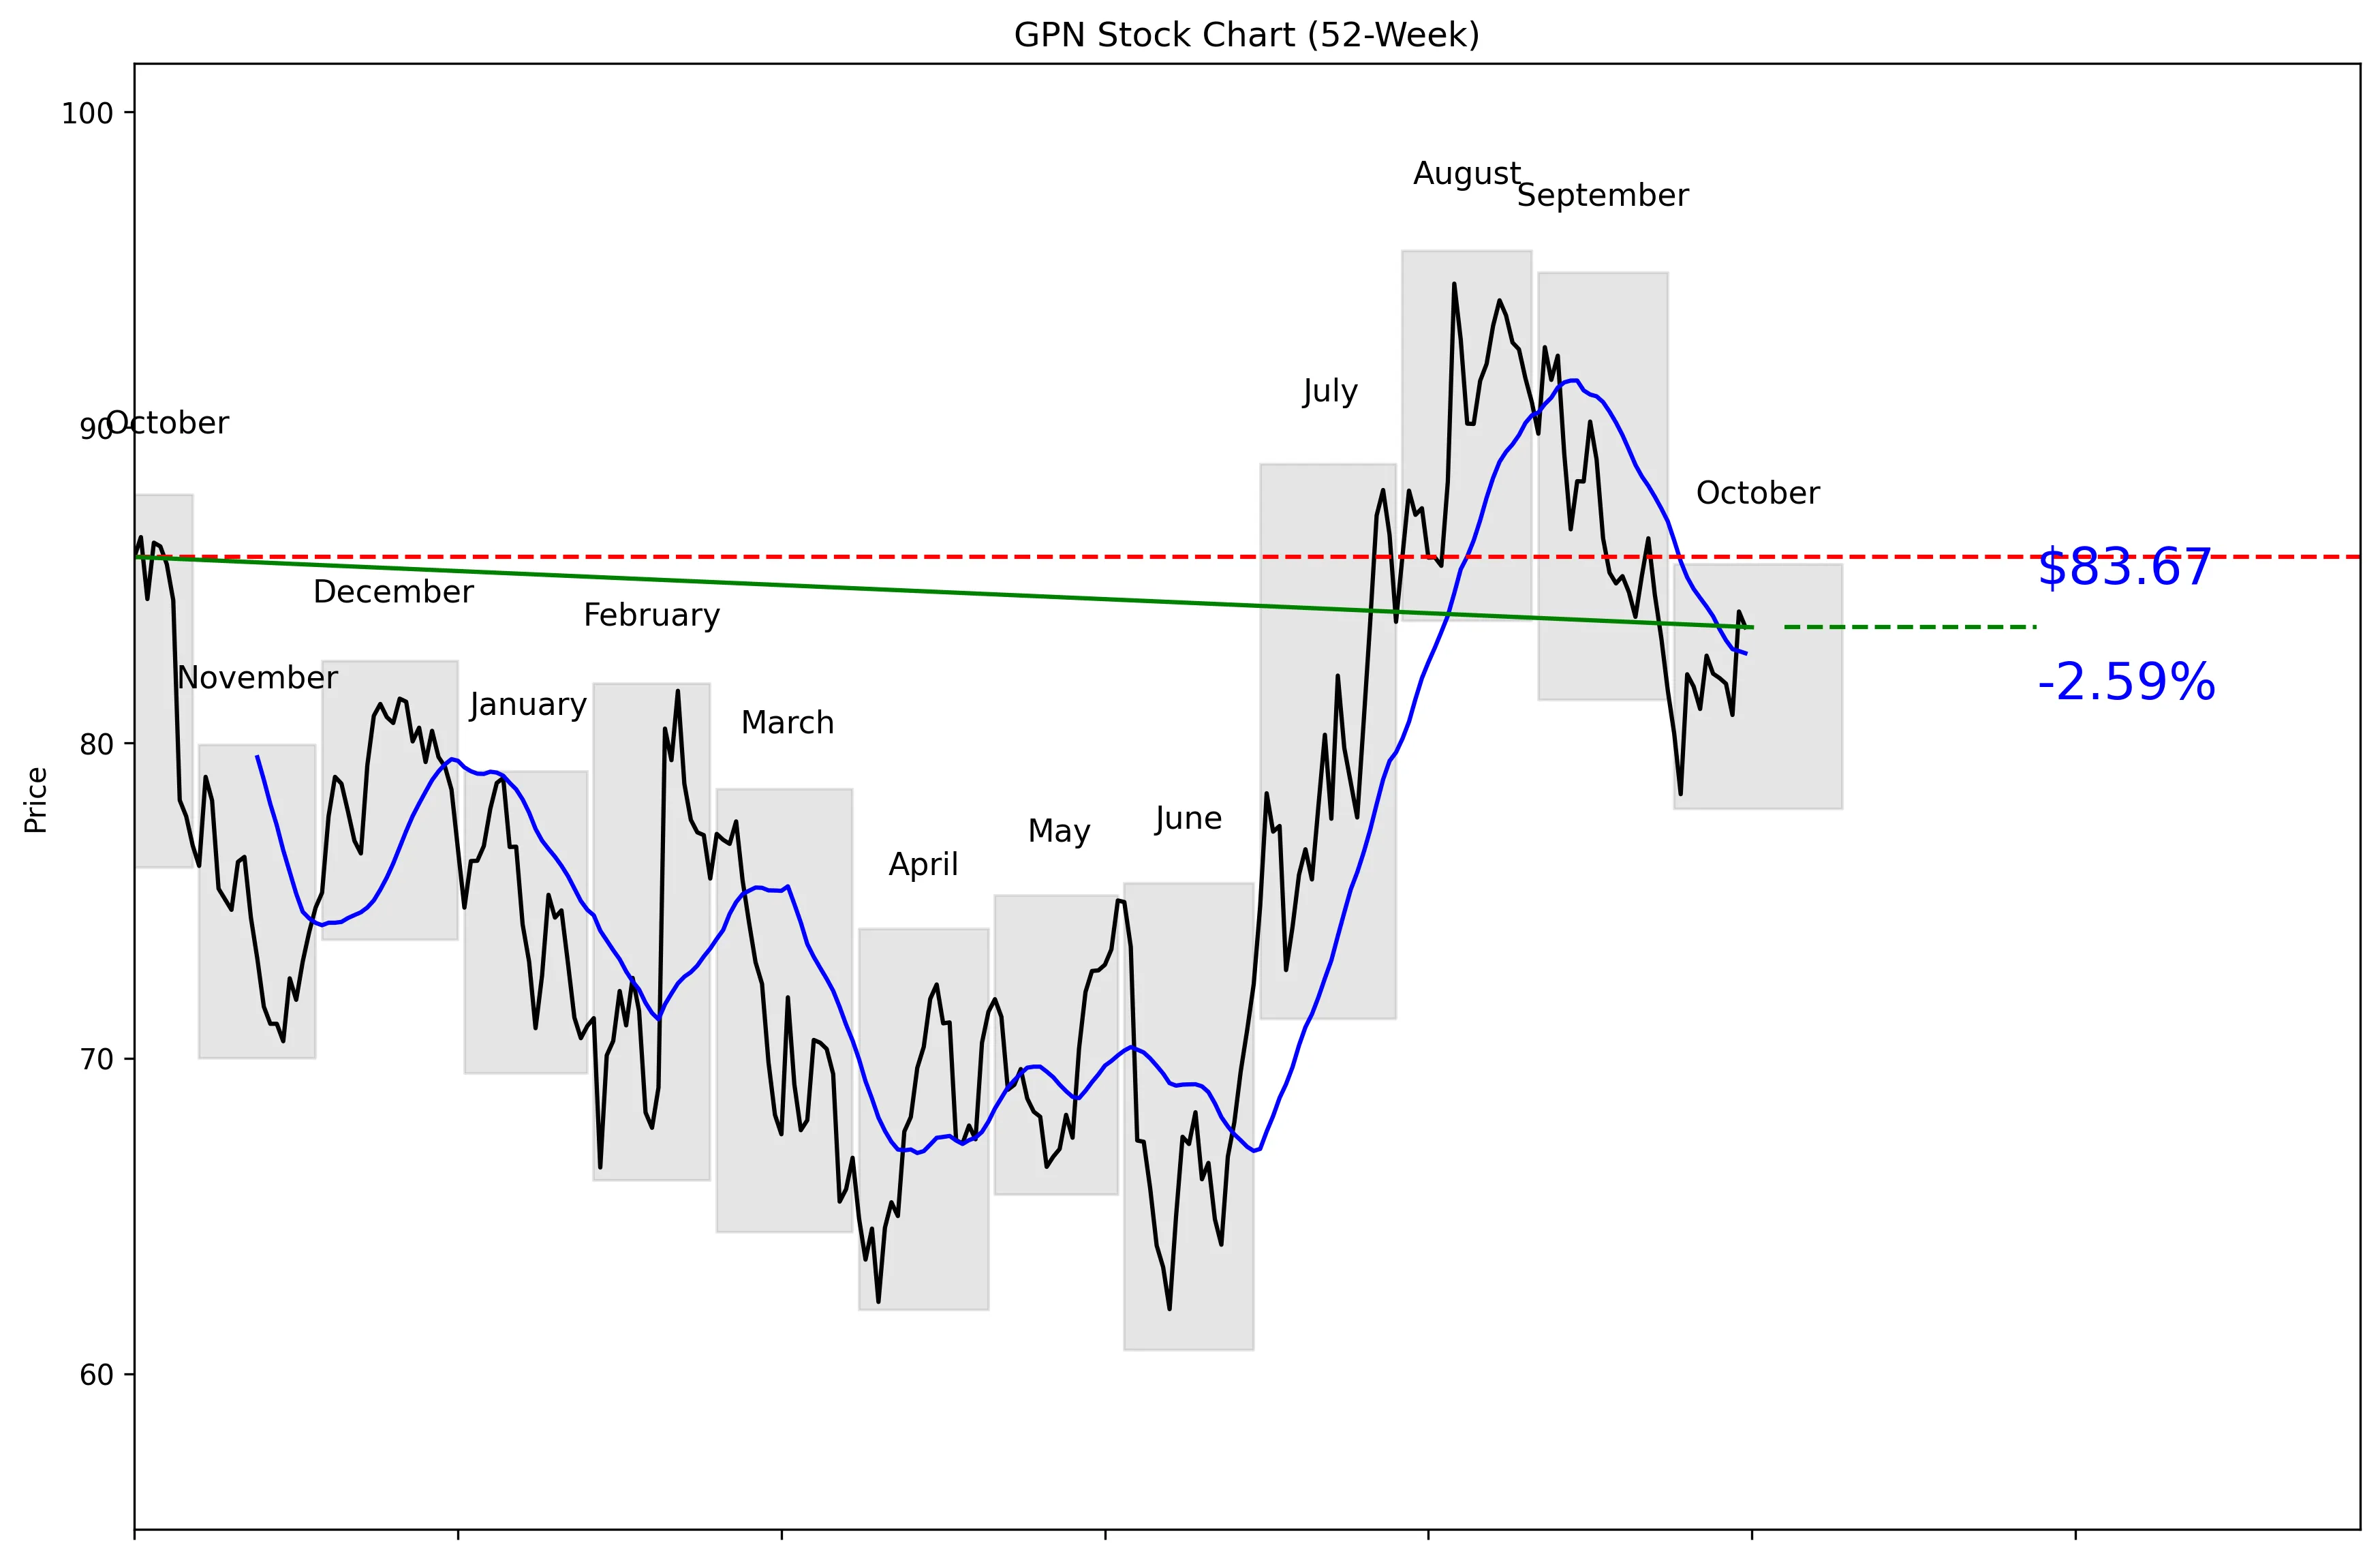
52-Week Price Performance Analysis
Recent News and Developments
Bank of America reinstated coverage of Global Payments with a Buy rating on October 15. The firm models about 85% of management’s roughly $600 million Worldpay synergy target and says GPN trades near 5 times forward earnings versus its historical average of roughly 8.5 times. Source: Yahoo Finance
Goldman Sachs maintained its Hold rating on October 13 and raised its price target from $94 to $98. That target represented 17.13% upside when the analyst data was updated. Source: StockAnalysis
Bernstein analyst Harshita Rawat reiterated a Hold rating on GPN on October 13. No price target was listed with the call. Source: StockAnalysis
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports