ALTSTATION.IO

L3Harris Technologies, Inc. (LHX) Stock Analysis

By Nova Skye | AltStation.io | Updated October 20, 2026

Price
$244.91
Change
-1.45%
Market Cap
$45.61B
Avg Volume
1.7M

Company Overview

L3Harris Technologies (LHX) is a major defense contractor in the Industrials sector, focused on Aerospace and Defense from its headquarters in Melbourne, Florida. The company builds mission-critical defense hardware across three operating units: Space and Mission Systems, Communications and Spectrum Dominance, and Missile Solutions. Their catalog includes tactical radios, night vision goggles, satellite payloads, and advanced missile propulsion systems. Buyers include the U.S. Department of Defense, federal and state agencies, and allied international governments.

L3Harris holds a formidable market position as a premier electronics and communications contractor rather than a traditional heavy platform builder. This focus on tactical electronics and proprietary waveforms gives them an edge over legacy primes like Lockheed Martin, Northrop Grumman, and RTX, which face heavier capital requirements. However, intense competition for high-value space payloads and hypersonic propulsion contracts keeps margins under constant pressure. Their biggest operating risk remains revenue concentration with government clients, making top-line performance dependent on defense appropriations and procurement timelines.

Founded in 1895 and renamed in June 2019 following its mega-merger, the company has generated over 21 billion dollars in annual revenue across its business lines. The company is actively executing a strategic pivot, reorganizing into three targeted operating segments in 2026 to cut complexity and focus on hypersonics, space defense, and secure communications. This operational consolidation directly targets high-priority modernization budgets within the Pentagon and global defense programs. LHX is intentionally repositioning its portfolio toward rapid, high-margin electronics and missile technologies instead of sprawling low-margin services.

Key Financials
Market Cap
$45.61B
Revenue
$22.93B
EBITDA
$4.14B
Gross Margin
25.5%
Profit Margin
8.2%
Revenue Growth
8.4%
Total Cash
$1.52B
Total Debt
$11.00B
Free Cash Flow
$1.61B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
24.69
Forward P/E
18.11
Beta
0.51
52-Week High
$379.23
52-Week Low
$232.34
EPS
$9.92
50-Day Avg
$254.89
200-Day Avg
$307.96
Price/Book
2.29
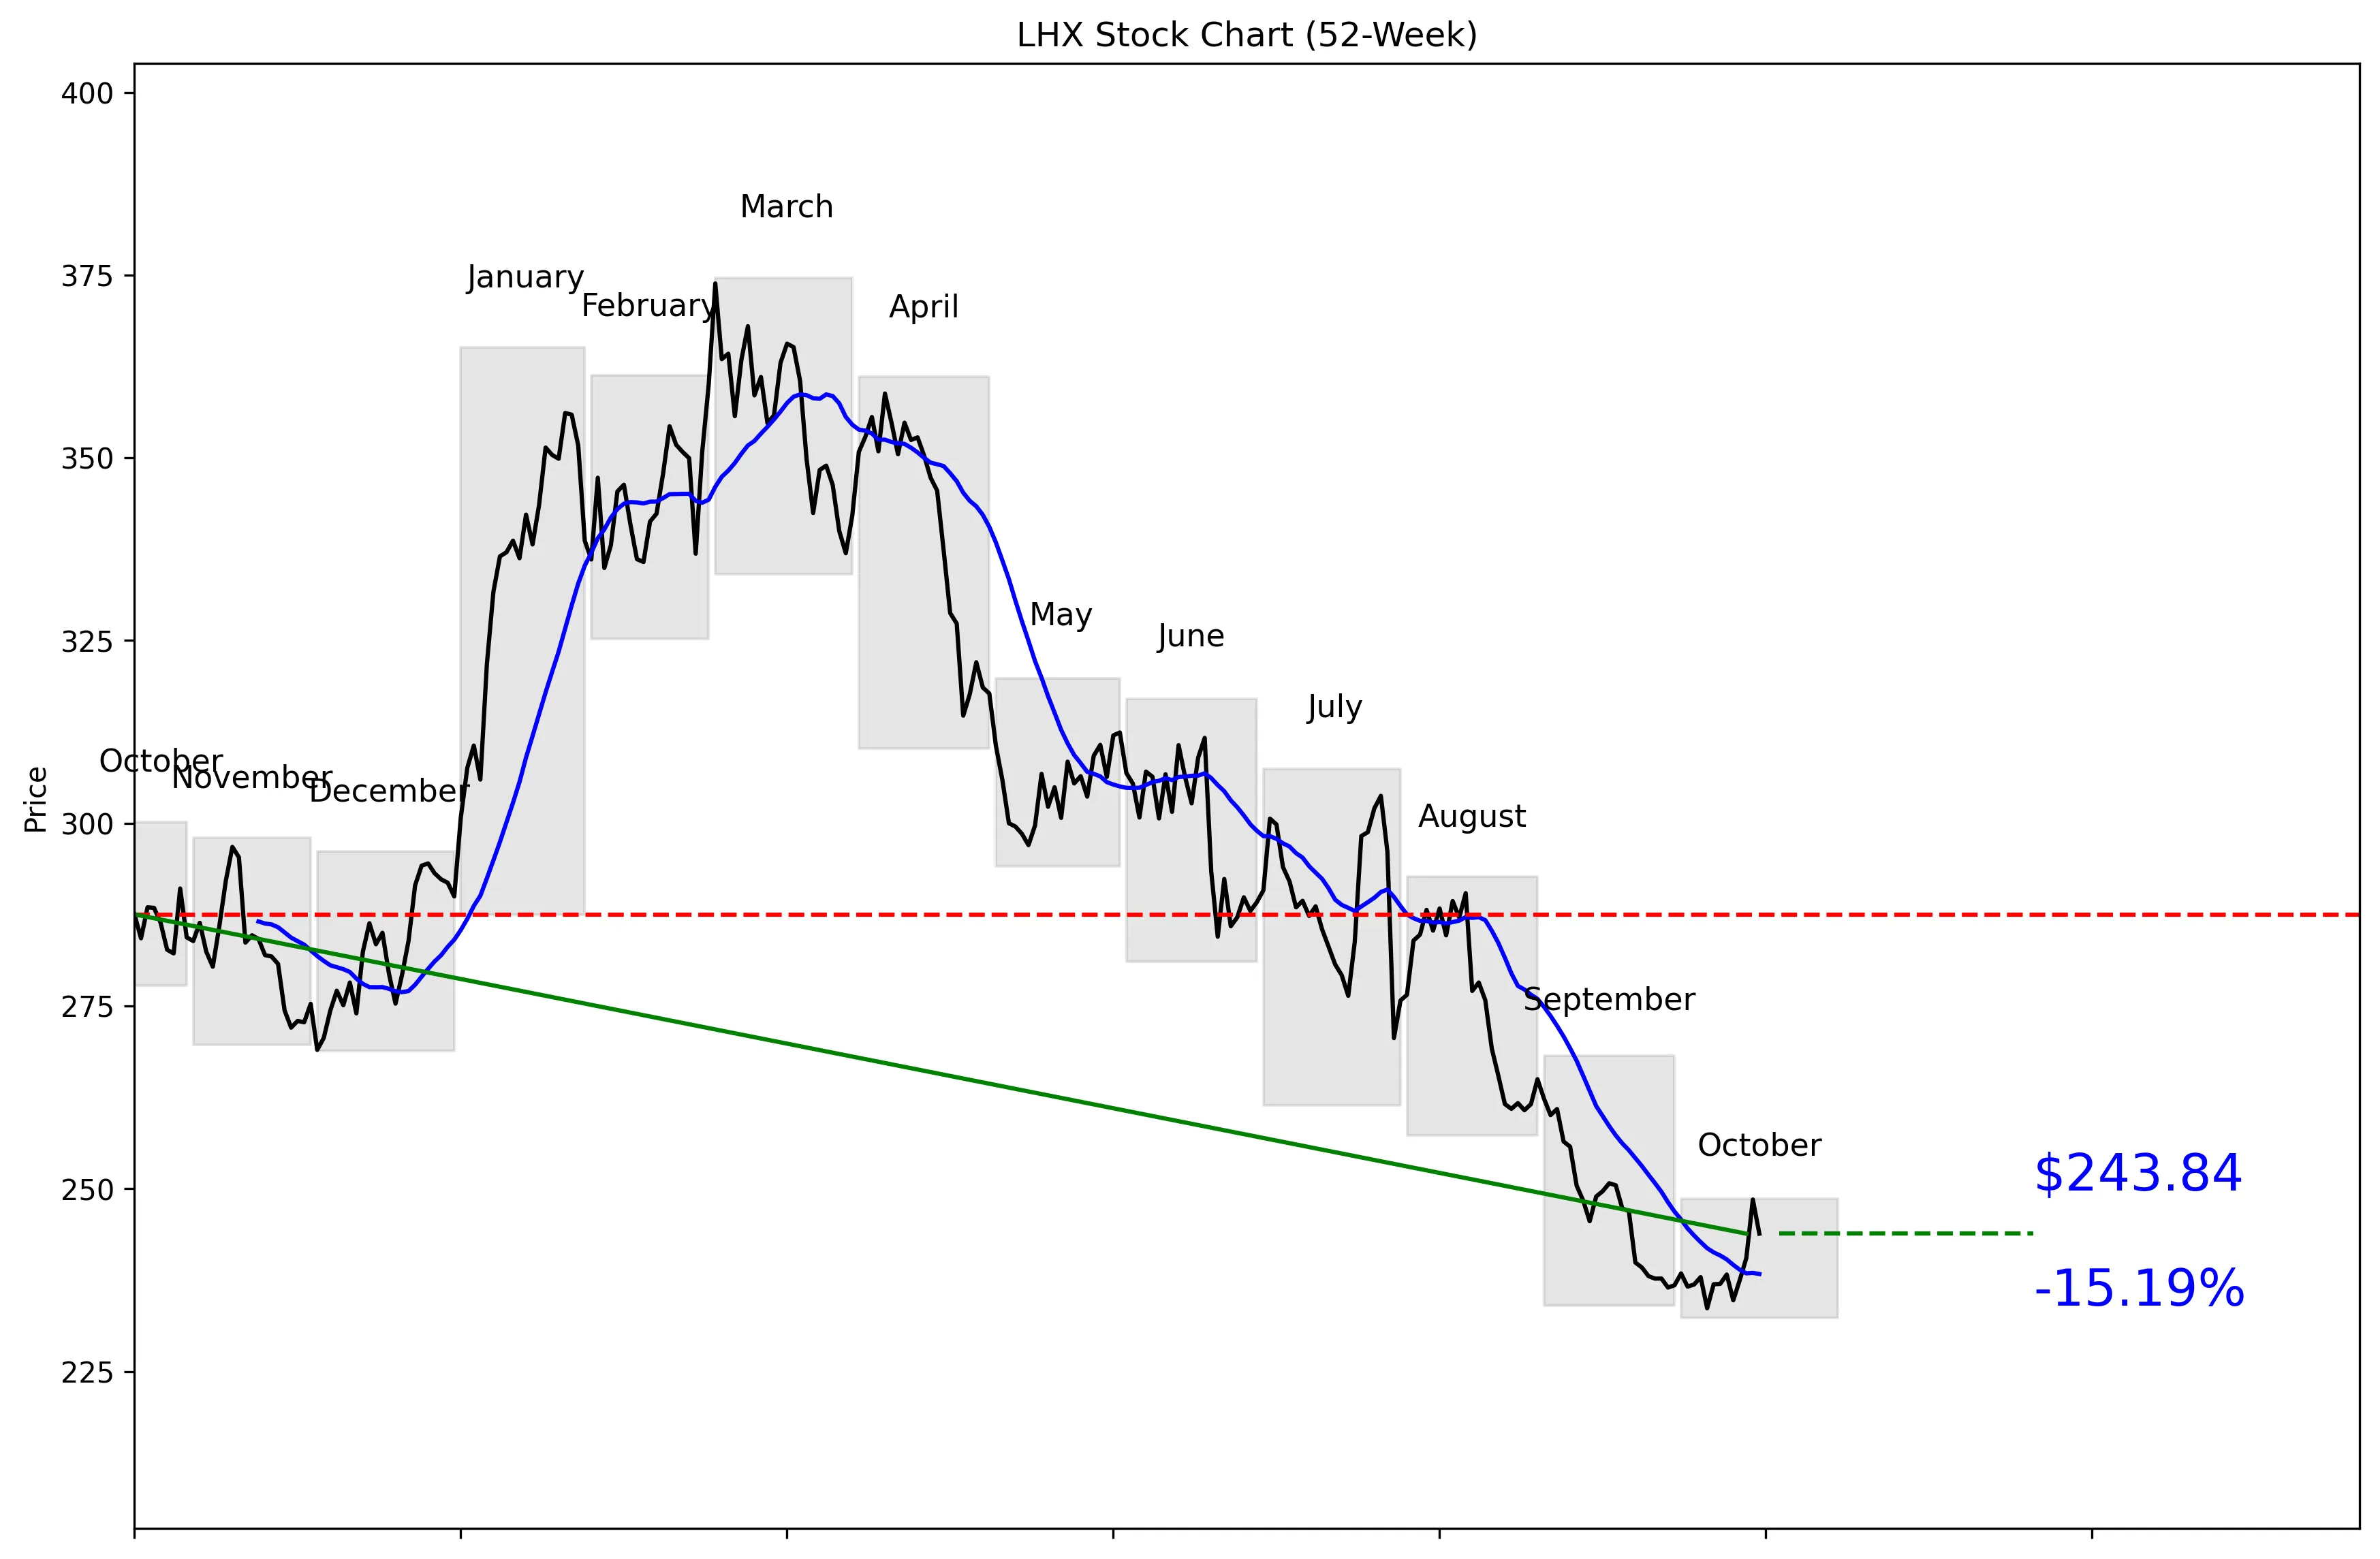
LHX 52-Week Stock Chart
Technical Analysis
LHX trades at $244.91, just 8% of the way from its technical 52-week low of $232.34 to its high of $374.59. The stock is 34.91% below that high and only 4.95% above the low, so the broader trend remains weak. Price is 2.32% above the 20-day moving average of $238.32, while five-day momentum has improved to 2.35%. The 20-day return is still negative at 1.25%, showing that the recovery has not established a sustained trend. Near-term support is $233.63, and resistance is $255.74.


Recent News and Developments

L3Harris wins $876.4 million Navy jammer award

L3Harris received an $876,440,942 U.S. Navy contract modification for the next engineering and manufacturing phase of the Next Generation Jammer Low Band program. The work covers demonstration pods, tooling, cybersecurity development, testing, logistics and software support. Source: L3Harris Technologies

L3Harris passes 1,000 shipsets for two F-35 components

L3Harris has delivered more than 1,000 shipsets of both the Panoramic Cockpit Display Electronic Unit and Aircraft Memory System for the F-35 Tech Refresh 3 program. The components provide 37 times the processing capability and 20 times the data storage of the legacy systems. Source: L3Harris Technologies

L3Harris and Skydio integrate anti-jam drone communications

L3Harris integrated its Falcon IV radios and Wraith waveform with Skydio’s X10D drone to provide layered anti-jam protection and electronic-warfare capability. More than 150,000 tactical radios in U.S. and allied inventories can host the Wraith waveform. Source: L3Harris Technologies


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is $22.93 billion and growing 8.4%, giving L3Harris a solid operating base. The $876,440,942 Navy contract modification adds meaningful work across engineering, manufacturing, cybersecurity, testing, logistics and software support. L3Harris has also delivered more than 1,000 shipsets of two F-35 components that provide 37 times the processing capability and 20 times the data storage of the legacy systems. Its anti-jam communications partnership with Skydio can build on more than 150,000 compatible tactical radios already in U.S. and allied inventories. Seventeen analysts rate the stock a buy, with a consensus target of $316.65 versus the current $244.91 price. With the stock 34.91% below its technical 52-week high, the bull case is straightforward: improving execution could close part of the gap between the current price and analyst expectations.
Bear Case
LHX carries $11.00 billion of debt against only $1.52 billion of cash, creating a clear balance-sheet risk. The stock trades at 24.69 times earnings, which is not a cheap valuation if revenue growth slows from 8.4%. Price is still 34.91% below the technical 52-week high and only 4.95% above the low, confirming that investors have sharply reduced what they will pay for the shares. Twenty-day momentum is negative at 1.25%, despite the stock sitting 2.32% above its 20-day moving average. RBC cut its target from $310 to $265 and kept a Sector Perform rating, while Bernstein lowered its target from $346 to $318. The wide analyst target range of $241 to $393 shows substantial disagreement about fair value. A break below $233.63 would put the stock back near its $232.34 technical 52-week low.
What to Watch
The first technical test is whether LHX can hold above its $238.32 20-day moving average. A move through $255.74 would clear the 30-day high and strengthen the near-term recovery, while a drop below $233.63 would weaken it. Investors should track progress on the $876,440,942 Navy jammer award, particularly the engineering, manufacturing, testing, cybersecurity and software work. Execution on the F-35 Tech Refresh 3 program also matters after deliveries passed 1,000 shipsets for both listed components. Watch whether the Skydio integration gains adoption across the installed base of more than 150,000 compatible tactical radios. Financially, the key questions are whether revenue growth can remain near 8.4% and whether the gap between $11.00 billion of debt and $1.52 billion of cash improves. Analyst revisions also matter because recent targets moved lower even though the overall recommendation remains buy.
Analyst Consensus
BUY

Based on 17 analyst opinions
Low Target
$241.00
Mean Target
$316.65
High Target
$393.00


Earnings and Financial Data

Sector
Industrials
Industry
Aerospace & Defense
Employees
45,000
Earnings & Dividends
Next Earnings
Oct 29, 2026
EPS (Trailing)
$9.92
Dividend Yield
201.0%
Payout Ratio
49.4%

Frequently Asked Questions

Is LHX a good stock to buy?
Seventeen analysts give LHX a buy recommendation, and their consensus target is $316.65 compared with a current price of $244.91. The takeaway is that analysts see upside, but the stock’s weak 52-week position still signals risk.
What is the analyst price target for LHX?
The consensus analyst target is $316.65, with estimates ranging from $241 to $393. The takeaway is that the average target is above the current price, but analyst expectations vary widely.
Is LHX stock near its 52-week low?
LHX is priced at $244.91, only 4.95% above its technical 52-week low of $232.34 and 34.91% below its technical high of $374.59. The takeaway is that the stock is trading near the bottom of its annual range.
What are the support and resistance levels for LHX?
Near-term support is the 30-day low of $233.63, while resistance is the 30-day high of $255.74. The takeaway is that these are the key levels to watch for the next directional move.
Is LHX overvalued?
LHX trades at a P/E ratio of 24.69 while revenue is growing 8.4%. The takeaway is that the valuation requires continued growth and is not obviously cheap based on the supplied figures.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 20, 2026.