Allegion plc (ALLE) Stock Analysis
By Nova Skye | AltStation.io | Updated October 24, 2026
Company Overview
Allegion plc is a Dublin, Ireland-based security hardware and access control manufacturer operating in the Industrials sector’s Security & Protection Services group. The company runs two reporting segments, Allegion Americas and Allegion International, selling mechanical locks, exit devices, door closers, and electronic access systems. Its core product lineup spans recognized commercial and residential brands like Schlage, Von Duprin, LCN, and CISA, serving educational facilities, healthcare centers, government buildings, commercial offices, and residential properties. Sales flow through DIY home improvement stores, specialty distributors, wholesalers, and e-commerce channels, supplemented by maintenance repair services and cloud access software.
Allegion holds a market-leading position in North American institutional security hardware, operating as a focused pure-play competitor against larger global rivals like ASSA ABLOY. The company’s primary moat lies in high switching costs and entrenched brand specifications, where architects and facility managers routinely write brands like Von Duprin and LCN directly into commercial building codes. The main operational threat is low-end mechanical lock commoditization and cyclical exposure to new commercial construction activity. However, Allegion insulates itself through recurring aftermarket replacement demand, where property managers prioritize proven reliability over unproven budget alternatives.
The business is growing steadily while executing a strategic shift from legacy mechanical locks toward digital, connected access platforms. Allegion generated $3.77 billion in net revenues for 2024, marking a 3.3% reported increase and 2.1% organic growth over 2023’s $3.65 billion top line. Electronic security products and digital solutions now account for roughly 33% of the company’s total revenue mix. That electronic migration is the central investment thesis, allowing Allegion to capture higher gross margins and attach recurring software-as-a-service workflows to its physical footprint.
52-Week Price Performance Analysis
Recent News and Developments
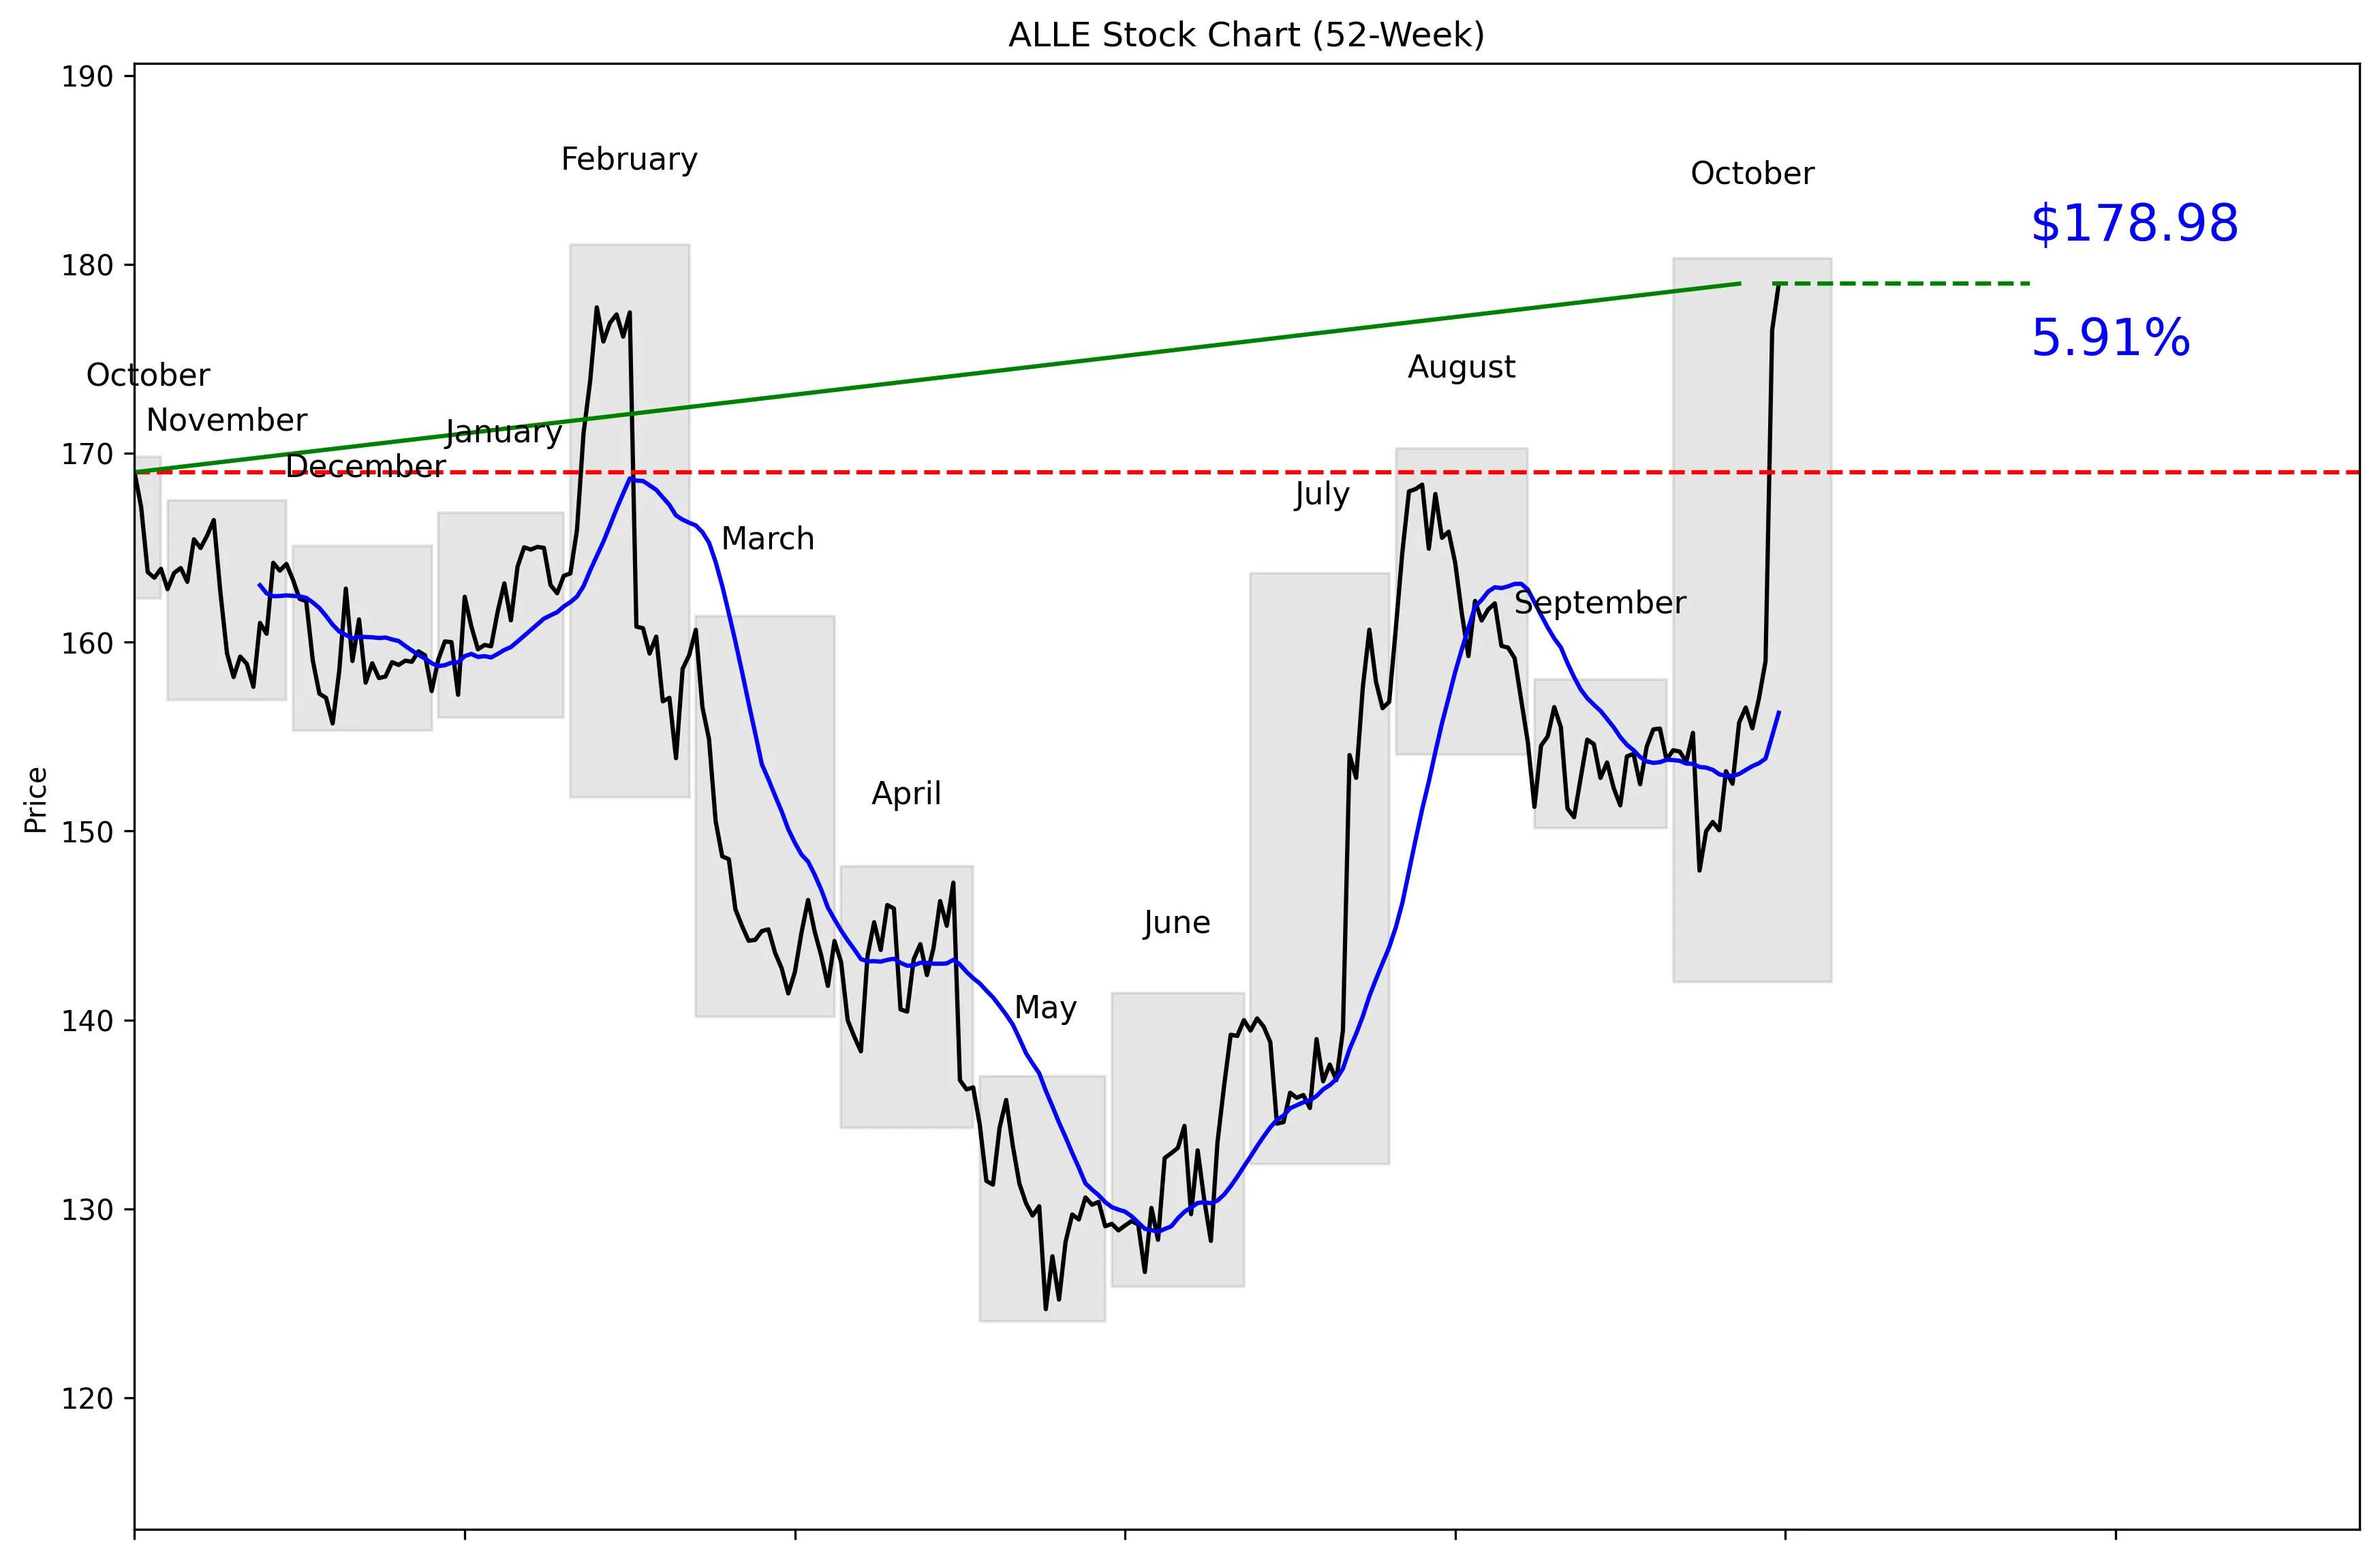
Third-quarter revenue rose 9.6% to $1.1726 billion, while adjusted EPS increased 13.0% to $2.60. Allegion raised its full-year adjusted EPS forecast to $9.05-$9.10, backed by 9.1% organic growth in the Americas. Source: Allegion
Allegion shares jumped 6.9% during the morning session on October 22 after its quarterly report. Adjusted EPS of $2.60 beat the $2.50 Wall Street estimate, while revenue of $1.173 billion topped the $1.137 billion estimate. Source: Yahoo Finance
BofA upgraded Allegion from Neutral to Buy and raised its price target from $164 to $200, citing accelerating organic growth and improving volume trends. JPMorgan lifted its target from $170 to $183 while keeping a Neutral rating, and Evercore ISI raised its target from $180 to $190 while maintaining Outperform. Source: Benzinga
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports