ALTSTATION.IO

Howmet Aerospace Inc. (HWM) Stock Analysis

By Nova Skye | AltStation.io | Updated September 19, 2026

Price
$228.68
Change
-1.70%
Market Cap
$91.20B
Avg Volume
3.0M

Company Overview

Howmet Aerospace operates out of Pittsburgh, Pennsylvania, in the Industrials sector under the Aerospace and Defense industry. The company manufactures mission-critical hardware across four divisions: Engine Products, Fastening Systems, Engineered Structures, and Forged Wheels. Their primary buyers are commercial jet manufacturers, defense contractors, and heavy-duty truck builders across the United States, Europe, and Asia. They supply high-spec components ranging from titanium airfoils and aero-engine structural parts to forged aluminum truck wheels. It is a specialized industrial powerhouse producing parts that modern jet turbines and commercial fleets cannot fly or roll without.

Howmet is a clear market leader with formidable pricing power because aerospace casting and precision machining have massive technical barriers to entry. Commercial aerospace generates roughly 53% of their business, while defense programs contribute another 15%, giving the company dependable revenue streams. In the industrial gas turbine space, Howmet commands more than a 50% global market share in turbine blades. Their primary headwind is not competitive disruption, but navigating input costs and cyclical downturns in their Forged Wheels commercial trucking business.

The business is in a clear growth phase, delivering $8.3 billion in revenue for 2025, an 11% increase over 2024. Engine Products is their primary margin driver thanks to surging global demand for engine spare parts, while the Fastening Systems segment grew 11% to reach $1.7 billion in 2025. Management accelerated this momentum by executing a $1.8 billion acquisition of aerospace fastener manufacturer CAM and lifting full-year 2026 revenue guidance to approximately $10.05 billion. Howmet is capturing direct upside from the massive multi-year aircraft manufacturing backlog, making it one of the most reliable industrial plays on the board.

Key Financials
Market Cap
$91.20B
Revenue
$9.12B
EBITDA
$2.79B
Gross Margin
36.0%
Profit Margin
20.5%
Revenue Growth
24.1%
Total Cash
$563.00M
Total Debt
$4.66B
Free Cash Flow
$1.19B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
49.39
Forward P/E
35.63
Beta
1.19
52-Week High
$310.00
52-Week Low
$181.36
EPS
$4.63
50-Day Avg
$273.88
200-Day Avg
$245.84
Price/Book
15.96
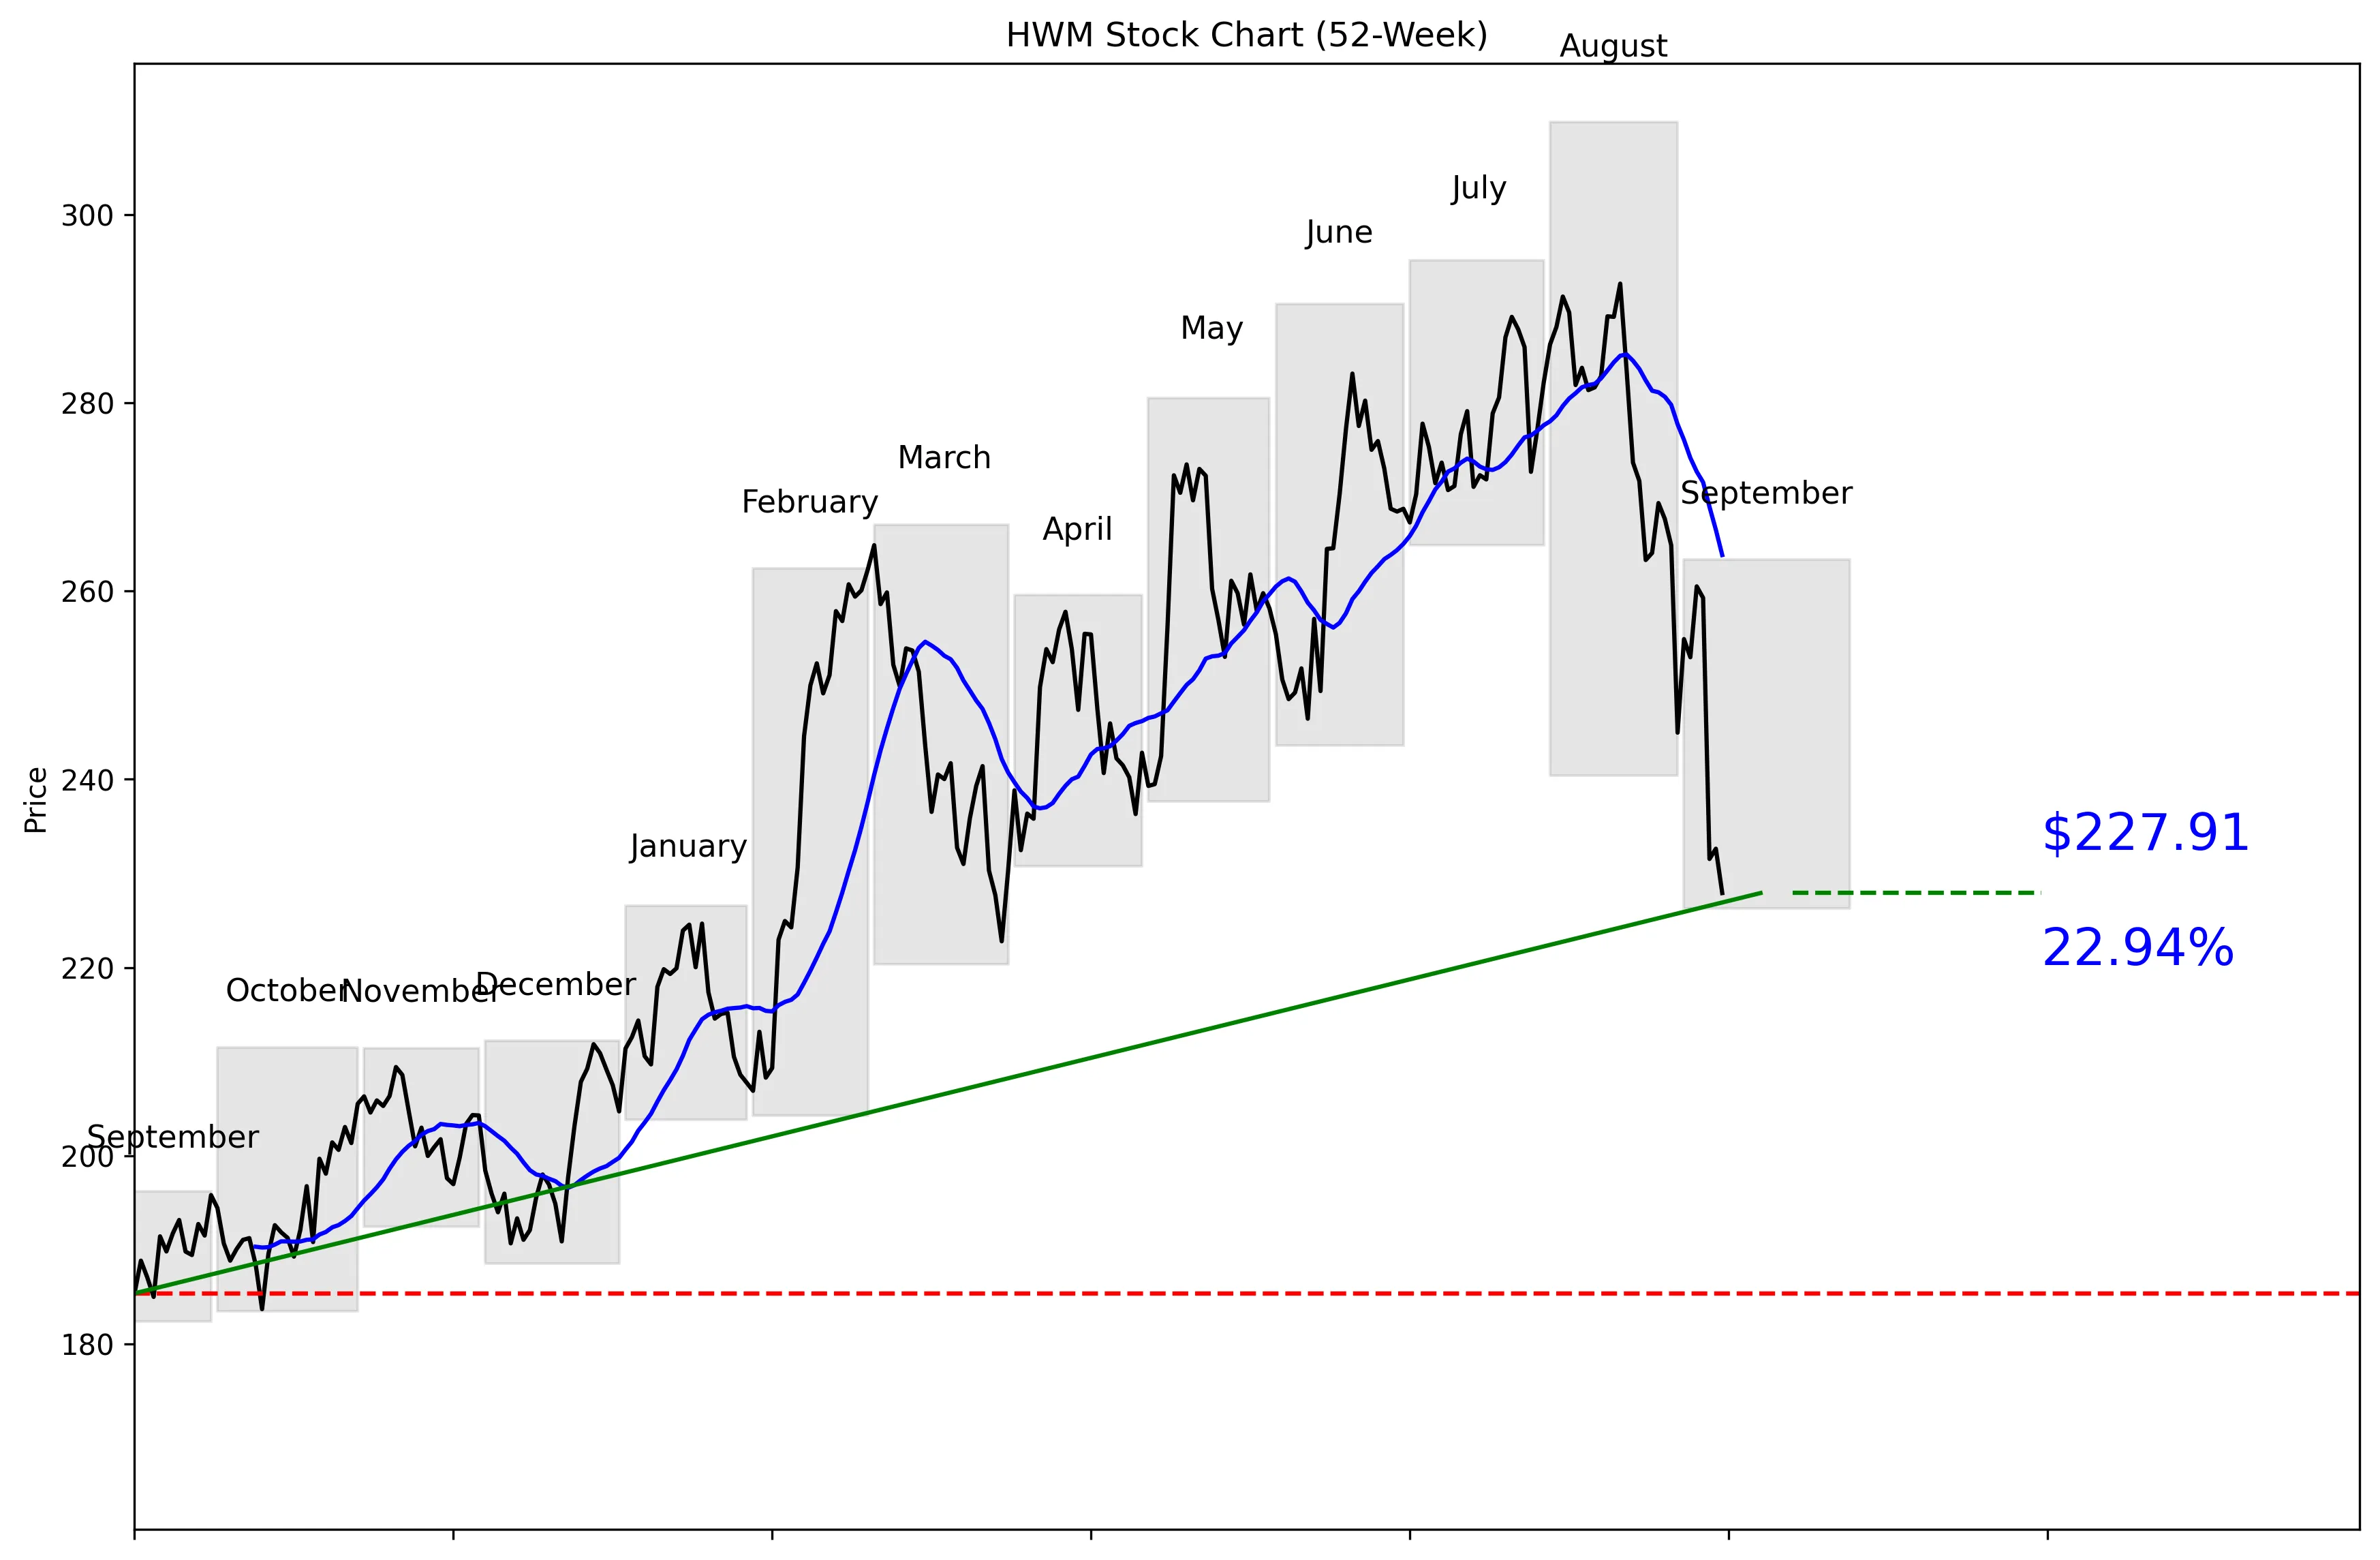
HWM 52-Week Stock Chart
Technical Analysis
HWM trades at $228.68, placing it 36% of the way from its 52-week low of $182.40 to its high of $309.85. The stock is 26.45% below that high but remains 24.95% above the low. Momentum is sharply negative, with declines of 9.90% over five trading days and 19.07% over 20 trading days. The price sits 13.61% below its 20-day moving average of $263.82, confirming that sellers control the near-term trend. Immediate support is $227.91, while the 30-day high of $292.65 is the key resistance level.


Recent News and Developments

GE rival deal sends Howmet shares down 10%

Howmet closed down 10% on September 8 after GE Aerospace agreed to acquire rival casting supplier Consolidated Precision Products for $11.75 billion. Investors treated GE’s vertical integration as a direct threat to Howmet’s engine-parts business. Source: Reuters

Howmet CEO dismisses threat from GE acquisition

CEO John Plant said Howmet should be “fine” with GE’s CPP deal and remains confident in the company’s position. He said customer demand and the scale of Howmet’s capital expansion are testing the business, with an update to long-term revenue goals planned within the next few earnings calls. Source: Reuters

Howmet favors capacity spending over major acquisitions

Plant said organic capacity investment remains Howmet’s preferred use of capital while the company continues buybacks, dividend increases and selective acquisitions. Howmet’s leverage stood at 1.2 times after the CAM acquisition, and Plant said he does not anticipate any very significant deals. Source: Stock Analysis


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is $9.12 billion and growing 24.1%, giving Howmet a strong fundamental growth rate despite the stock’s recent decline. The analyst consensus is strong buy across 20 analysts. Their average target is $337.13, which is 47.42% above the current price of $228.68. Even the low target of $256.56 sits above the current price, while the high estimate reaches $375.00. CEO John Plant remains confident in Howmet’s competitive position following GE Aerospace’s agreement to acquire Consolidated Precision Products. Management is prioritizing organic capacity investment while continuing buybacks, dividend increases and selective acquisitions. The bull case is straightforward: strong revenue growth, broad analyst support and a major valuation gap between the current price and consensus target.
Bear Case
A P/E ratio of 49.39 leaves little room for weak execution or slower growth. Total debt of $4.66 billion is more than eight times the company’s $563 million cash balance. GE Aerospace’s $11.75 billion acquisition of Consolidated Precision Products creates a credible competitive threat through vertical integration. Investors took that threat seriously, pushing HWM down 10% on September 8. The attempted rebound was weak: HWM gained 0.47% on September 9, then fell another 2.02% on September 10 to $227.91. The stock’s 19.07% decline over 20 trading days and position 13.61% below its moving average show that sentiment has broken down. Howmet must manage its capacity expansion while meeting customer demand, and a stumble would be punished at this valuation.
What to Watch
The first test is whether HWM can hold near-term support at $227.91 during the next quarter. A recovery above the 20-day moving average of $263.82 would signal that selling pressure is easing. The larger technical hurdle is $292.65, the 30-day resistance level. Investors should watch the next few earnings calls for management’s planned update to long-term revenue goals. Revenue growth needs to remain strong relative to the current 24.1% rate to support a P/E of 49.39. Any evidence that GE Aerospace’s CPP acquisition is pressuring Howmet’s engine-parts position would weaken the thesis, while stable demand and successful capacity expansion would strengthen it. Capital allocation also matters because Howmet has $4.66 billion of debt against $563 million in cash while funding expansion, buybacks, dividend increases and selective acquisitions.
Analyst Consensus
STRONG BUY

Based on 20 analyst opinions
Low Target
$256.56
Mean Target
$337.13
High Target
$375.00


Earnings and Financial Data

Sector
Industrials
Industry
Aerospace & Defense
Employees
25,430
Earnings & Dividends
Next Earnings
Nov 05, 2026
EPS (Trailing)
$4.63
Dividend Yield
24.0%
Payout Ratio
10.3%

Frequently Asked Questions

Is HWM a good stock to buy?
HWM has 24.1% revenue growth and a strong buy recommendation from 20 analysts. However, its P/E is 49.39 and short-term momentum is negative, so the takeaway is that the growth case is strong but the entry remains technically risky.
What is HWM’s price target?
The average analyst target is $337.13, with estimates ranging from $256.56 to $375.00. Against the current price of $228.68, the takeaway is that every listed analyst target implies upside.
Is HWM stock overvalued?
HWM trades at a P/E of 49.39 while revenue is growing 24.1%. The takeaway is that investors are paying a high multiple for growth, leaving limited room for disappointment.
What are HWM’s support and resistance levels?
Near-term support is the 30-day low of $227.91, and near-term resistance is the 30-day high of $292.65. The takeaway is that HWM is currently trading almost directly on support.
How far is HWM below its 52-week high?
HWM is 26.45% below its 52-week high of $309.85 and 24.95% above its 52-week low of $182.40. The takeaway is that the stock remains well off its peak and sits only 36% of the way through its 52-week range.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated September 19, 2026.