ALTSTATION.IO

Gartner, Inc. (IT) Stock Analysis

By Nova Skye | AltStation.io | Updated October 24, 2026

Price
$230.61
Change
-1.63%
Market Cap
$14.56B
Avg Volume
1.2M

Company Overview

Gartner sells research, executive conferences, and hands-on consulting to corporate leaders making high-stakes technology decisions. Founded in 1979 and headquartered in Stamford, Connecticut, the company operates in the Information Technology Services industry within the broader Technology sector. Its business splits into three divisions: Insights subscription services, in-person industry conferences, and tailored consulting engagements focused on digital transformation and cost optimization. Enterprise buyers and senior executives worldwide pay recurring fees to access proprietary data, benchmarks, and direct analyst guidance to derisk multi-million-dollar software and infrastructure investments.

Gartner is the undisputed market leader in enterprise IT research, holding far more pricing power and executive reach than direct rivals like Forrester Research and IDC. Its primary moat is the subscription-driven Insights division, which generates high-margin recurring cash flow backed by sticky client retention. The consulting arm faces tough competition from heavyweight professional services firms like Accenture and Deloitte, but Gartner’s proprietary research gives it an immediate foot in the boardroom door. The biggest emerging threat to its business model is whether generative AI tools commoditize entry-level advisory reports, forcing Gartner to prove its human analysts remain worth premium prices.

The business remains fundamentally healthy and growing, pulling in 6.26 billion dollars in 2024 revenue, up roughly 6.1 percent over 2023’s 5.90 billion dollars. While top-line expansion has moderated from previous high-single-digit rates, Gartner continues to grind out steady gains by expanding into non-IT executive roles and riding a wave of demand for AI advisory work. Tightening enterprise budgets and scrutiny on consulting fees remain active headwinds, but the company’s subscription foundation protects its core profitability. It is not a hyper-growth tech play, but a disciplined, cash-generative machine that corporate decision-makers still treat as essential insurance.

Key Financials
Market Cap
$14.56B
Revenue
$6.46B
EBITDA
$1.38B
Gross Margin
69.6%
Profit Margin
12.0%
Revenue Growth
-0.6%
Total Cash
$1.49B
Total Debt
$3.33B
Free Cash Flow
$1.05B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
20.85
Forward P/E
14.07
Beta
0.98
52-Week High
$257.69
52-Week Low
$124.25
EPS
$11.06
50-Day Avg
$191.42
200-Day Avg
$169.79
Price/Book
-88.76
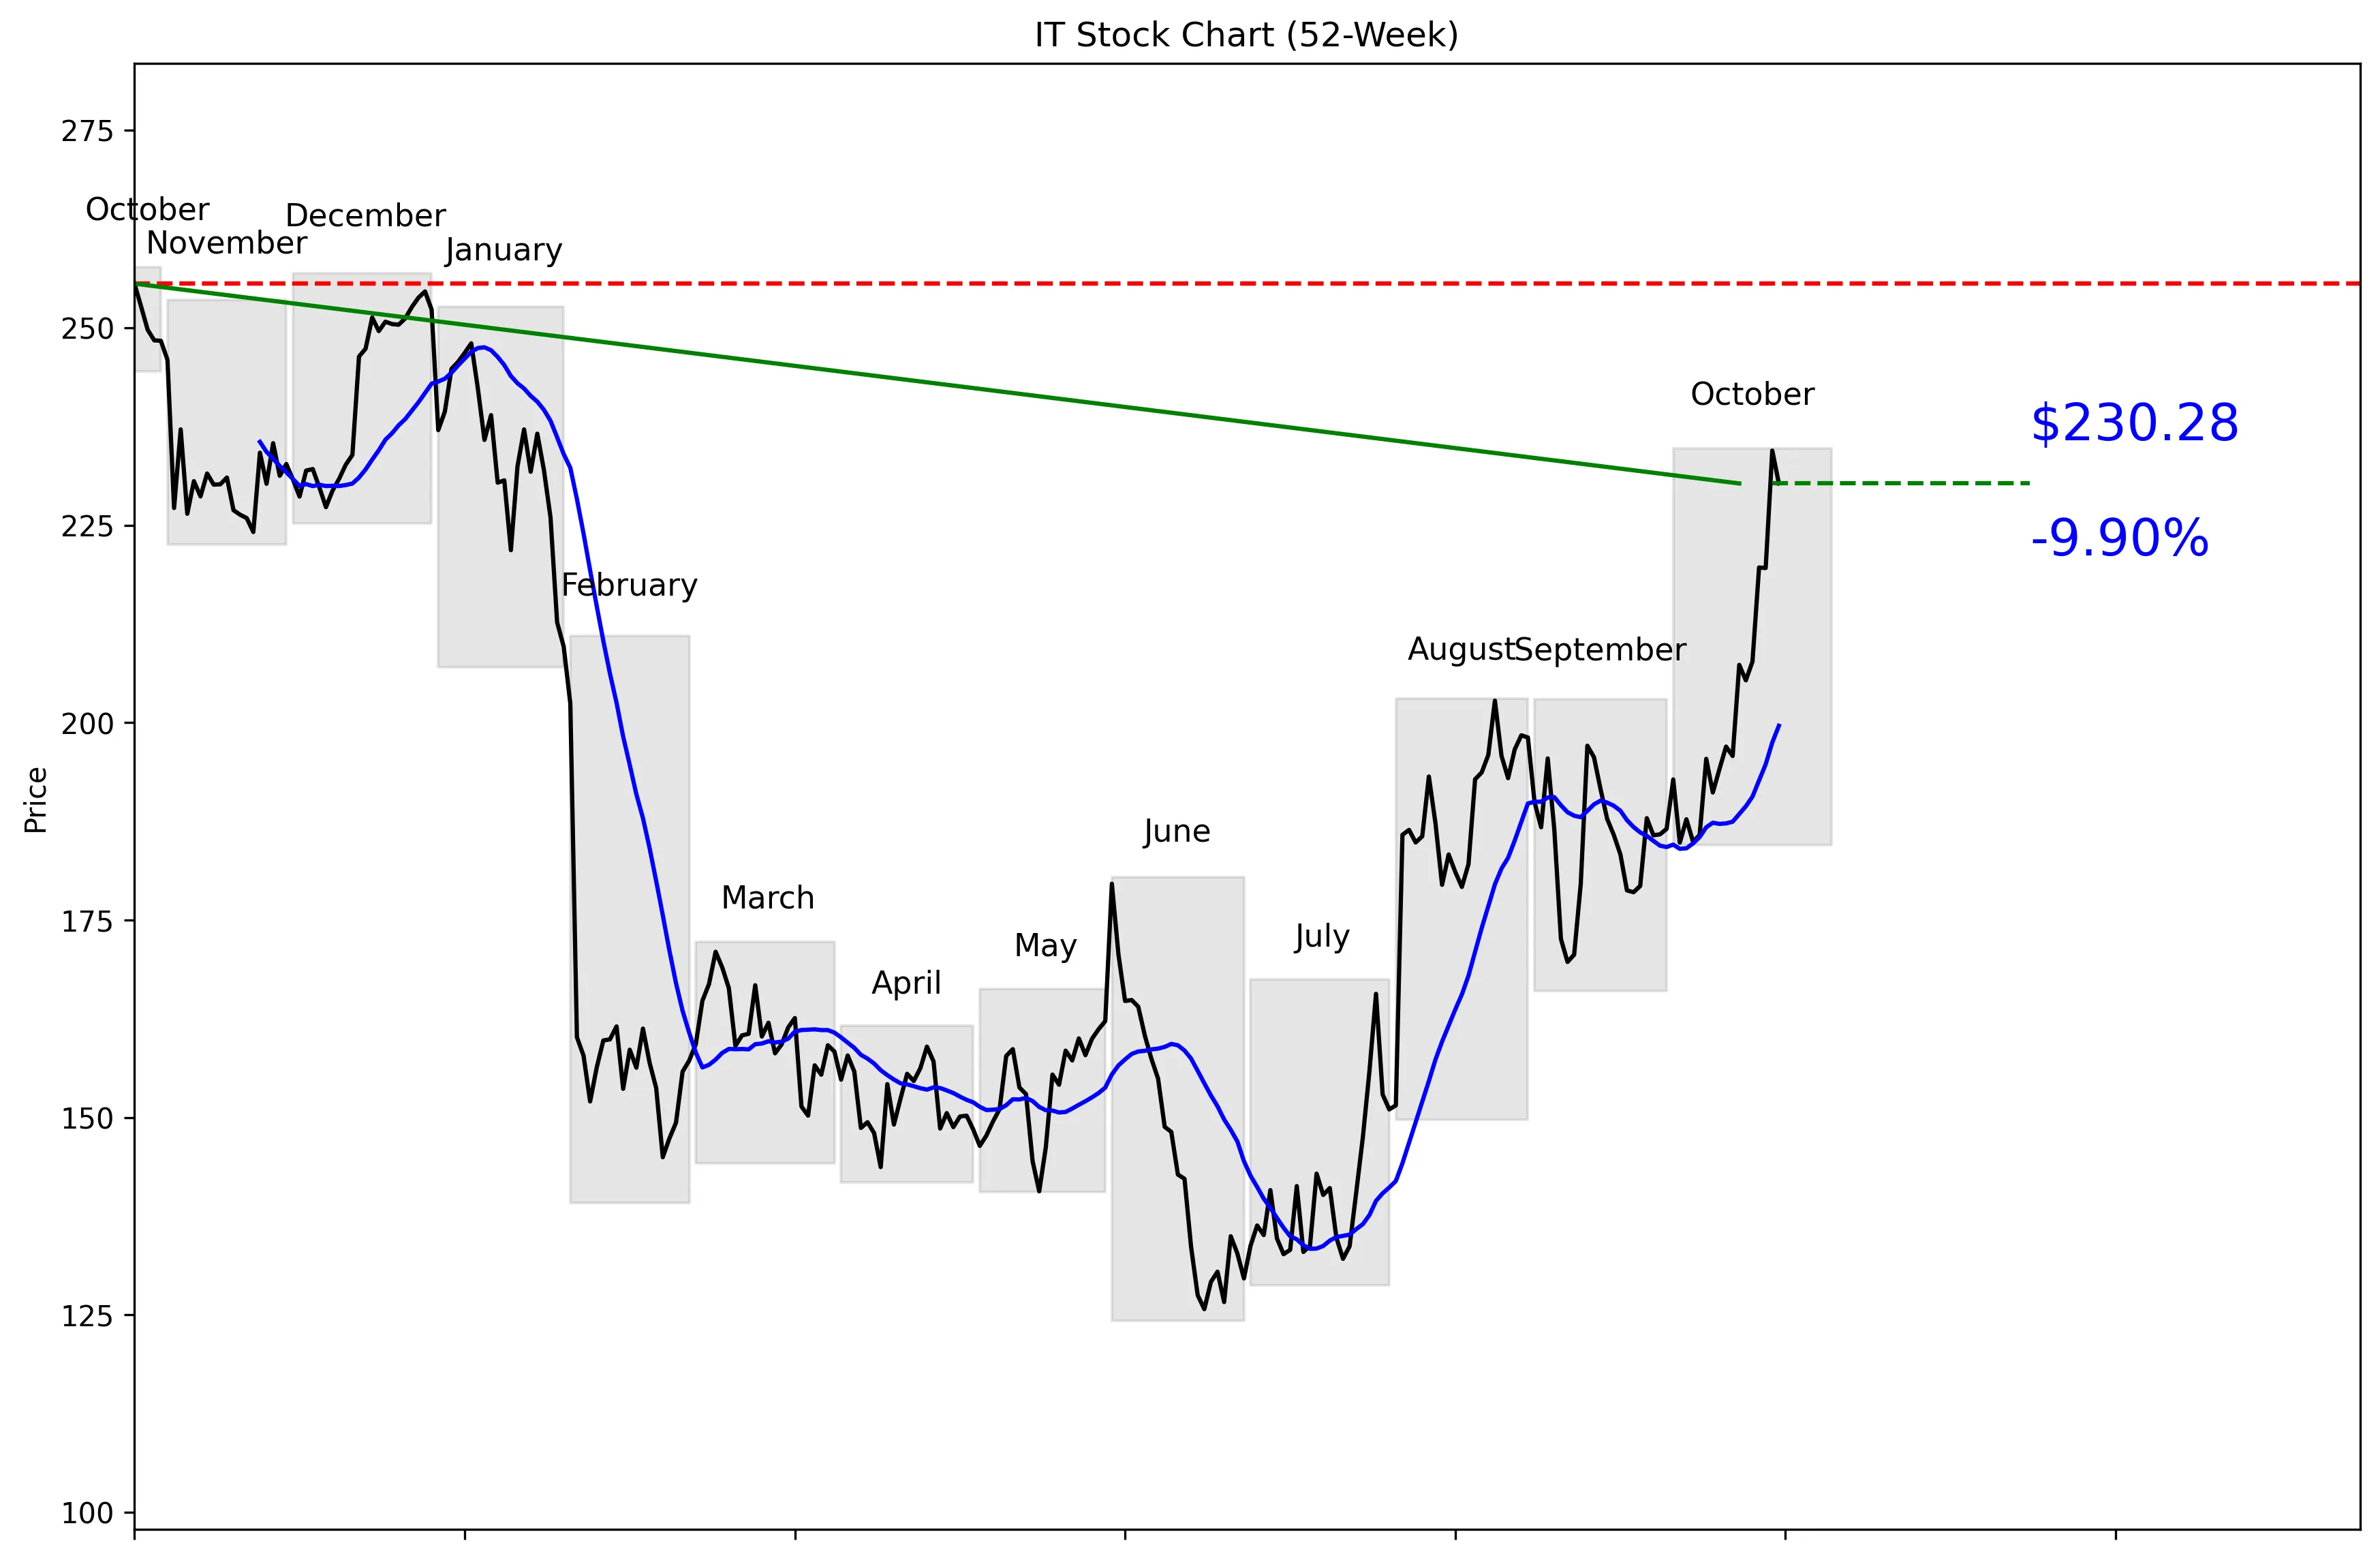
IT 52-Week Stock Chart
Technical Analysis
Gartner trades at $230.61, 79% of the way from its 52-week low of $124.25 to its $257.69 high. The stock is 10.64% below that high and 85.34% above the low. Price sits 15.37% above its 20-day moving average of $199.59, confirming strong short-term momentum. Shares gained 12.14% over the last five trading days and 22.55% over the last 20. Near-term support is $178.52, while resistance sits at $234.44.


Recent News and Developments

Gartner shares jump 4.8% after analyst target hikes

Gartner traded at $217.61 on October 20, up 4.8% from the previous close. The move followed price-target increases from Truist Securities and Wells Fargo after meetings around Gartner’s IT Symposium. Source: Yahoo Finance

Truist raises Gartner target to $235

Truist Securities raised its Gartner price target from $205 to $235 and maintained its Buy rating. The firm cited double-digit year-over-year growth in IT Symposium attendance and management’s confidence in long-term contract-value acceleration. Source: Investing.com

Wells Fargo raises target but stays bearish

Wells Fargo increased its Gartner price target from $150 to $175 while maintaining an Underweight rating. The firm expects Gartner’s Business and Technology Insights transformation, including AskGartner and faster “quick-takes” research, to improve client engagement. Source: Investing.com


Market Sentiment and Analyst Recommendations

Bull Case
Gartner has strong price momentum, with shares gaining 22.55% over the last 20 trading days. Truist raised its target from $205 to $235 after reporting double-digit year-over-year growth in IT Symposium attendance and management confidence in long-term contract-value acceleration. The $235 target also sits above Gartner’s current $230.61 price. Wells Fargo expects the Business and Technology Insights transformation, including AskGartner and faster quick-takes research, to improve client engagement. UBS expects third-quarter total contract-value growth could reach 2.5%, ahead of the Street’s 2.3% expectation. The reason to buy here is clear: momentum is strong, operational improvements are underway, and the November 3 earnings report could validate improving contract growth.
Bear Case
The biggest problem is valuation relative to expectations. Gartner trades at $230.61, while the average analyst target is only $193.77 and the analyst range starts at $150. Revenue growth is negative at 0.6%, which makes the 20.85 P/E harder to defend. Total debt of $3.33 billion is more than double the company’s $1.49 billion in cash. Wells Fargo remains Underweight despite raising its target from $150 to $175, and UBS remains Neutral with a $208 target. With the stock already 15.37% above its 20-day average and close to $234.44 resistance, weak November 3 results could trigger a sharp reversal.
What to Watch
Gartner will report third-quarter 2026 results before the market opens on November 3, followed by an 8:00 a.m. ET webcast. Contract-value growth is the key metric, with UBS expecting 2.5% compared with the Street’s 2.3% expectation. Investors should watch whether management continues to express confidence in long-term contract-value acceleration. Updates on AskGartner and faster quick-takes research matter because Wells Fargo expects those initiatives to improve client engagement. On the chart, a move above $234.44 would clear near-term resistance, while a decline toward $178.52 would test near-term support. The thesis strengthens if contract growth accelerates and price breaks resistance; it weakens if revenue growth remains below zero and momentum reverses.
Analyst Consensus
HOLD

Based on 13 analyst opinions
Low Target
$150.00
Mean Target
$193.77
High Target
$235.00


Earnings and Financial Data

Sector
Technology
Industry
Information Technology Services
Employees
19,285
Earnings & Dividends
Next Earnings
Nov 03, 2026
EPS (Trailing)
$11.06
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is IT a good stock to buy?
IT has strong momentum, rising 12.14% over five trading days and 22.55% over 20 days, but revenue growth is negative at 0.6%. The takeaway: IT is a momentum-driven hold, not an obvious value buy.
What is Gartner’s stock price target?
The average analyst target is $193.77, with estimates ranging from $150 to $235. The takeaway: the average target is below the current $230.61 price.
Is Gartner stock overvalued?
Gartner trades at a P/E of 20.85 while revenue growth is negative at 0.6%. The takeaway: the valuation looks demanding without a return to revenue growth.
What are the support and resistance levels for IT stock?
Near-term support is $178.52, based on the 30-day low, and resistance is $234.44, based on the 30-day high. The takeaway: $234.44 is the immediate breakout level to watch.
How much cash and debt does Gartner have?
Gartner has $1.49 billion in total cash and $3.33 billion in total debt. The takeaway: debt is substantially higher than cash.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 24, 2026.