ALTSTATION.IO

Jack Henry & Associates, Inc. (JKHY) Stock Analysis

By Nova Skye | AltStation.io | Updated September 19, 2026

Price
$167.83
Change
+0.48%
Market Cap
$11.77B
Avg Volume
1.3M

Company Overview

Headquartered in Monett, Missouri, Jack Henry & Associates operates in the technology sector under information technology services, providing core software infrastructure and payment processing to banks and credit unions across the United States. The company generates revenue across four distinct segments: Core processing platforms, Payments, Complementary software, and Corporate Services. Its primary products include SilverLake, CIF 20/20, and Core Director for banks, Symitar for credit unions, and the Banno Digital Platform for consumer mobile banking. Since its founding in 1976, Jack Henry has focused on selling mission-critical transaction, loan, and ledger software that regional financial institutions cannot operate without.

Jack Henry is an established market leader in regional banking, forming a core oligopoly alongside Fiserv and Fidelity National Information Services (FIS) that collectively controls over 70% of the United States core banking market. While Fiserv dominates overall scale with $20.46 billion in 2024 revenue, Jack Henry holds an edge among mid-sized and community institutions through specialized service support and high platform switching costs. The primary structural threat to its business is ongoing bank consolidation, which shrinks the total pool of independent community banks and credit unions. However, replacing a core platform like Symitar or SilverLake carries massive operational friction, making Jack Henry’s existing client base exceptionally sticky.

The company is steadily expanding, growing its annual revenue from $2.16 billion in fiscal 2023 to $2.27 billion in fiscal 2024, a 5.1% increase. This expansion is driven by community institutions upgrading to modern digital interfaces through the Banno platform to keep pace with larger national banks. Rather than chasing speculative pivots, Jack Henry focuses on cross-selling high-margin payment, fraud detection, and lending modules directly into its locked-in base. It functions as a resilient, defensive cash-flow compounder rather than a breakout hyper-growth tech play.

Key Financials
Market Cap
$11.77B
Revenue
$2.54B
EBITDA
$702.21M
Gross Margin
43.9%
Profit Margin
19.8%
Revenue Growth
4.7%
Total Cash
$12.06M
Total Debt
$77.82M
Free Cash Flow
$352.22M


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
24.04
Forward P/E
21.43
Beta
0.55
52-Week High
$193.39
52-Week Low
$121.04
EPS
$6.98
50-Day Avg
$153.61
200-Day Avg
$159.91
Price/Book
5.60
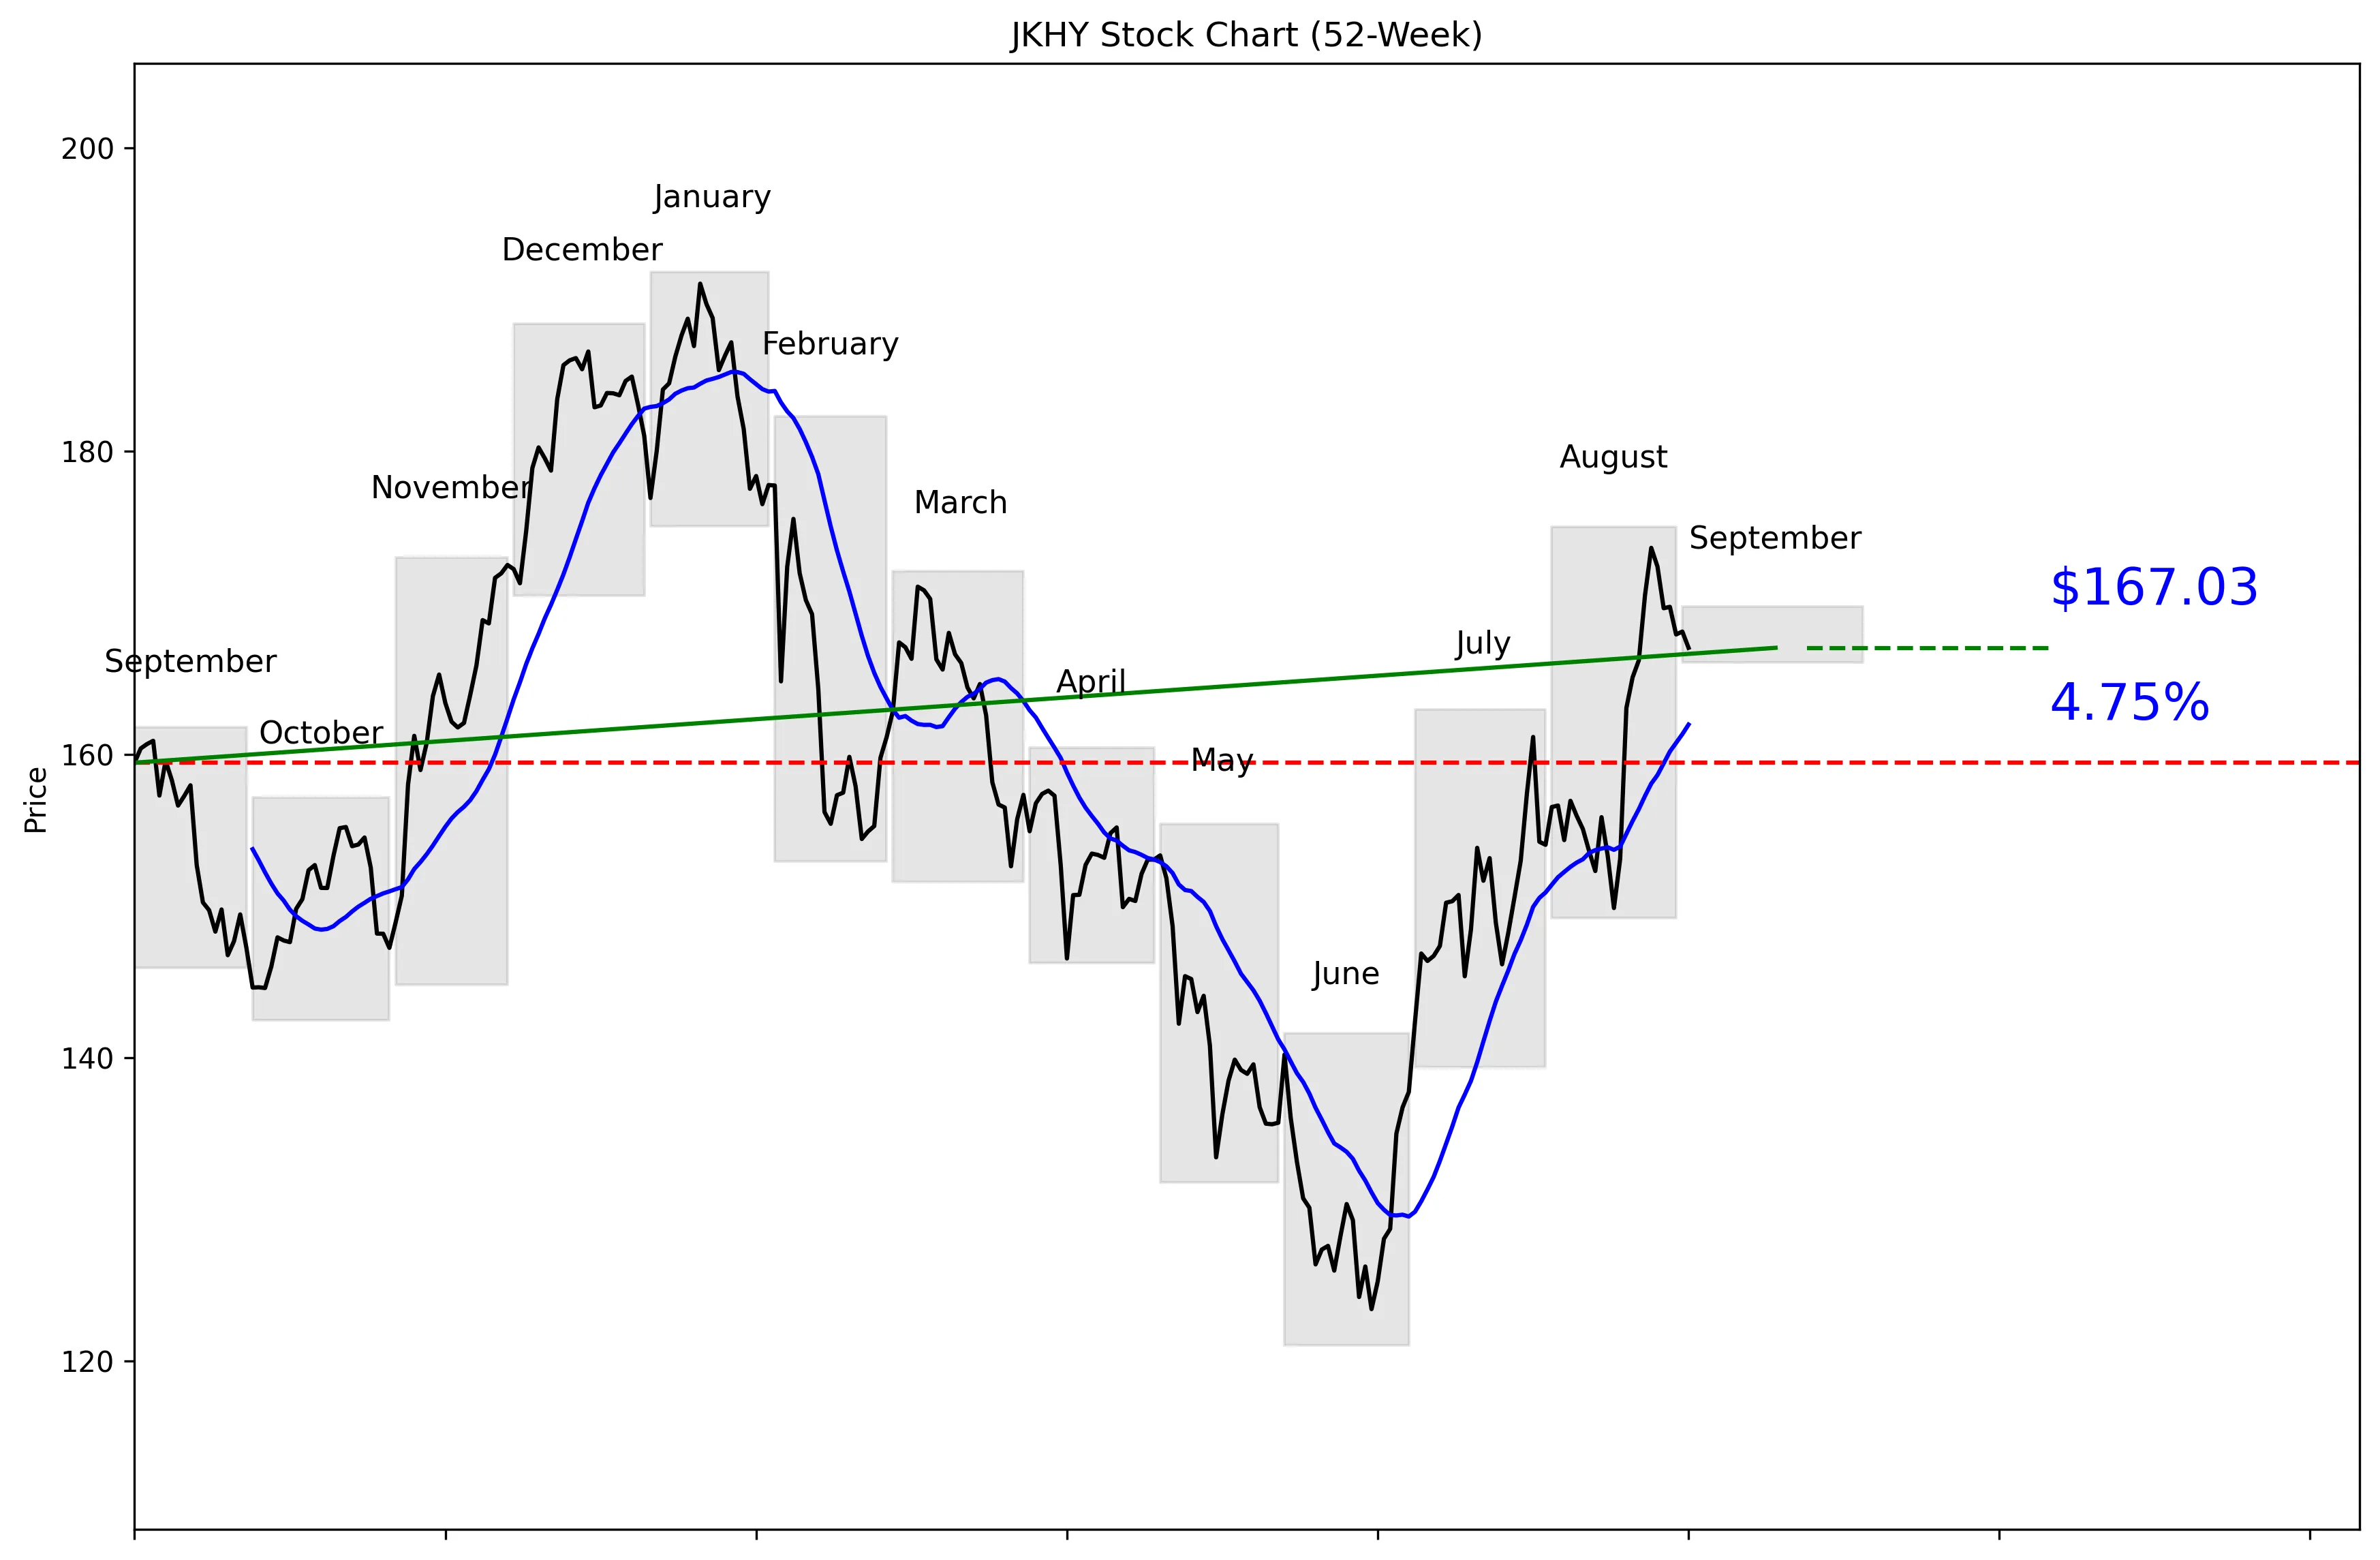
JKHY 52-Week Stock Chart
Technical Analysis
JKHY trades at $167.83, 65% of the way from its $121.04 52-week low to its $191.83 52-week high. The stock is 12.93% below that high and 38.00% above the low. Price is 3.13% above the 20-day moving average of $161.97, supported by an 8.22% gain over the last 20 trading days. Five-day momentum is weaker at -3.11%, showing that the recent advance has lost some speed. Near-term support is $148.23, while resistance sits at $173.62.


Recent News and Developments

Jack Henry contains cybersecurity incident

Jack Henry said a vishing attack by ShinyHunters reached a limited part of its internal, non-production environment and exposed personally identifiable information tied to fewer than 10 clients. Client-facing platforms stayed operational with no outages, and the company said the extortion attempt was not financially material and no payment would be made. Source: Jack Henry & Associates

Fiscal 2026 revenue rises 7.1% in new 10-K

Jack Henry filed its fiscal 2026 Form 10-K on August 28, reporting revenue of $2.544 billion, up 7.1% year over year. Net income increased 10.3% to $502.776 million, while diluted EPS rose 11.9% to $6.98. Source: U.S. Securities and Exchange Commission

DA Davidson sticks with Buy rating

DA Davidson reiterated its Buy rating on JKHY on September 2 and kept its $198 price target. This was not an upgrade or downgrade, but the target implied 17.97% upside based on the price used by MarketBeat. Source: MarketBeat


Market Sentiment and Analyst Recommendations

Bull Case
Fiscal 2026 revenue increased 7.1% to $2.544 billion, while net income rose 10.3% to $502.776 million. Diluted EPS grew even faster, climbing 11.9% to $6.98. That combination shows earnings expanding faster than sales, which is exactly what investors want from a mature financial technology company. The analyst consensus is buy across 15 analysts, with an average target of $191.53 versus the current $167.83 price. DA Davidson also maintained a Buy rating and a $198 target on September 2. The balance sheet carries just $77.82 million of debt, modest relative to a market capitalization of $11.77 billion. My take: the earnings growth, limited debt and analyst upside make JKHY attractive if it can break through $173.62.
Bear Case
JKHY trades at 24.04 times earnings, so investors are already paying a substantial multiple for the business. The supplied revenue-growth figure is 4.7%, which is not especially aggressive for a stock at that valuation. Total cash is only $12.06 million against $77.82 million of debt, leaving net debt rather than a net-cash position. The cybersecurity incident exposed personally identifiable information tied to fewer than 10 clients, creating a real trust and execution risk even though client-facing platforms stayed operational. Management said the incident was not financially material and refused payment, but investors still need evidence that the exposure is fully contained. The stock has also lost 3.11% over the last five trading days and remains 12.93% below its 52-week high. The bear case gets stronger below the $161.97 moving average and especially near the $148.23 support level.
What to Watch
CEO Greg Adelson is scheduled to present at the Goldman Sachs Communacopia + Technology Conference on September 9 at 4:05 p.m. ET. Investors should watch for any update on demand, growth or the cybersecurity incident during that presentation. The first technical test is $173.62 resistance; a move above it would support the positive 20-day momentum of 8.22%. A drop below the $161.97 moving average would weaken the near-term setup, while $148.23 is the key support threshold. Future results should be measured against fiscal 2026 revenue of $2.544 billion, net income of $502.776 million and diluted EPS of $6.98. Investors should also track whether revenue growth holds near the reported 7.1% fiscal 2026 rate or falls toward the supplied 4.7% growth figure. The cyber thesis changes materially if the company reports client-facing disruption, broader exposure or a financial impact, none of which was reported in the disclosed incident.
Analyst Consensus
BUY

Based on 15 analyst opinions
Low Target
$170.00
Mean Target
$191.53
High Target
$215.00


Earnings and Financial Data

Sector
Technology
Industry
Information Technology Services
Employees
7,300
Earnings & Dividends
Next Earnings
Nov 03, 2026
EPS (Trailing)
$6.98
Dividend Yield
146.0%
Payout Ratio
34.1%

Frequently Asked Questions

Is JKHY a good stock to buy?
The recommendation is buy based on 15 analysts, and the stock trades at $167.83 versus an average analyst target of $191.53. The clear takeaway is that analyst sentiment is positive, though the 24.04 P/E demands continued execution.
What is JKHY’s price target?
The average analyst target is $191.53, with estimates ranging from $170.00 to $215.00. The takeaway is that the consensus target sits above the current $167.83 price.
Is JKHY stock overvalued?
JKHY trades at a P/E of 24.04 while the supplied revenue-growth rate is 4.7%. The takeaway is that the valuation is not cheap relative to that growth rate.
What are JKHY’s support and resistance levels?
Near-term support is the 30-day low of $148.23, while near-term resistance is the 30-day high of $173.62. The takeaway is that these are the key technical levels around the current $167.83 price.
Does JKHY pay a dividend?
The supplied key and technical data do not include a dividend amount or yield. The takeaway is that no dividend conclusion can be made from the provided data.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated September 19, 2026.