
Gartner, Inc. (IT) Stock Analysis
By Nova Skye | AltStation.io | Updated October 24, 2026
Company Overview
Gartner sells research, executive conferences, and hands-on consulting to corporate leaders making high-stakes technology decisions. Founded in 1979 and headquartered in Stamford, Connecticut, the company operates in the Information Technology Services industry within the broader Technology sector. Its business splits into three divisions: Insights subscription services, in-person industry conferences, and tailored consulting engagements focused on digital transformation and cost optimization. Enterprise buyers and senior executives worldwide pay recurring fees to access proprietary data, benchmarks, and direct analyst guidance to derisk multi-million-dollar software and infrastructure investments.
Gartner is the undisputed market leader in enterprise IT research, holding far more pricing power and executive reach than direct rivals like Forrester Research and IDC. Its primary moat is the subscription-driven Insights division, which generates high-margin recurring cash flow backed by sticky client retention. The consulting arm faces tough competition from heavyweight professional services firms like Accenture and Deloitte, but Gartner’s proprietary research gives it an immediate foot in the boardroom door. The biggest emerging threat to its business model is whether generative AI tools commoditize entry-level advisory reports, forcing Gartner to prove its human analysts remain worth premium prices.
The business remains fundamentally healthy and growing, pulling in 6.26 billion dollars in 2024 revenue, up roughly 6.1 percent over 2023’s 5.90 billion dollars. While top-line expansion has moderated from previous high-single-digit rates, Gartner continues to grind out steady gains by expanding into non-IT executive roles and riding a wave of demand for AI advisory work. Tightening enterprise budgets and scrutiny on consulting fees remain active headwinds, but the company’s subscription foundation protects its core profitability. It is not a hyper-growth tech play, but a disciplined, cash-generative machine that corporate decision-makers still treat as essential insurance.
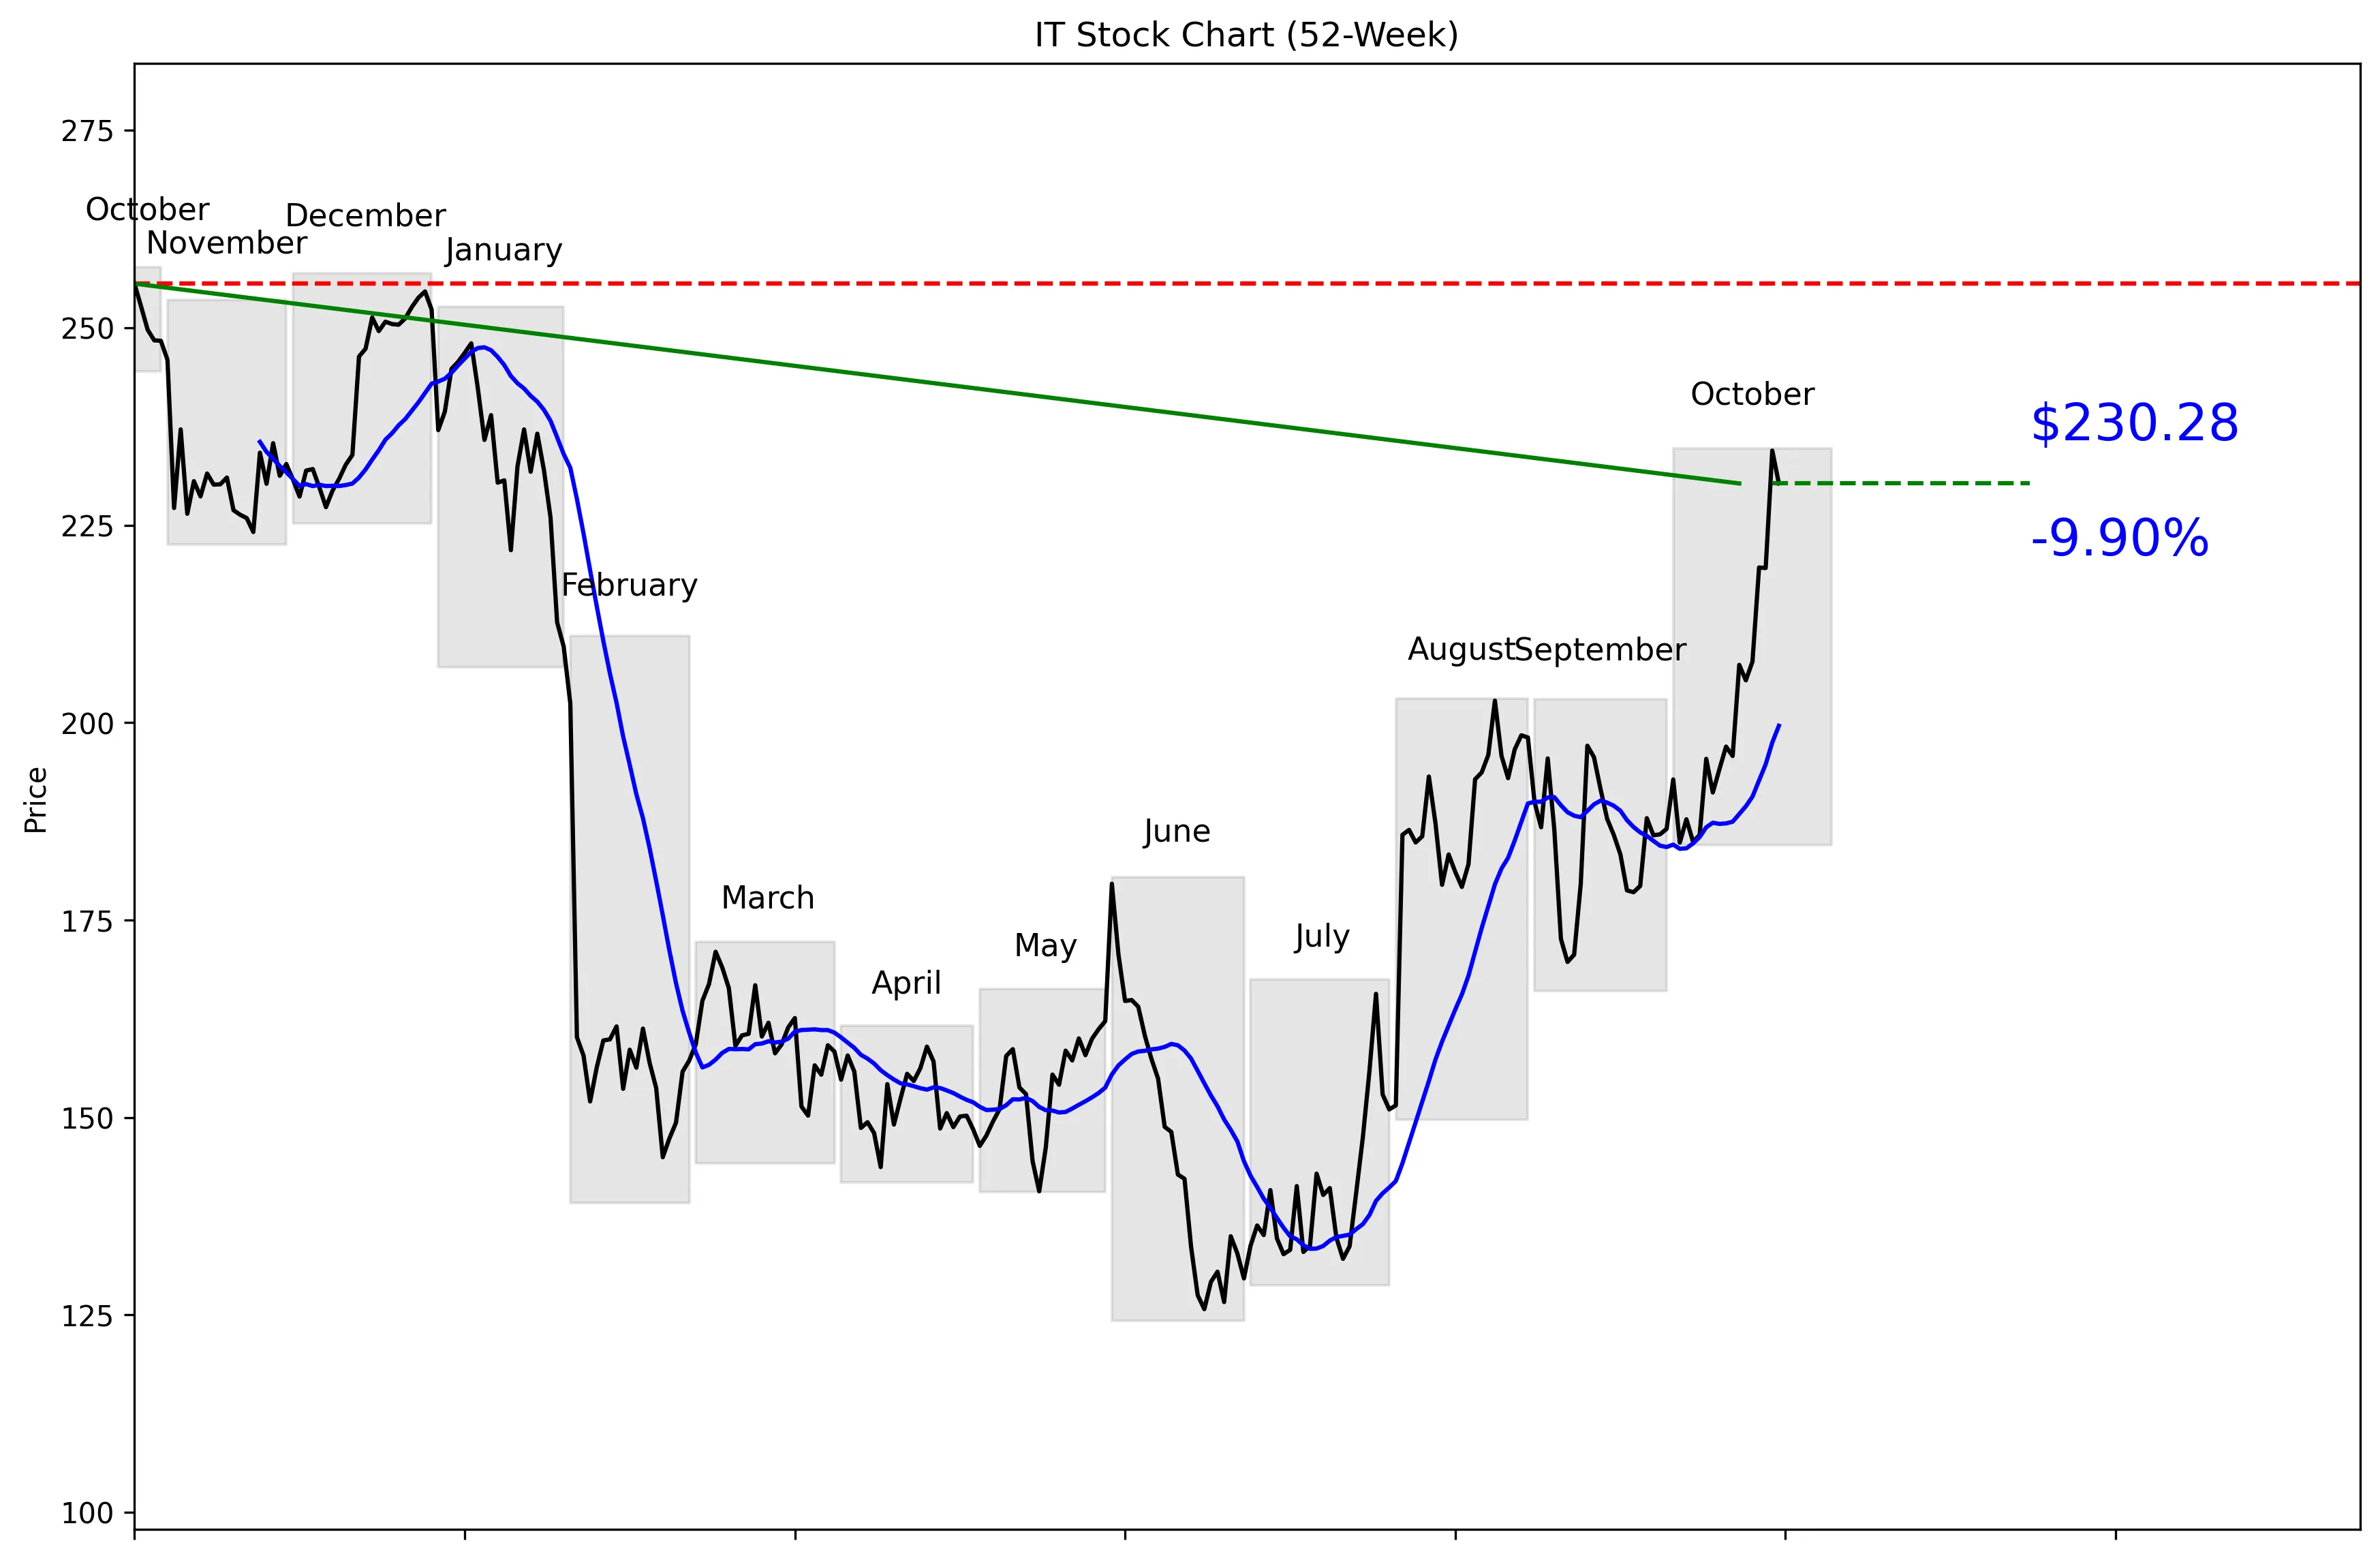
52-Week Price Performance Analysis
Recent News and Developments
Gartner traded at $217.61 on October 20, up 4.8% from the previous close. The move followed price-target increases from Truist Securities and Wells Fargo after meetings around Gartner’s IT Symposium. Source: Yahoo Finance
Truist Securities raised its Gartner price target from $205 to $235 and maintained its Buy rating. The firm cited double-digit year-over-year growth in IT Symposium attendance and management’s confidence in long-term contract-value acceleration. Source: Investing.com
Wells Fargo increased its Gartner price target from $150 to $175 while maintaining an Underweight rating. The firm expects Gartner’s Business and Technology Insights transformation, including AskGartner and faster “quick-takes” research, to improve client engagement. Source: Investing.com
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports