ALTSTATION.IO

Walmart Inc. (WMT) Stock Analysis

By Nova Skye | AltStation.io | Updated September 19, 2026

Price
$108.44
Change
+0.32%
Market Cap
$860.30B
Avg Volume
24.2M

Company Overview

Walmart Inc. operates as the world’s largest discount store chain, headquartered in Bentonville, Arkansas, within the Consumer Defensive sector. The company serves hundreds of millions of everyday shoppers and small businesses across three primary segments: Walmart U.S., Walmart International, and Sam’s Club. It sells high-turnover staples ranging from groceries, fresh produce, and pharmacy items to electronics, apparel, and home improvement goods. Outside its supercenters and warehouse clubs, Walmart also operates digital payment platforms like PhonePe, international sites like Flipkart, and financial services such as check cashing and money transfers.

Walmart is the undisputed market leader in the retail space, weaponizing its massive scale and physical footprint to underprice traditional competitors. Its network of thousands of clubs and supercenters doubles as local fulfillment hubs, giving it a durable cost advantage over pure-play e-commerce rivals like Amazon in same-day grocery delivery. Still, the company faces tough price-to-value competition from warehouse operators like Costco and deep discounters like Target and Aldi. The core risk is margin pressure if wage and supply chain costs rise faster than its ability to pass expenses to price-sensitive shoppers.

Walmart is growing at a solid clip, generating 681.0 billion dollars in total revenue for fiscal year 2025, which marks a 5.1 percent increase over the prior year. Operating income climbed 8.6 percent over the same period, proving that efficiency gains are translating directly to the bottom line. Growth is heavily fueled by digital channels, having crossed the 100 billion dollar annual e-commerce milestone in fiscal 2024. Sam’s Club also continues to outperform, posting 6.8 percent comparable sales growth and 24 percent e-commerce growth in the fourth quarter of fiscal 2025.

Key Financials
Market Cap
$860.30B
Revenue
$735.84B
EBITDA
$44.07B
Gross Margin
24.8%
Profit Margin
3.0%
Revenue Growth
5.9%
Total Cash
$11.53B
Total Debt
$75.09B
Free Cash Flow
$7.13B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
39.29
Forward P/E
33.57
Beta
0.59
52-Week High
$135.16
52-Week Low
$98.88
EPS
$2.76
50-Day Avg
$110.22
200-Day Avg
$118.75
Price/Book
9.15
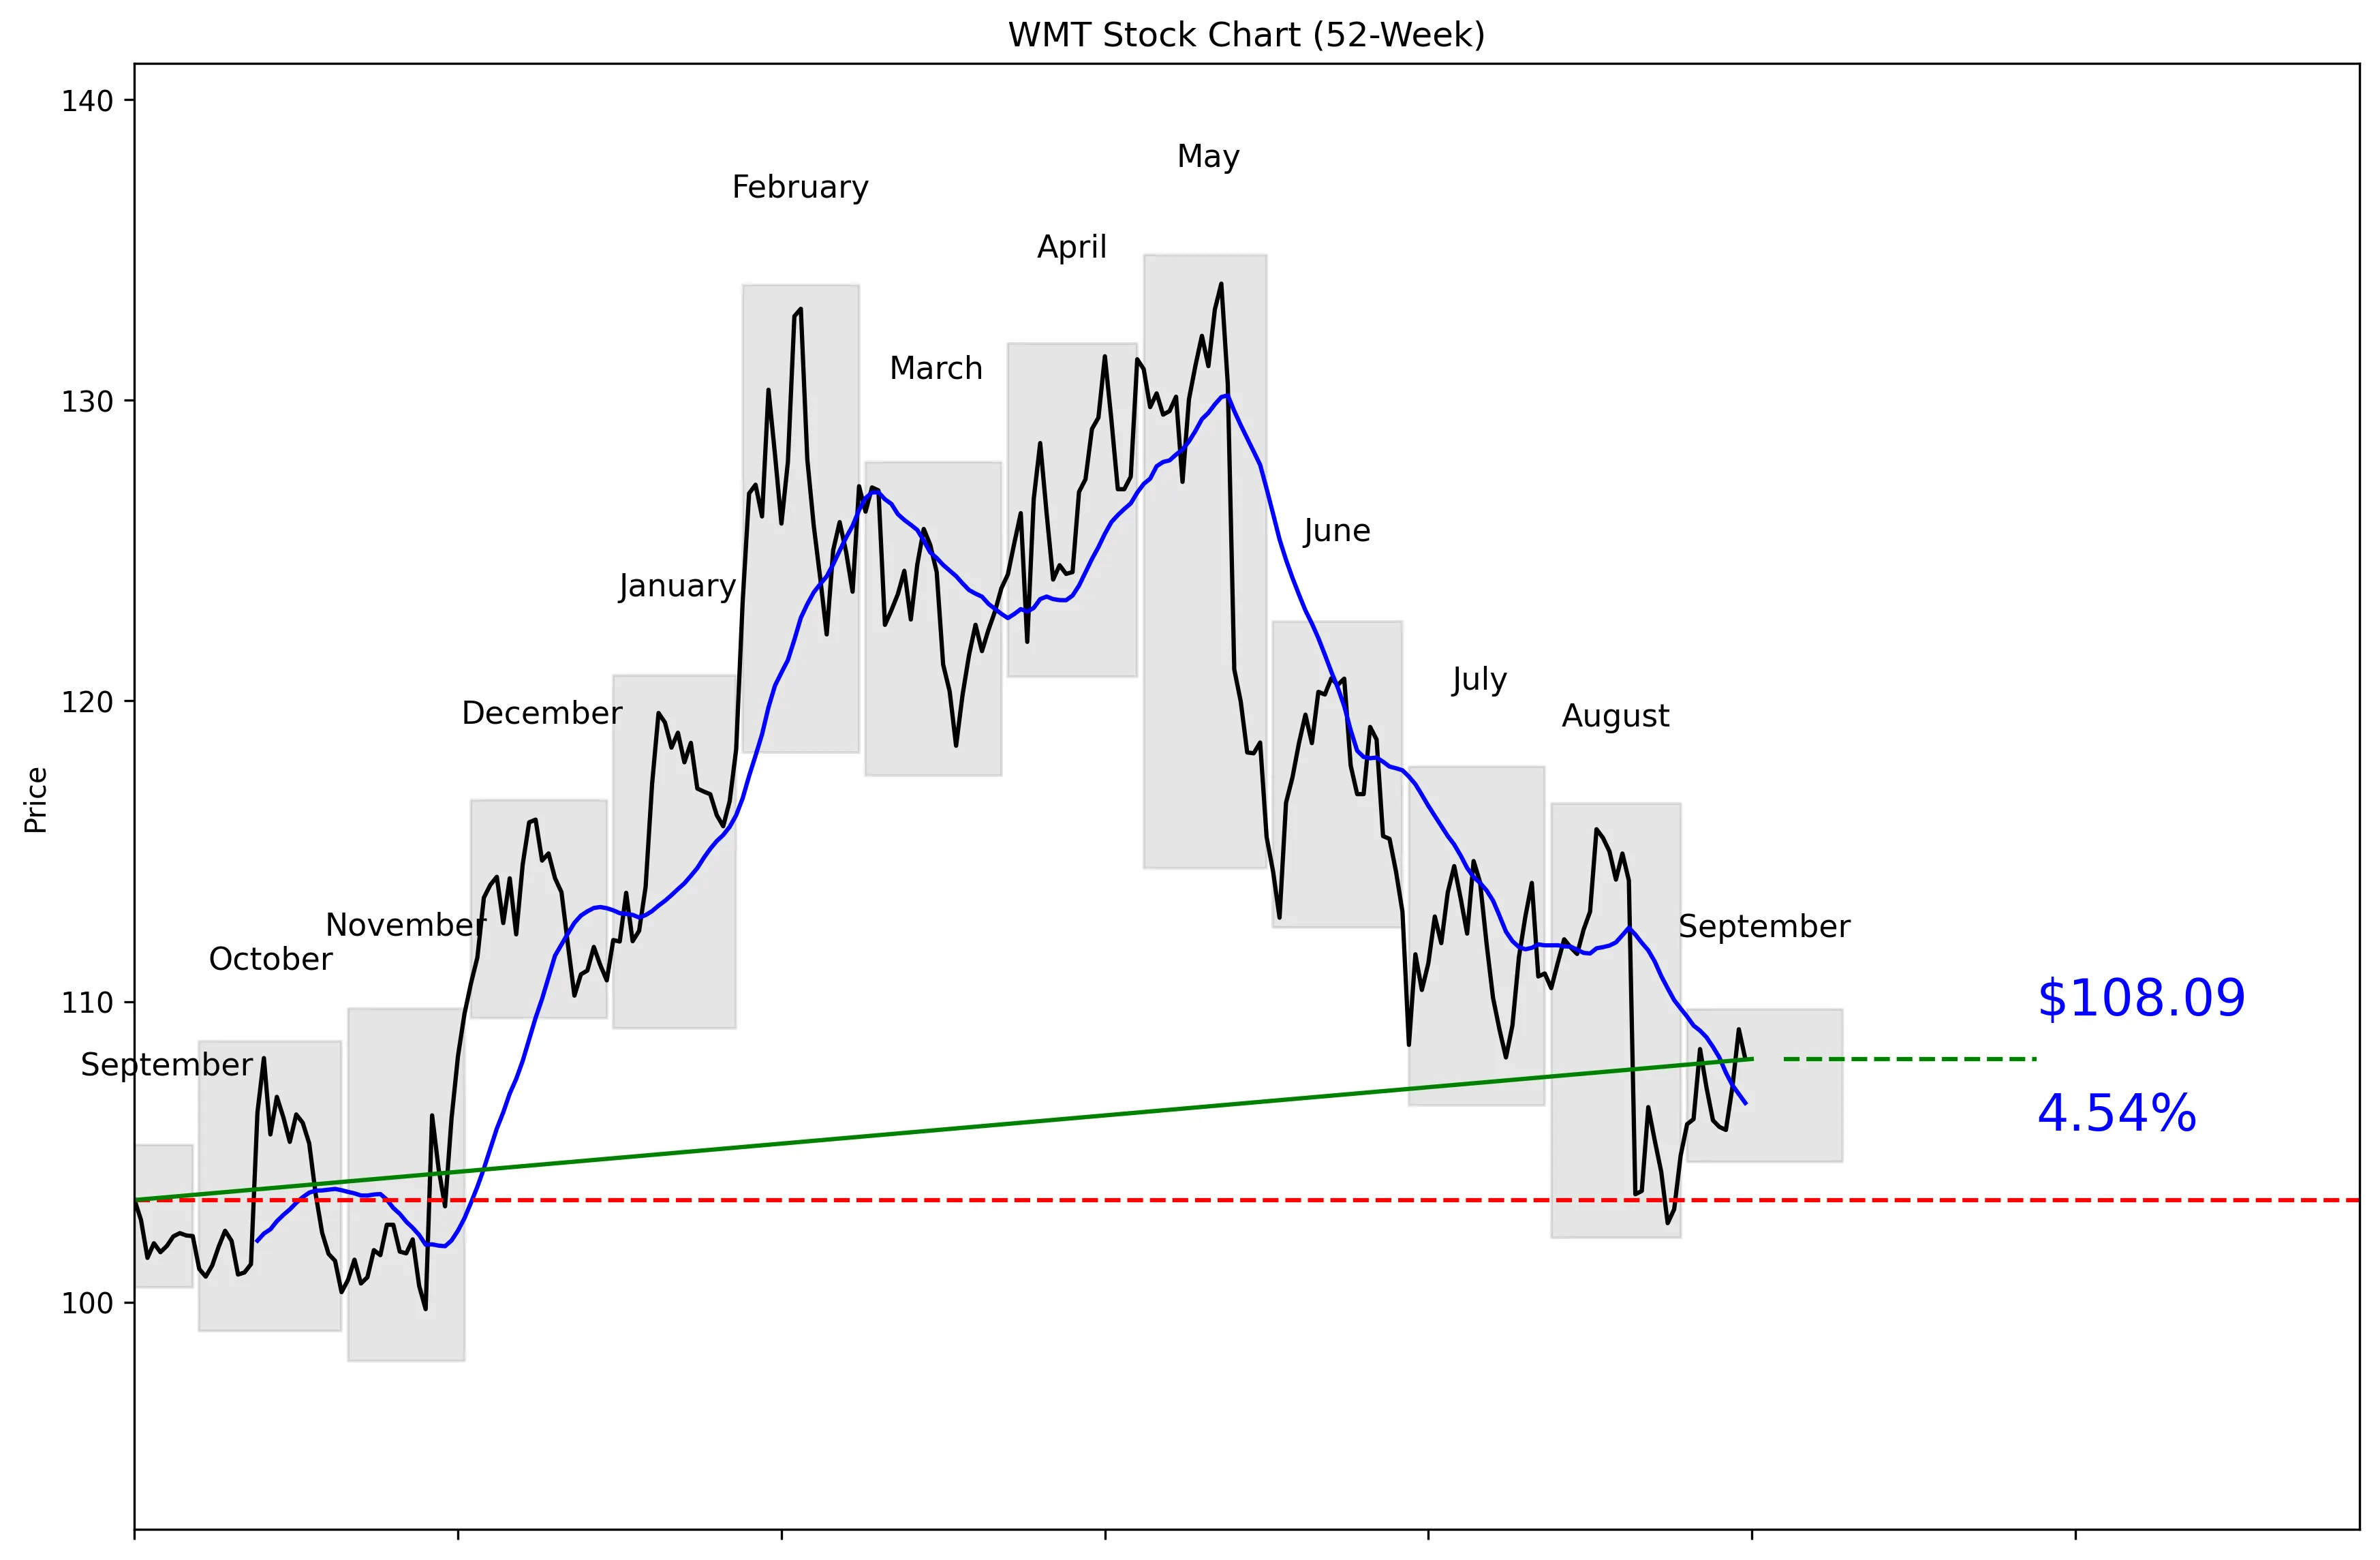
WMT 52-Week Stock Chart
Technical Analysis
WMT trades at $108.44, 19.84% below its $134.84 52-week high and 10.23% above its $98.05 low. The stock sits 27% of the way from the low to the high, putting it in the lower third of its 52-week range. Price is 1.37% above the 20-day moving average of $106.63, while five-day momentum is positive at 1.92%. The broader 20-day momentum remains negative at 5.23%, so the short-term rebound has not reversed the recent decline. Near-term support is $102.63, and resistance is $115.73.


Recent News and Developments

Walmart’s e-commerce streak stays hot

Walmart U.S. CEO Dave Guggina said e-commerce grew 24% last quarter, marking the tenth consecutive quarter above 20%. Sparky’s visual-shopping feature converts 57% better than text-based shopping, while weekly engagement rose more than 60% quarter over quarter and average order value increased 40%. Source: Stock Analysis

Drug-pricing rules remain a sales headwind

Walmart said Maximum Fair Pricing affected about 10 high-volume drugs, creating a top-line headwind for its health and wellness operation. Another 15 drugs are expected to enter the program next year, although the business delivered double-digit profit improvement year over year. Source: Stock Analysis

Analysts reaffirm bullish WMT ratings

DA Davidson reiterated its Buy rating and $132 price target on September 10, while BTIG repeated its Buy rating and $140 target. KeyCorp also reaffirmed an Overweight rating. Source: PriceTargets.com


Market Sentiment and Analyst Recommendations

Bull Case
Walmart generated $735.84 billion in revenue while maintaining 5.9% revenue growth, proving that its enormous scale is not preventing expansion. Walmart U.S. e-commerce grew 24% last quarter, its tenth consecutive quarter above 20%. Sparky’s visual-shopping feature converts 57% better than text-based shopping, while weekly engagement increased more than 60% quarter over quarter and average order value rose 40%. Those numbers show that Walmart’s digital business is improving both customer activity and transaction value. The average analyst target of $127.42 is $18.98 above the current $108.44 price, and 40 analysts rate the stock a buy. DA Davidson and BTIG are even more bullish, with targets of $132 and $140, respectively. The bull case is straightforward: sustained digital growth plus a stock trading 19.84% below its 52-week high creates a credible rebound setup.
Bear Case
Walmart’s 39.29 P/E is expensive for a company growing revenue by 5.9%. Investors are paying a premium valuation, so weaker growth or execution could hit the stock hard. Total debt of $75.09 billion is more than six times the company’s $11.53 billion in cash, limiting the balance-sheet cushion. The stock remains 19.84% below its 52-week high, and 20-day momentum is still negative at 5.23%. Drug-pricing rules are already creating a sales headwind across about 10 high-volume drugs, with another 15 expected to enter the program next year. Health and wellness delivered double-digit profit improvement year over year, but further pricing pressure could offset that progress. At $108.44, WMT is not cheap enough to ignore these risks.
What to Watch
The first number to track next quarter is e-commerce growth, which reached 24% last quarter after ten consecutive quarters above 20%. Investors should also watch whether Sparky can sustain its 57% conversion advantage, more than 60% quarterly engagement growth and 40% increase in average order value. Health and wellness results matter because Maximum Fair Pricing is affecting about 10 high-volume drugs, with another 15 expected to enter the program next year. The tap-to-pay rollout is another execution test as Walmart works toward coverage at all U.S. Walmart and Sam’s Club locations by the end of 2026. On the chart, a move above $115.73 would clear near-term resistance, while a break below $102.63 would weaken the rebound. Holding above the $106.63 20-day moving average would support the short-term recovery, but 20-day momentum needs to improve from negative 5.23%. The core thesis strengthens if revenue growth stays near or above 5.9% while e-commerce remains above 20%.
Analyst Consensus
BUY

Based on 40 analyst opinions
Low Target
$81.00
Mean Target
$127.42
High Target
$155.00


Earnings and Financial Data

Sector
Consumer Defensive
Industry
Discount Stores
Employees
2,100,000
Earnings & Dividends
Next Earnings
Nov 19, 2026
EPS (Trailing)
$2.76
Dividend Yield
92.0%
Payout Ratio
35.0%

Frequently Asked Questions

Is WMT a good stock to buy?
The recommendation is buy based on 40 analysts, and the average analyst target is $127.42 versus a current price of $108.44. The takeaway is that analyst sentiment is bullish, but the 39.29 P/E makes valuation an important consideration.
What is WMT’s price target?
The average analyst target is $127.42, with estimates ranging from $81.00 to $155.00. The takeaway is that Wall Street’s outlook is positive on average but unusually wide.
How far is WMT below its 52-week high?
WMT is 19.84% below its technical 52-week high of $134.84. The takeaway is that the stock remains well below its peak despite trading 1.37% above its 20-day moving average.
What are WMT’s support and resistance levels?
Near-term support is the 30-day low of $102.63, while near-term resistance is the 30-day high of $115.73. The takeaway is that these are the key levels framing the current trading range.
Does WMT pay a dividend?
The provided data does not include dividend information. The takeaway is that no dividend conclusion can be made from these figures alone.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated September 19, 2026.