
UnitedHealth Group Incorporated (UNH) Stock Analysis
By Nova Skye | AltStation.io | Updated October 15, 2026
Company Overview
UnitedHealth Group is the largest player in the healthcare plans industry, headquartered in Eden Prairie, Minnesota, and founded in 1974. The company runs four key business units: UnitedHealthcare for medical insurance, Optum Health for clinical care delivery, Optum Rx for pharmacy services, and Optum Insight for healthcare software and analytics. Its customer base spans individual consumers, employers of all sizes, state and federal programs like Medicaid and Medicare, and hospital systems. It makes money by collecting health plan premiums, managing pharmacy benefits, and selling technology and healthcare services directly to providers and payers.
UnitedHealth is the undisputed market leader in U.S. managed care, controlling roughly 16% of the commercial health insurance market. Its real competitive edge is vertical integration: Optum feeds patient care, pharmacy management, and data directly into UnitedHealthcare, capturing revenue at every link of the healthcare chain. While peers like Elevance Health, CVS Health, and The Cigna Group fight for membership, UnitedHealth’s massive scale gives it pricing leverage competitors cannot match. The primary risk to its business model comes from regulatory scrutiny over pharmacy benefit managers and rising medical care utilization across government-backed plans.
The business continues to expand at a steady pace, generating $447.6 billion in revenue in 2025, which represents 12% year-over-year growth. Optum remains the primary growth engine, expanding care delivery and specialty pharmacy services alongside the core insurance division. Instead of pivoting away from managed care, UnitedHealth is doubling down on its integrated ecosystem to capture value across every patient touchpoint. For investors, this is a dominant defensive compounder with unmatched cash flow, not a turnaround story.
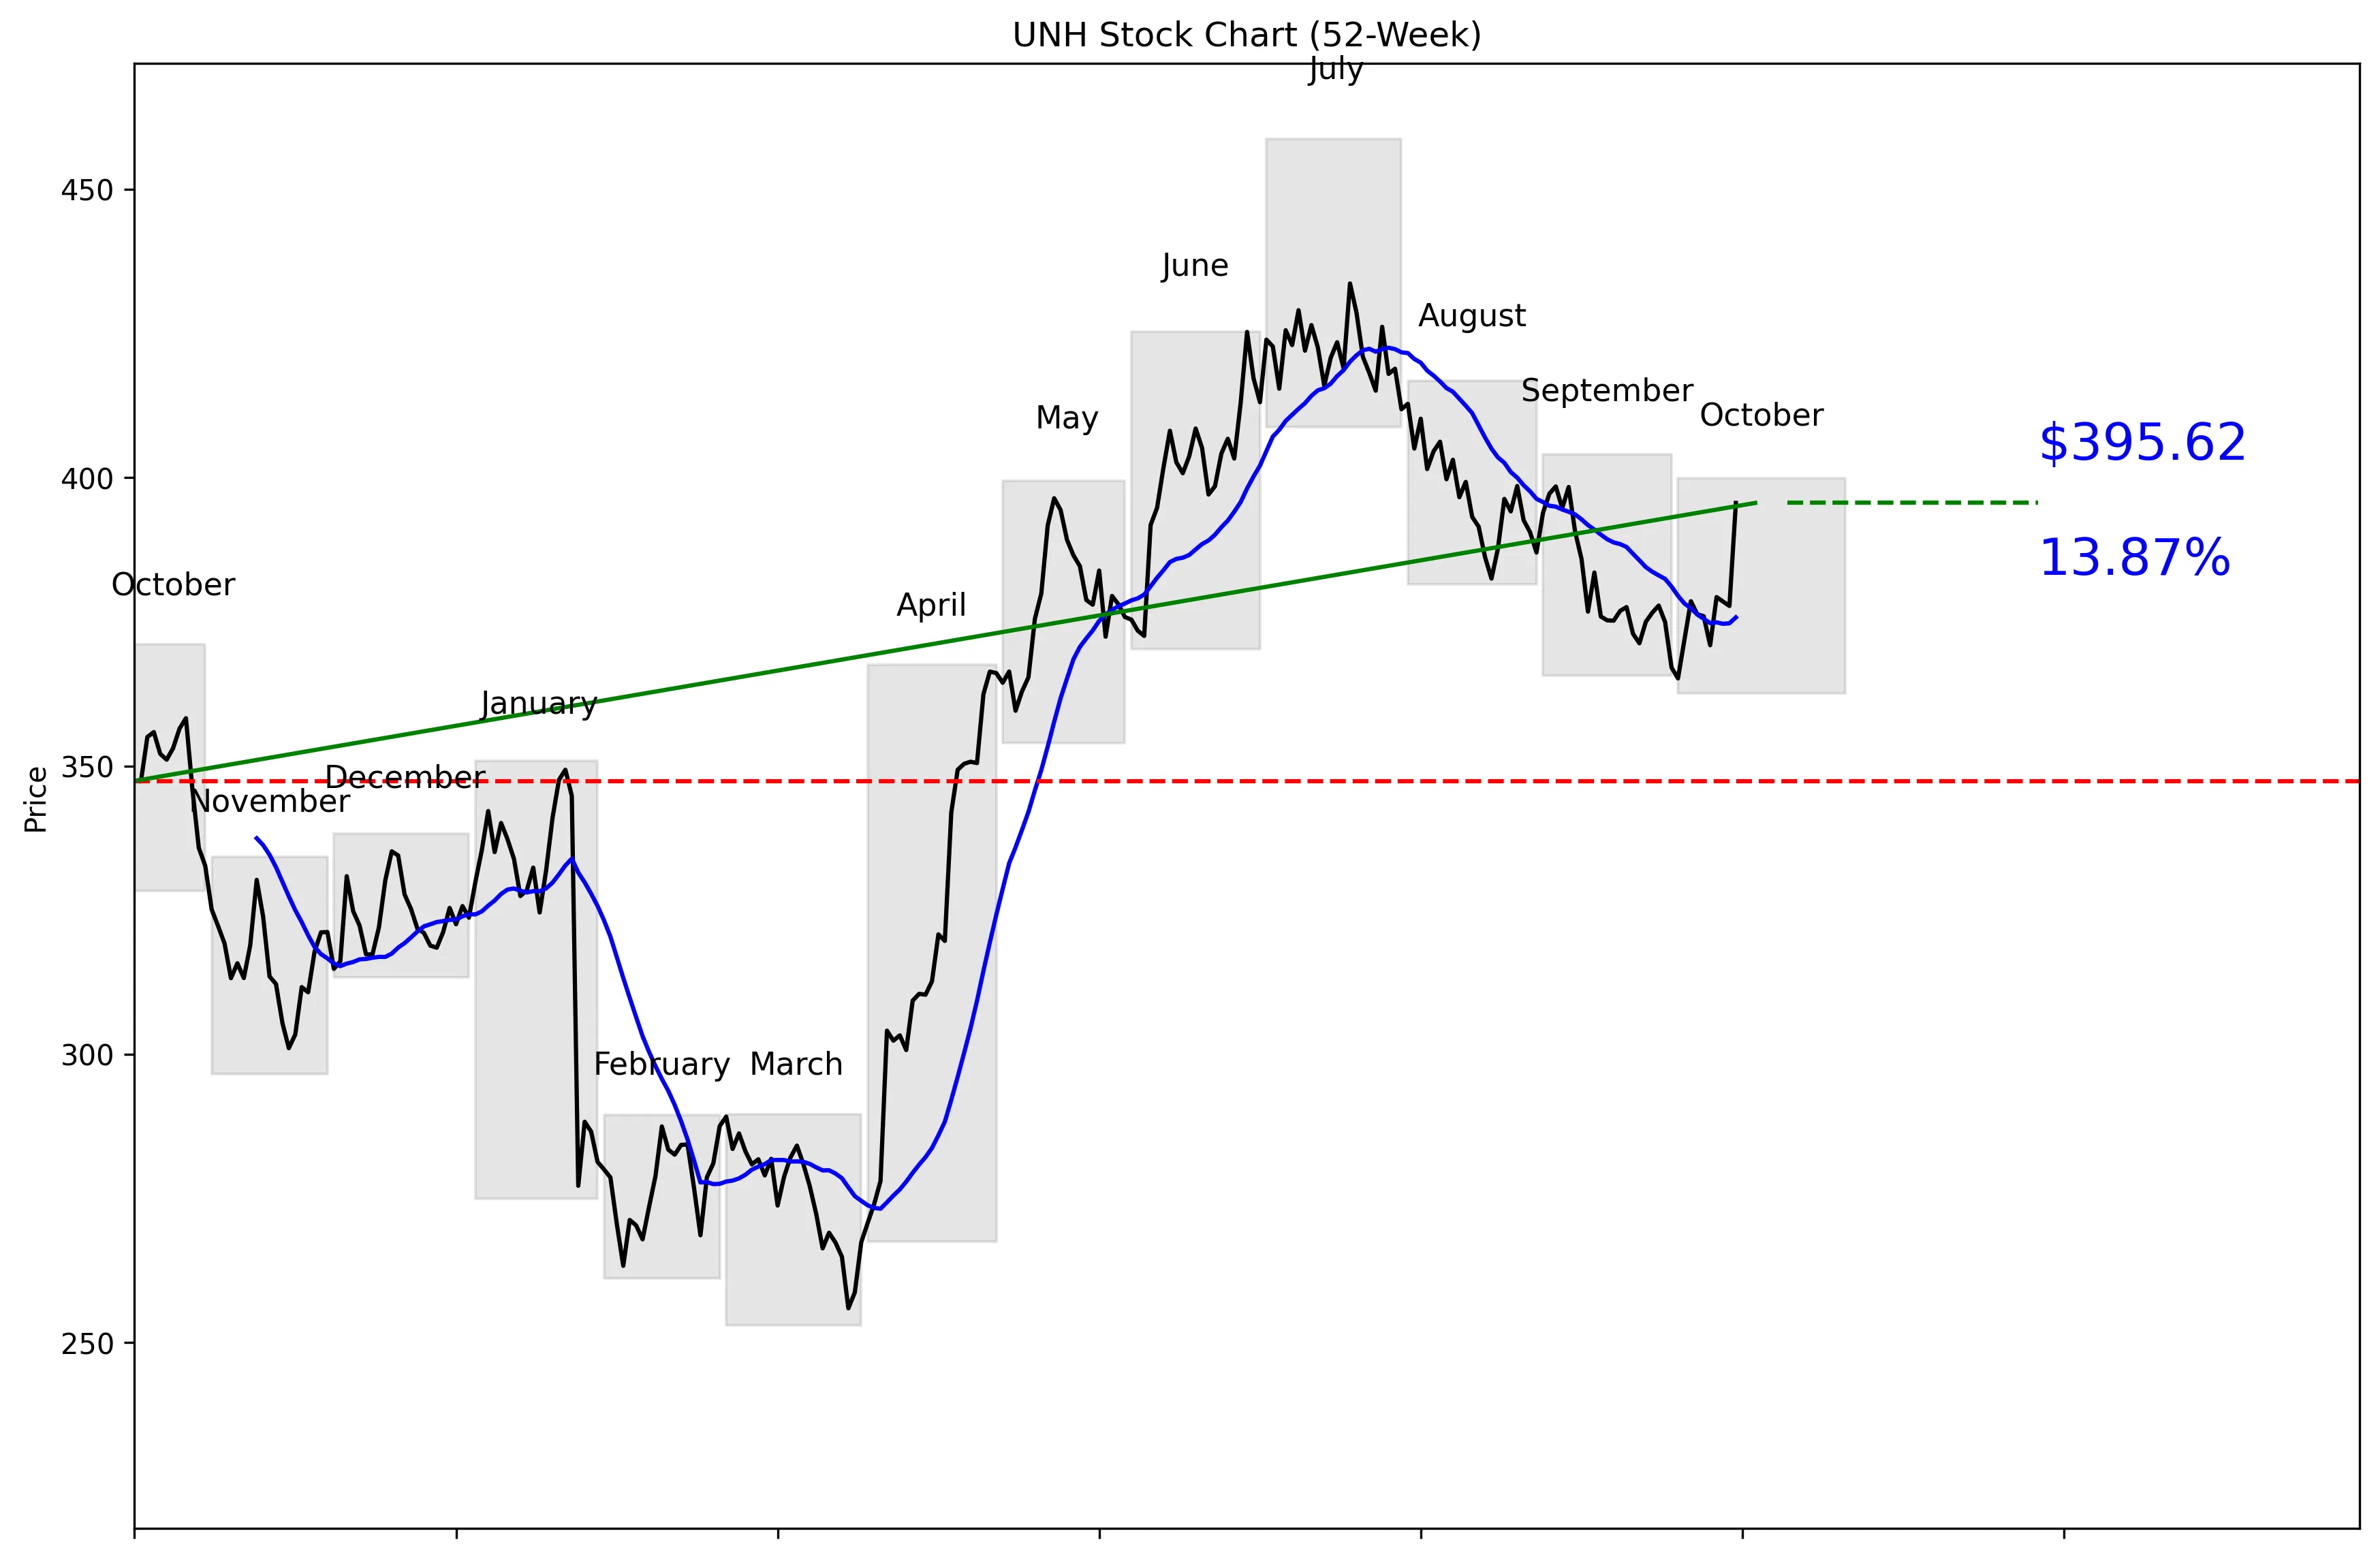
52-Week Price Performance Analysis
Recent News and Developments
UnitedHealth reported third-quarter revenue of $112.7 billion, operating earnings of $6.6 billion and adjusted earnings of $4.69 per share. Management raised its full-year adjusted earnings outlook to at least $20.50 per share. Source: UnitedHealth Group
Piper Sandler kept its Overweight rating and raised its price target from $502 to $504 on October 14. Barclays maintained Overweight but trimmed its target from $441 to $440, while Baird maintained Neutral and cut its target from $453 to $427. Source: Benzinga
TD Cowen analyst Ryan Langston maintained a Hold rating on October 9 and lowered the price target from $430 to $402. That was a 6.51% reduction ahead of UnitedHealth’s third-quarter report. Source: GuruFocus
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports