Humana Inc. (HUM) Stock Analysis
By Nova Skye | AltStation.io | Updated October 08, 2026
Company Overview
Humana Inc. operates in the Healthcare sector under the Healthcare Plans industry, headquartered in Louisville, Kentucky since its founding in 1961. The company generates revenue through two primary segments: Insurance and CenterWell. Its Insurance segment sells individual and group Medicare Advantage plans, prescription drug policies, Medicare supplements, and specialty dental and vision coverage to seniors and military families. Its CenterWell segment operates dedicated senior primary care clinics, home health services, pharmacy operations, and post-acute care coordination.
Humana is the second-largest Medicare Advantage provider in the United States, trailing only UnitedHealth Group. Together, UnitedHealth and Humana account for nearly half of all national Medicare Advantage enrollment and hold the top market share in two-thirds of U.S. counties. Humana’s proprietary CenterWell clinic network gives it a solid clinical moat against competitors like CVS Health and Elevance Health. However, its heavy concentration in government-funded programs leaves the business uniquely vulnerable to Medicare reimbursement cuts and rising medical utilization.
The company is currently executing a margin reset as higher senior healthcare utilization and tighter government payment rates compress insurer profits. Instead of chasing aggressive membership growth, Humana is prioritizing pricing discipline, cost reduction, and the expansion of its value-based CenterWell primary care assets. That strategy aims to lock in higher medical margins and capture more revenue per patient across its clinical footprint. HUM remains the purest large-cap play on aging demographics, but its trajectory hinges entirely on management’s ability to rein in medical loss ratios.
52-Week Price Performance Analysis
Recent News and Developments
Cantor Fitzgerald upgraded HUM from Neutral to Overweight and raised its price target from $300 to $460, citing stronger confidence in Medicare Advantage margins and Star Ratings recovery. The firm raised its 2027 EPS estimate from $15.86 to $17.96 and its 2028 estimate from $25.38 to $28.27. Source: Investing.com
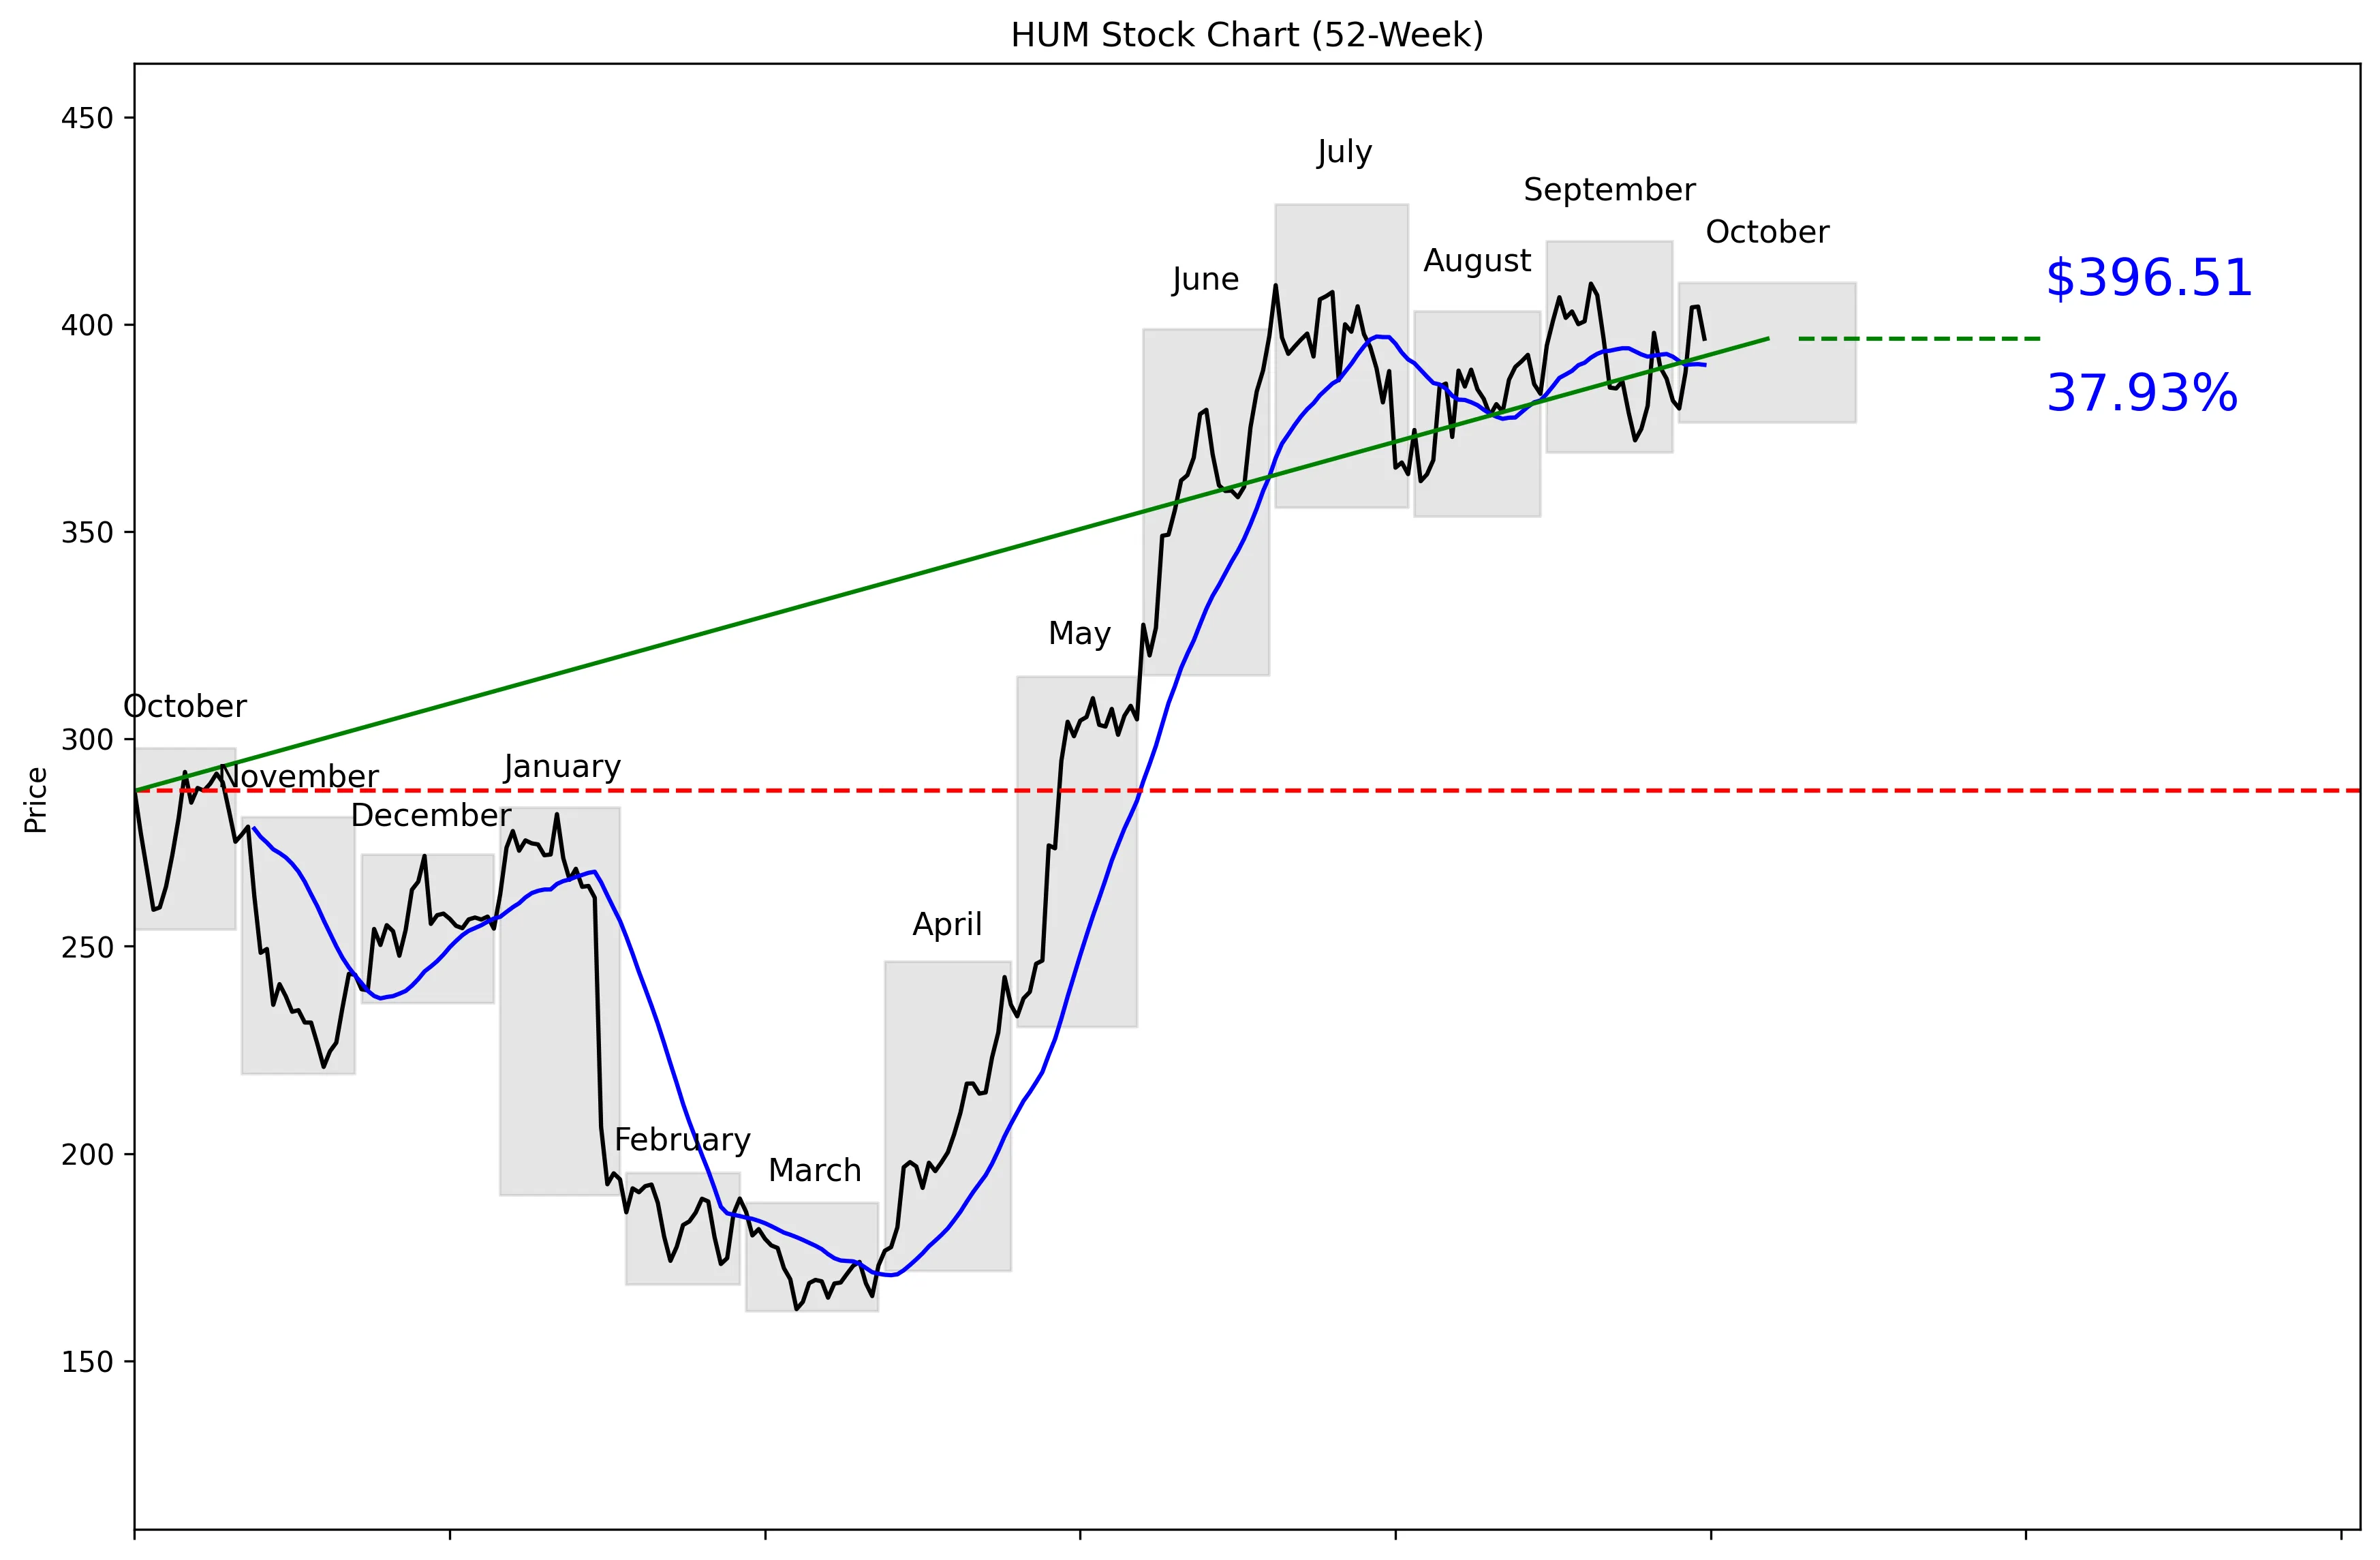
Humana gained 4.05% on October 5 and closed at $404.07, then finished October 7 at $396.51 after falling 1.92%. Shares were down another 2.04% at $388.43 as of 10:04 a.m. EDT on October 8. Source: Stock Analysis
Humana will offer 2027 Medicare Advantage plans in approximately 2,600 counties across 45 states and Washington, D.C., covering more than 80% of U.S. counties. The lineup adds $0 in-network routine lab services and expands Chronic Condition Special Needs Plans into Pennsylvania, Utah and Wisconsin. Source: Humana
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports