
PayPal Holdings, Inc. (PYPL) Stock Analysis
By Nova Skye | AltStation.io | Updated November 03, 2026
Company Overview
PayPal Holdings, Inc. is a San Jose-based digital payments platform operating in the Credit Services industry within Financial Services. Founded in 1998, the company runs a two-sided network connecting merchants and consumers for online and in-person transactions. Its platform lets users store, transfer, and withdraw funds across bank accounts, cards, account balances, and cryptocurrencies. The business delivers payment processing and financial tools across 8 key brands: PayPal, PayPal Credit, Braintree, Venmo, Xoom, Hyperwallet, Honey, and Paidy. Everyday shoppers use these tools for checkout and money transfers, while commercial merchants deploy them to accept and manage customer payments.
PayPal sits as an incumbent market leader in digital checkout due to the scale of its two-sided network. Its competitive edge comes from widespread consumer brand recognition and high-volume platforms like Venmo for peer-to-peer transfers and Braintree for merchant processing. The primary threat is that digital credit services and checkout processing are heavily contested by alternative digital wallets, card networks, and rival payment providers. If merchants adopt lower-cost payment rails or competing checkout buttons, PayPal risks pricing pressure and lower transaction margins on its core volume.
Today, PayPal is in a mature phase focused on deepening engagement and extracting more value across its existing network. The strategic priority centers on integrating its 8 distinct brand properties into a unified commerce ecosystem, linking checkout, Honey rewards, cross-border remittances via Xoom, and local payment methods like Paidy. Growth now relies on increasing checkout conversion rates and expanding consumer credit products rather than purely adding new accounts. It remains a durable, cash-generative payments heavyweight that must continuously defend its core checkout market share.
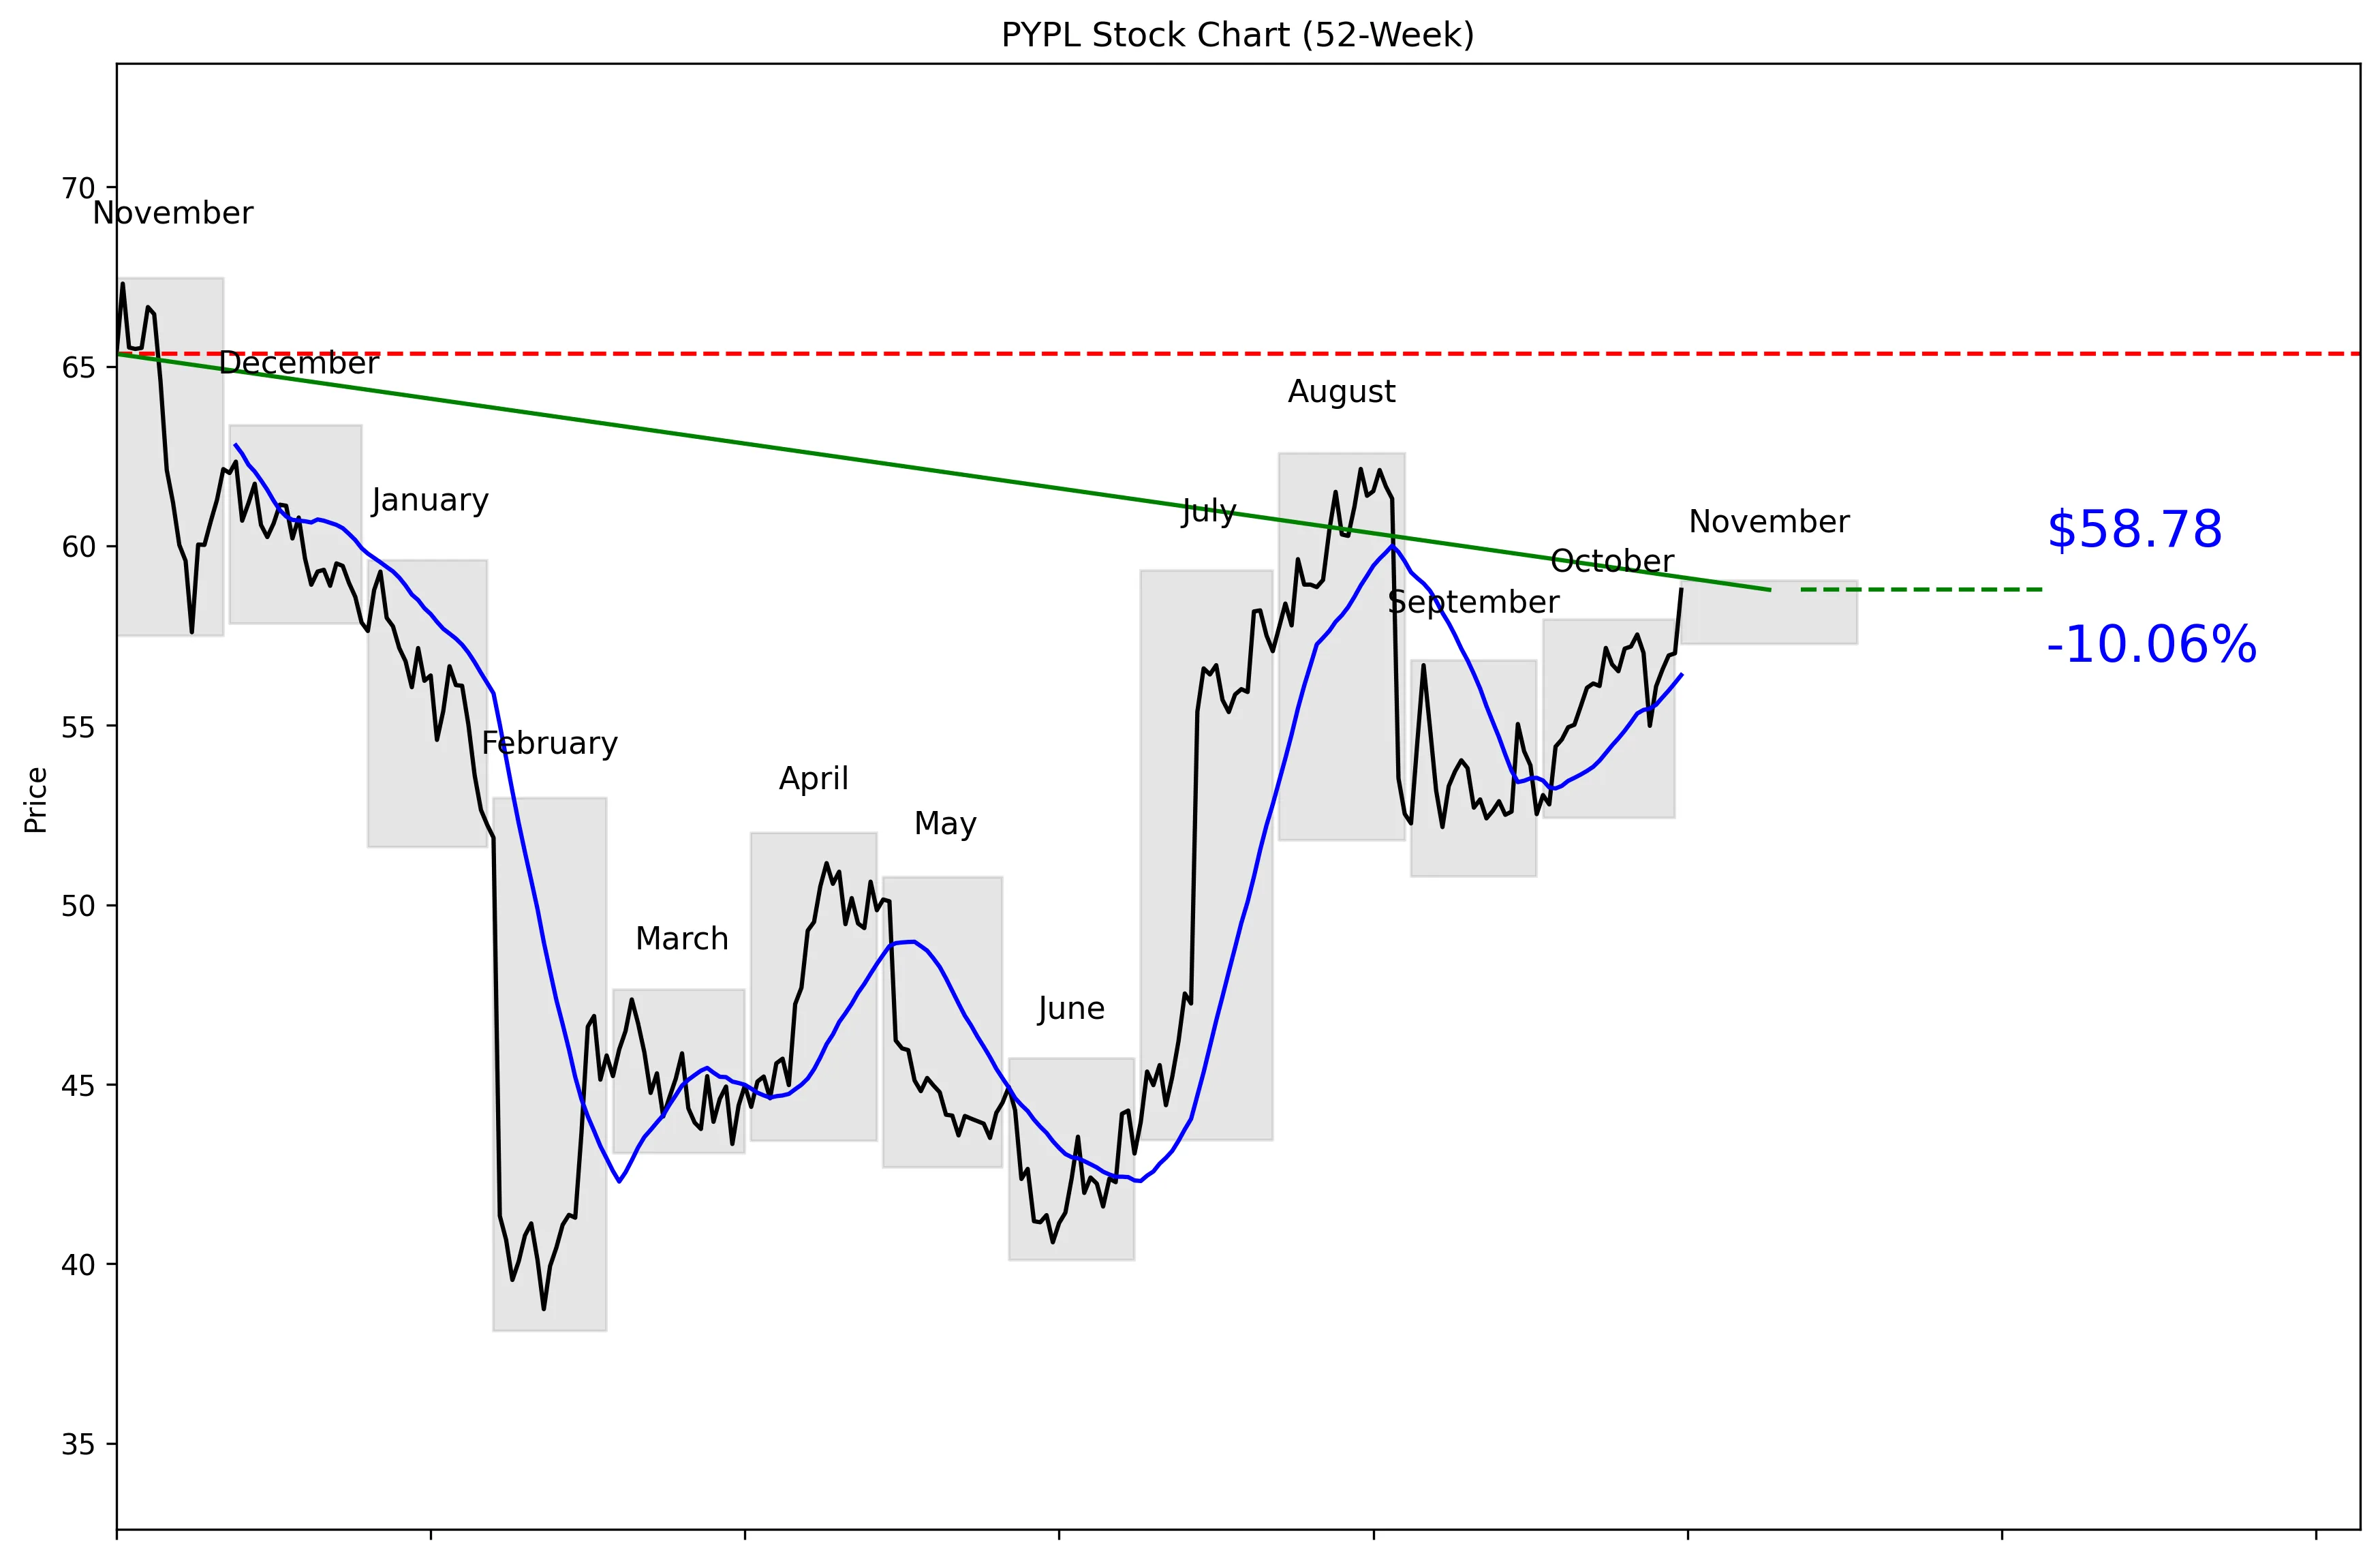
52-Week Price Performance Analysis
Recent News and Developments
Third-quarter revenue rose 2% to $8.584 billion, while non-GAAP EPS increased 8% to $1.45. Total payment volume reached $487.1 billion, up 6%, but GAAP operating income fell 8% to $1.402 billion. Source: U.S. Securities and Exchange Commission
PayPal raised its 2026 non-GAAP EPS forecast to approximately $5.60 from approximately $5.38. The company also declared a $0.14-per-share dividend and repurchased approximately 28 million shares for $1.5 billion during the quarter. Source: PayPal Newsroom
BofA Securities raised its PayPal price target to $54 from $53 while keeping an Underperform rating. The firm remains cautious because PayPal’s branded business is not expected to improve during the fourth quarter. Source: Investing.com
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports