ALTSTATION.IO

American Express Company (AXP) Stock Analysis

By Nova Skye | AltStation.io | Updated October 20, 2026

Price
$315.23
Change
+0.52%
Market Cap
$212.88B
Avg Volume
2.9M

Company Overview

American Express is a New York-based financial services firm founded in 1850 that operates as a closed-loop payments and credit services powerhouse. The company makes its money by issuing premium credit and charge cards, providing banking and lending products, and running its own merchant processing network. Its customer base spans individual consumers, small businesses, and large corporations across four core segments: U.S. Consumer Services, Commercial Services, International Card Services, and Global Merchant and Network Services. Alongside payment processing, it monetizes lifestyle, travel, dining, and corporate expense management solutions.

American Express is a dominant premium market leader rather than a mass-market volume play like Visa or Mastercard. Its primary competitive edge is its closed-loop model, allowing it to collect both merchant discount fees and recurring cardmember annual fees while controlling the customer relationship directly. That structure yields higher spend per cardholder and superior credit quality compared to traditional retail banks. The trade-off is smaller overall merchant acceptance compared to open networks and constant margin pressure from competitors chasing the same affluent demographic.

Amex is expanding steadily on the back of premium customer additions and double-digit card fee growth. Full-year 2024 revenue reached $65.95 billion, a 9% increase over 2023 following 14% growth to $60.52 billion the year before. The company acquired 13 million new cards in 2024, pushing net card fee revenue up 16% as members leaned into fee-based premium tiers. With consumer services generating 47% of revenue and commercial services bringing in another 24%, the strategy of locking in high-spend users is delivering reliable top-line expansion.

Key Financials
Market Cap
$212.88B
Revenue
$70.91B
EBITDA
N/A
Gross Margin
62.3%
Profit Margin
16.1%
Revenue Growth
12.8%
Total Cash
$45.75B
Total Debt
$59.09B
Free Cash Flow
N/A


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
19.13
Forward P/E
15.64
Beta
1.08
52-Week High
$387.49
52-Week Low
$290.97
EPS
$16.48
50-Day Avg
$321.42
200-Day Avg
$328.74
Price/Book
6.21
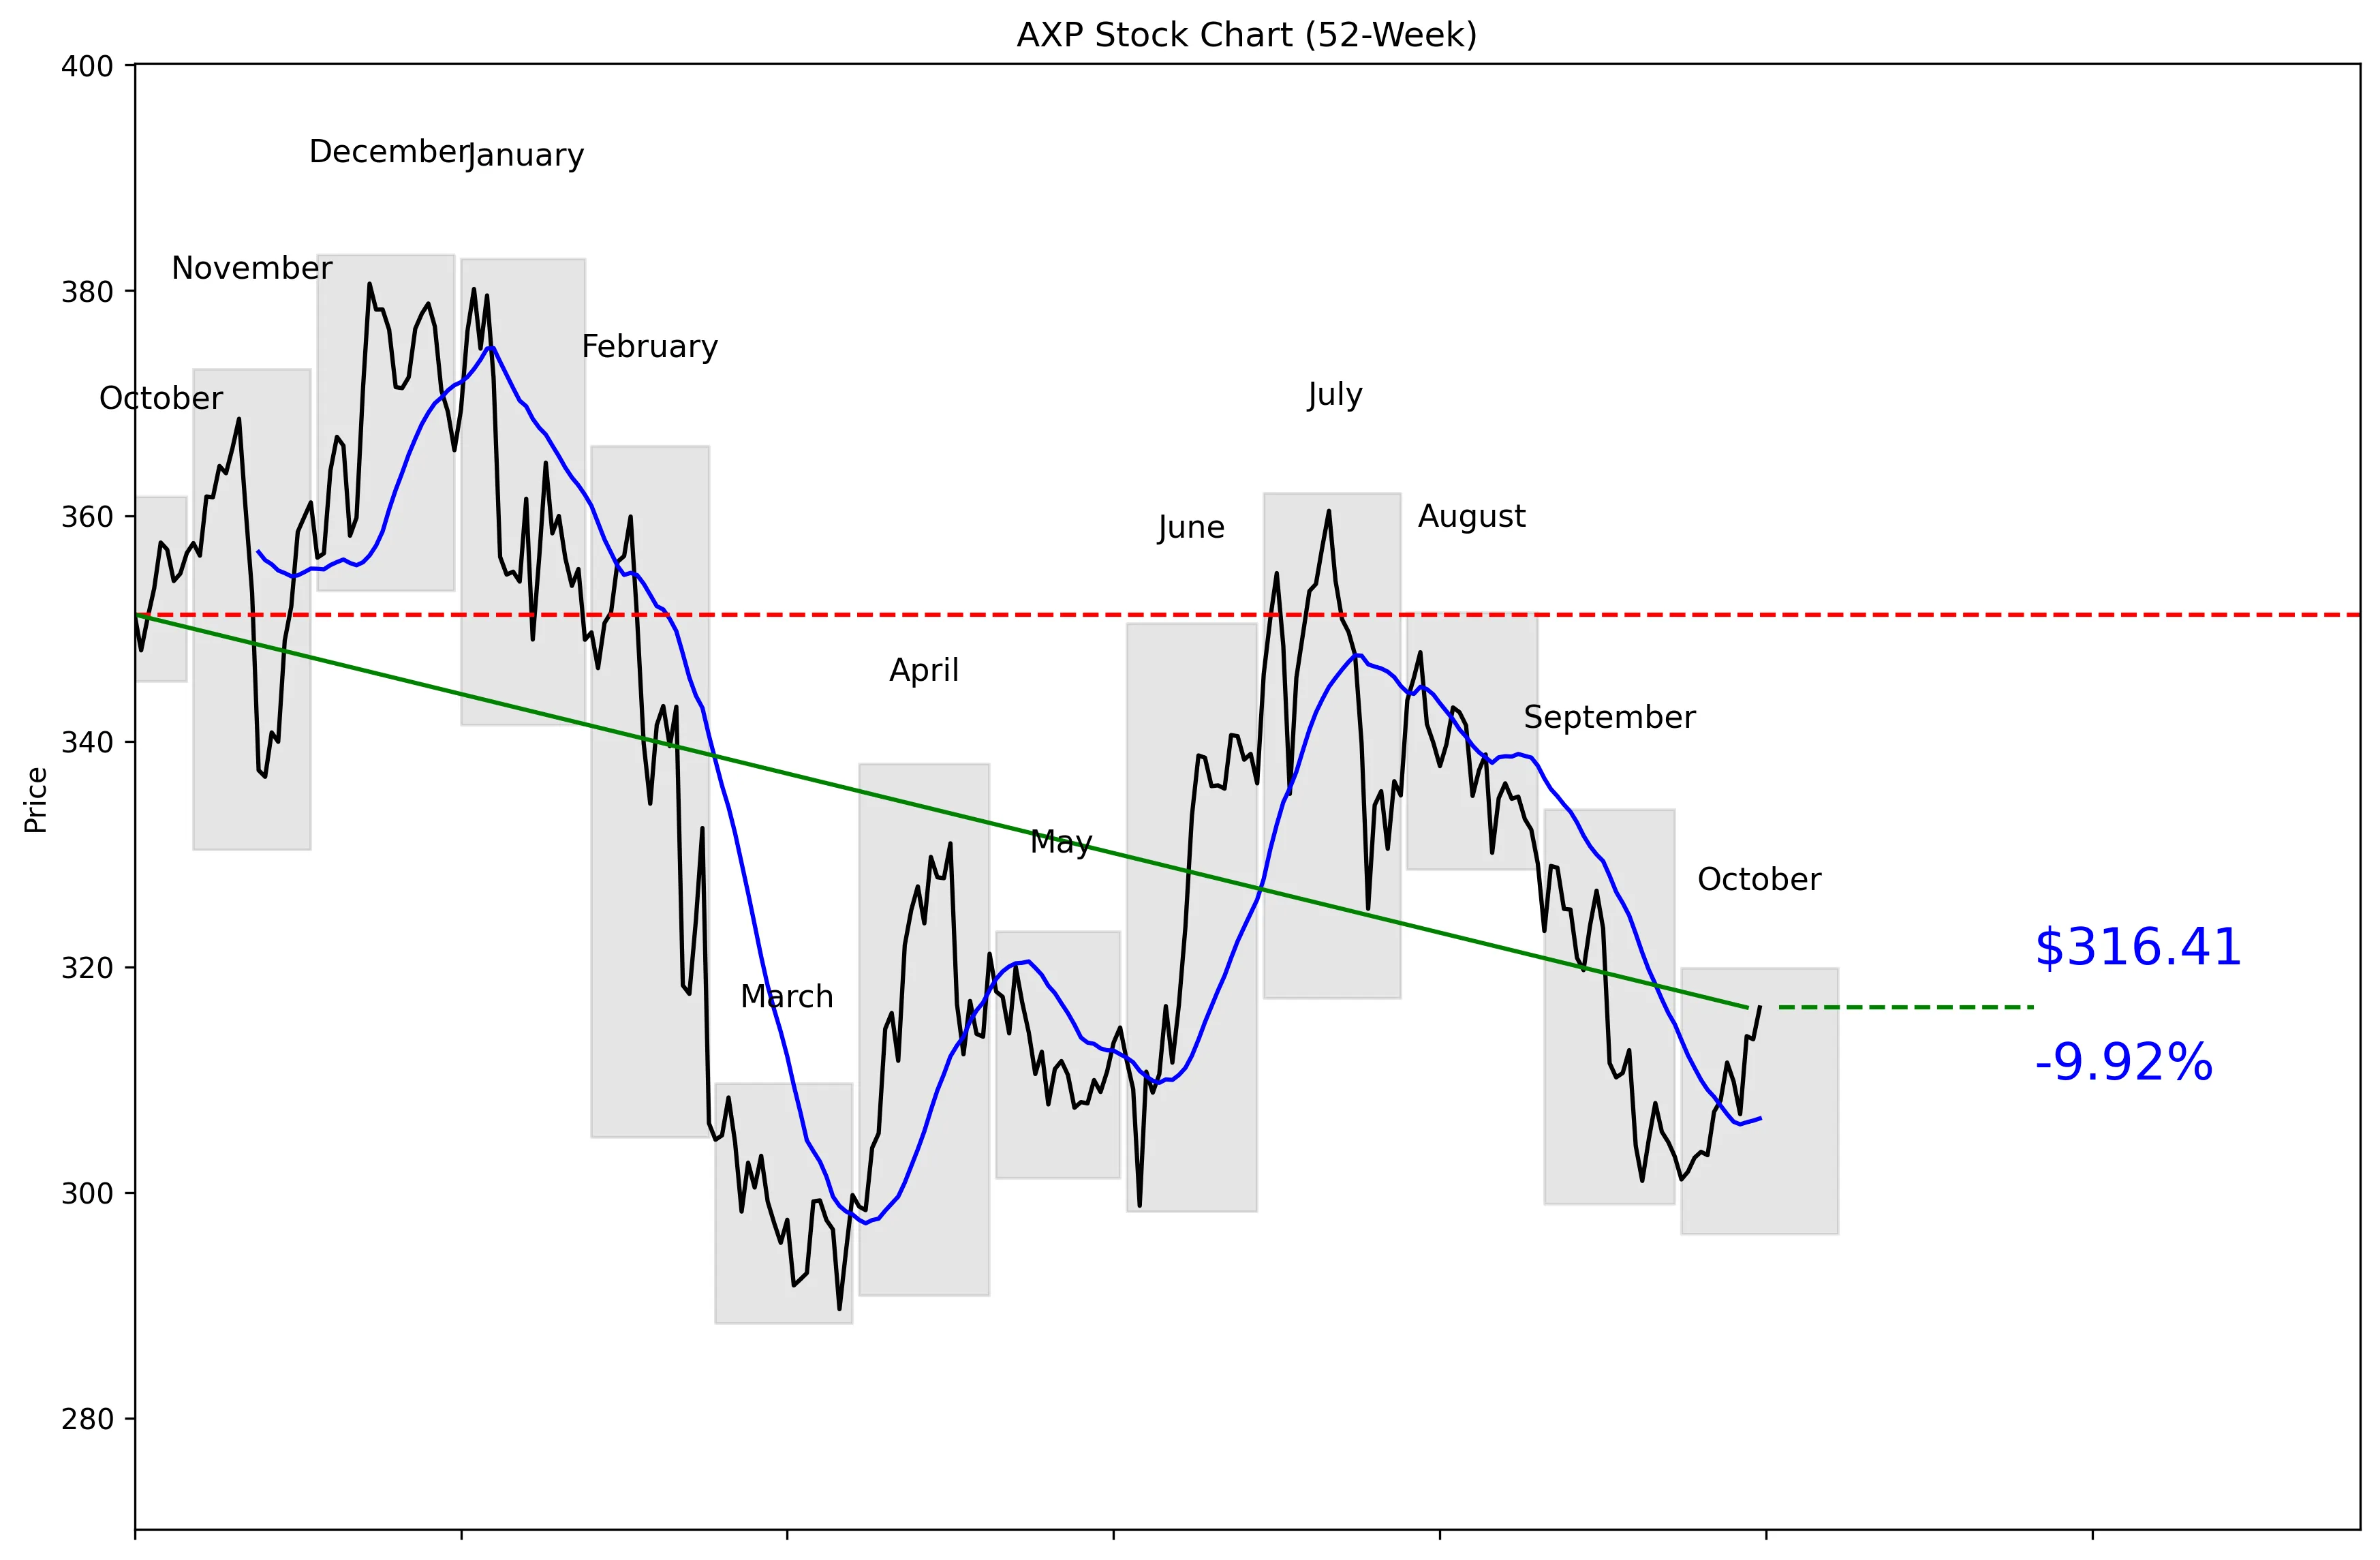
AXP 52-Week Stock Chart
Technical Analysis
AXP trades at $315.23, 30% of the way from its $288.37 52-week low to its $383.18 high. The stock is 17.42% below that high and 9.72% above the low. Price sits 3.21% above the 20-day moving average of $306.57. Momentum is positive but modest, at 1.57% over five trading days and 1.21% over 20 trading days. Near-term support is $301.03, while resistance sits at $326.77.


Recent News and Developments

Card balances rise as write-off rates improve

American Express reported $114.3 billion in U.S. consumer card balances for September, with the net write-off rate falling to 1.5% from 1.7% in August. Small-business balances reached $46.6 billion while the write-off rate improved to 2.1% from 2.2%, although both portfolios recorded a 0.1-percentage-point increase in accounts at least 30 days past due. Source: U.S. Securities and Exchange Commission

Wall Street trims AXP targets before earnings

Morgan Stanley lowered its AXP price target to $380 from $382 and maintained an Equal Weight rating. RBC Capital cut its target to $400 from $415 but kept its Outperform rating, showing reduced expectations without abandoning the bullish case. Source: TipRanks

Analysts expect higher Q3 profit despite lower revenue

American Express is scheduled to report third-quarter results on October 23. Analysts expect earnings of $4.58 per share versus $4.14 a year earlier, while projected revenue of $20.12 billion is below the prior-year figure of $20.56 billion. Source: TipRanks


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is growing 12.8%, giving American Express a solid fundamental base. U.S. consumer card balances reached $114.3 billion in September, while small-business balances hit $46.6 billion. Credit performance also improved, with consumer net write-offs falling from 1.7% to 1.5% and small-business write-offs declining from 2.2% to 2.1%. Analysts expect third-quarter earnings of $4.58 per share, up from $4.14 a year earlier. The consensus recommendation is buy across 25 analysts, with an average target of $369.44 and a high estimate of $450.00. At $315.23 and 17.42% below its 52-week high, AXP offers a credible rebound setup if earnings and credit quality hold.
Bear Case
AXP carries $59.09 billion in debt against $45.75 billion in cash, so the balance sheet is not without pressure. Its P/E of 19.13 leaves less room for disappointment if revenue growth slows or credit losses rise. Analysts expect third-quarter revenue of $20.12 billion, below the prior-year figure of $20.56 billion. Accounts at least 30 days past due increased by 0.1 percentage point in both the consumer and small-business portfolios. Morgan Stanley cut its target from $382 to $380, while RBC Capital lowered its target from $415 to $400. The stock remains below near-term resistance at $326.77, and a break under $301.03 would weaken the current technical setup.
What to Watch
The immediate catalyst is the October 23 third-quarter report. Investors should compare reported earnings with the expected $4.58 per share and revenue with the projected $20.12 billion. Consumer and small-business write-off rates need to remain near or below September’s 1.5% and 2.1%, respectively. The 0.1-percentage-point increase in accounts at least 30 days past due deserves close attention because further deterioration would challenge the credit-quality thesis. Technically, a move above $326.77 would clear near-term resistance, while a drop below $301.03 would break near-term support. The average analyst target of $369.44 remains achievable only if earnings growth, revenue growth and credit performance stay intact.
Analyst Consensus
BUY

Based on 25 analyst opinions
Low Target
$320.00
Mean Target
$369.44
High Target
$450.00


Earnings and Financial Data

Sector
Financial Services
Industry
Credit Services
Employees
76,800
Earnings & Dividends
Next Earnings
Oct 23, 2026
EPS (Trailing)
$16.48
Dividend Yield
121.0%
Payout Ratio
21.5%

Frequently Asked Questions

Is AXP a good stock to buy?
The consensus recommendation is buy based on 25 analysts, and revenue growth is 12.8%. The takeaway is that analysts favor AXP, but the stock still needs to hold its fundamental growth.
What is AXP’s price target?
The average analyst target is $369.44, with estimates ranging from $320.00 to $450.00. The takeaway is that Wall Street’s expected outcomes vary widely.
What is AXP’s current valuation?
AXP trades at $315.23 with a market capitalization of $212.88 billion and a P/E ratio of 19.13. The takeaway is that investors are paying 19.13 times earnings for the stock.
What are AXP’s support and resistance levels?
Near-term support is $301.03, and near-term resistance is $326.77. The takeaway is that these are the key technical levels around the current $315.23 price.
Does AXP pay a dividend?
The provided data does not include dividend information. The takeaway is that no dividend conclusion can be made from these figures.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 20, 2026.