ALTSTATION.IO

Martin Marietta Materials, Inc. (MLM) Stock Analysis

By Nova Skye | AltStation.io | Updated October 18, 2026

Price
$496.91
Change
+1.16%
Market Cap
$35.29B
Avg Volume
715.8K

Company Overview

Martin Marietta Materials, Inc. is a major supplier of heavy construction aggregates headquartered in Raleigh, North Carolina, operating in the Basic Materials sector within the Building Materials industry. Founded in 1939, the company processes and distributes crushed stone, sand, and gravel, alongside ready mixed concrete, asphalt, and paving services across its East Group and West Group segments. It also manufactures specialized magnesia-based chemical products and dolomitic lime used for steel production, soil stabilization, and wastewater treatment. Its core customer base spans public infrastructure projects, commercial and residential construction contractors, railroads, agriculture, and utilities.

Martin Marietta sits as an entrenched market leader in the United States aggregates industry, competing head-to-head with Vulcan Materials Company and CRH. Its primary economic moat is geographic: heavy stone and gravel are costly to haul over long distances, giving local quarry operators substantial regional pricing power. Strict zoning and permitting barriers make opening competing quarries near major metropolitan areas nearly impossible, shielding incumbents from new entrants. While exposure to commercial and residential building cycles creates volume risk, ongoing infrastructure demand provides a steady baseline of demand.

The company is currently executing a strategic shift toward a pure aggregates model, prioritizing high-margin quarry operations over lower-margin downstream businesses. This capital allocation strategy is paying off, with MLM generating $6.15 billion in revenue in 2025 and management raising full-year 2026 revenue guidance to between $7.2 billion and $7.4 billion. Rather than chasing commoditized volume, the company relies on pricing discipline and federal infrastructure tailwinds to protect margins. This tighter focus on quarry assets positions MLM for resilient cash flow generation even through uneven macroeconomic conditions.

Key Financials
Market Cap
$35.29B
Revenue
$6.69B
EBITDA
$2.13B
Gross Margin
28.2%
Profit Margin
36.7%
Revenue Growth
21.0%
Total Cash
$112.00M
Total Debt
$6.34B
Free Cash Flow
$593.37M


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
32.23
Forward P/E
22.69
Beta
1.08
52-Week High
$710.97
52-Week Low
$464.92
EPS
$15.42
50-Day Avg
$508.24
200-Day Avg
$582.56
Price/Book
2.58
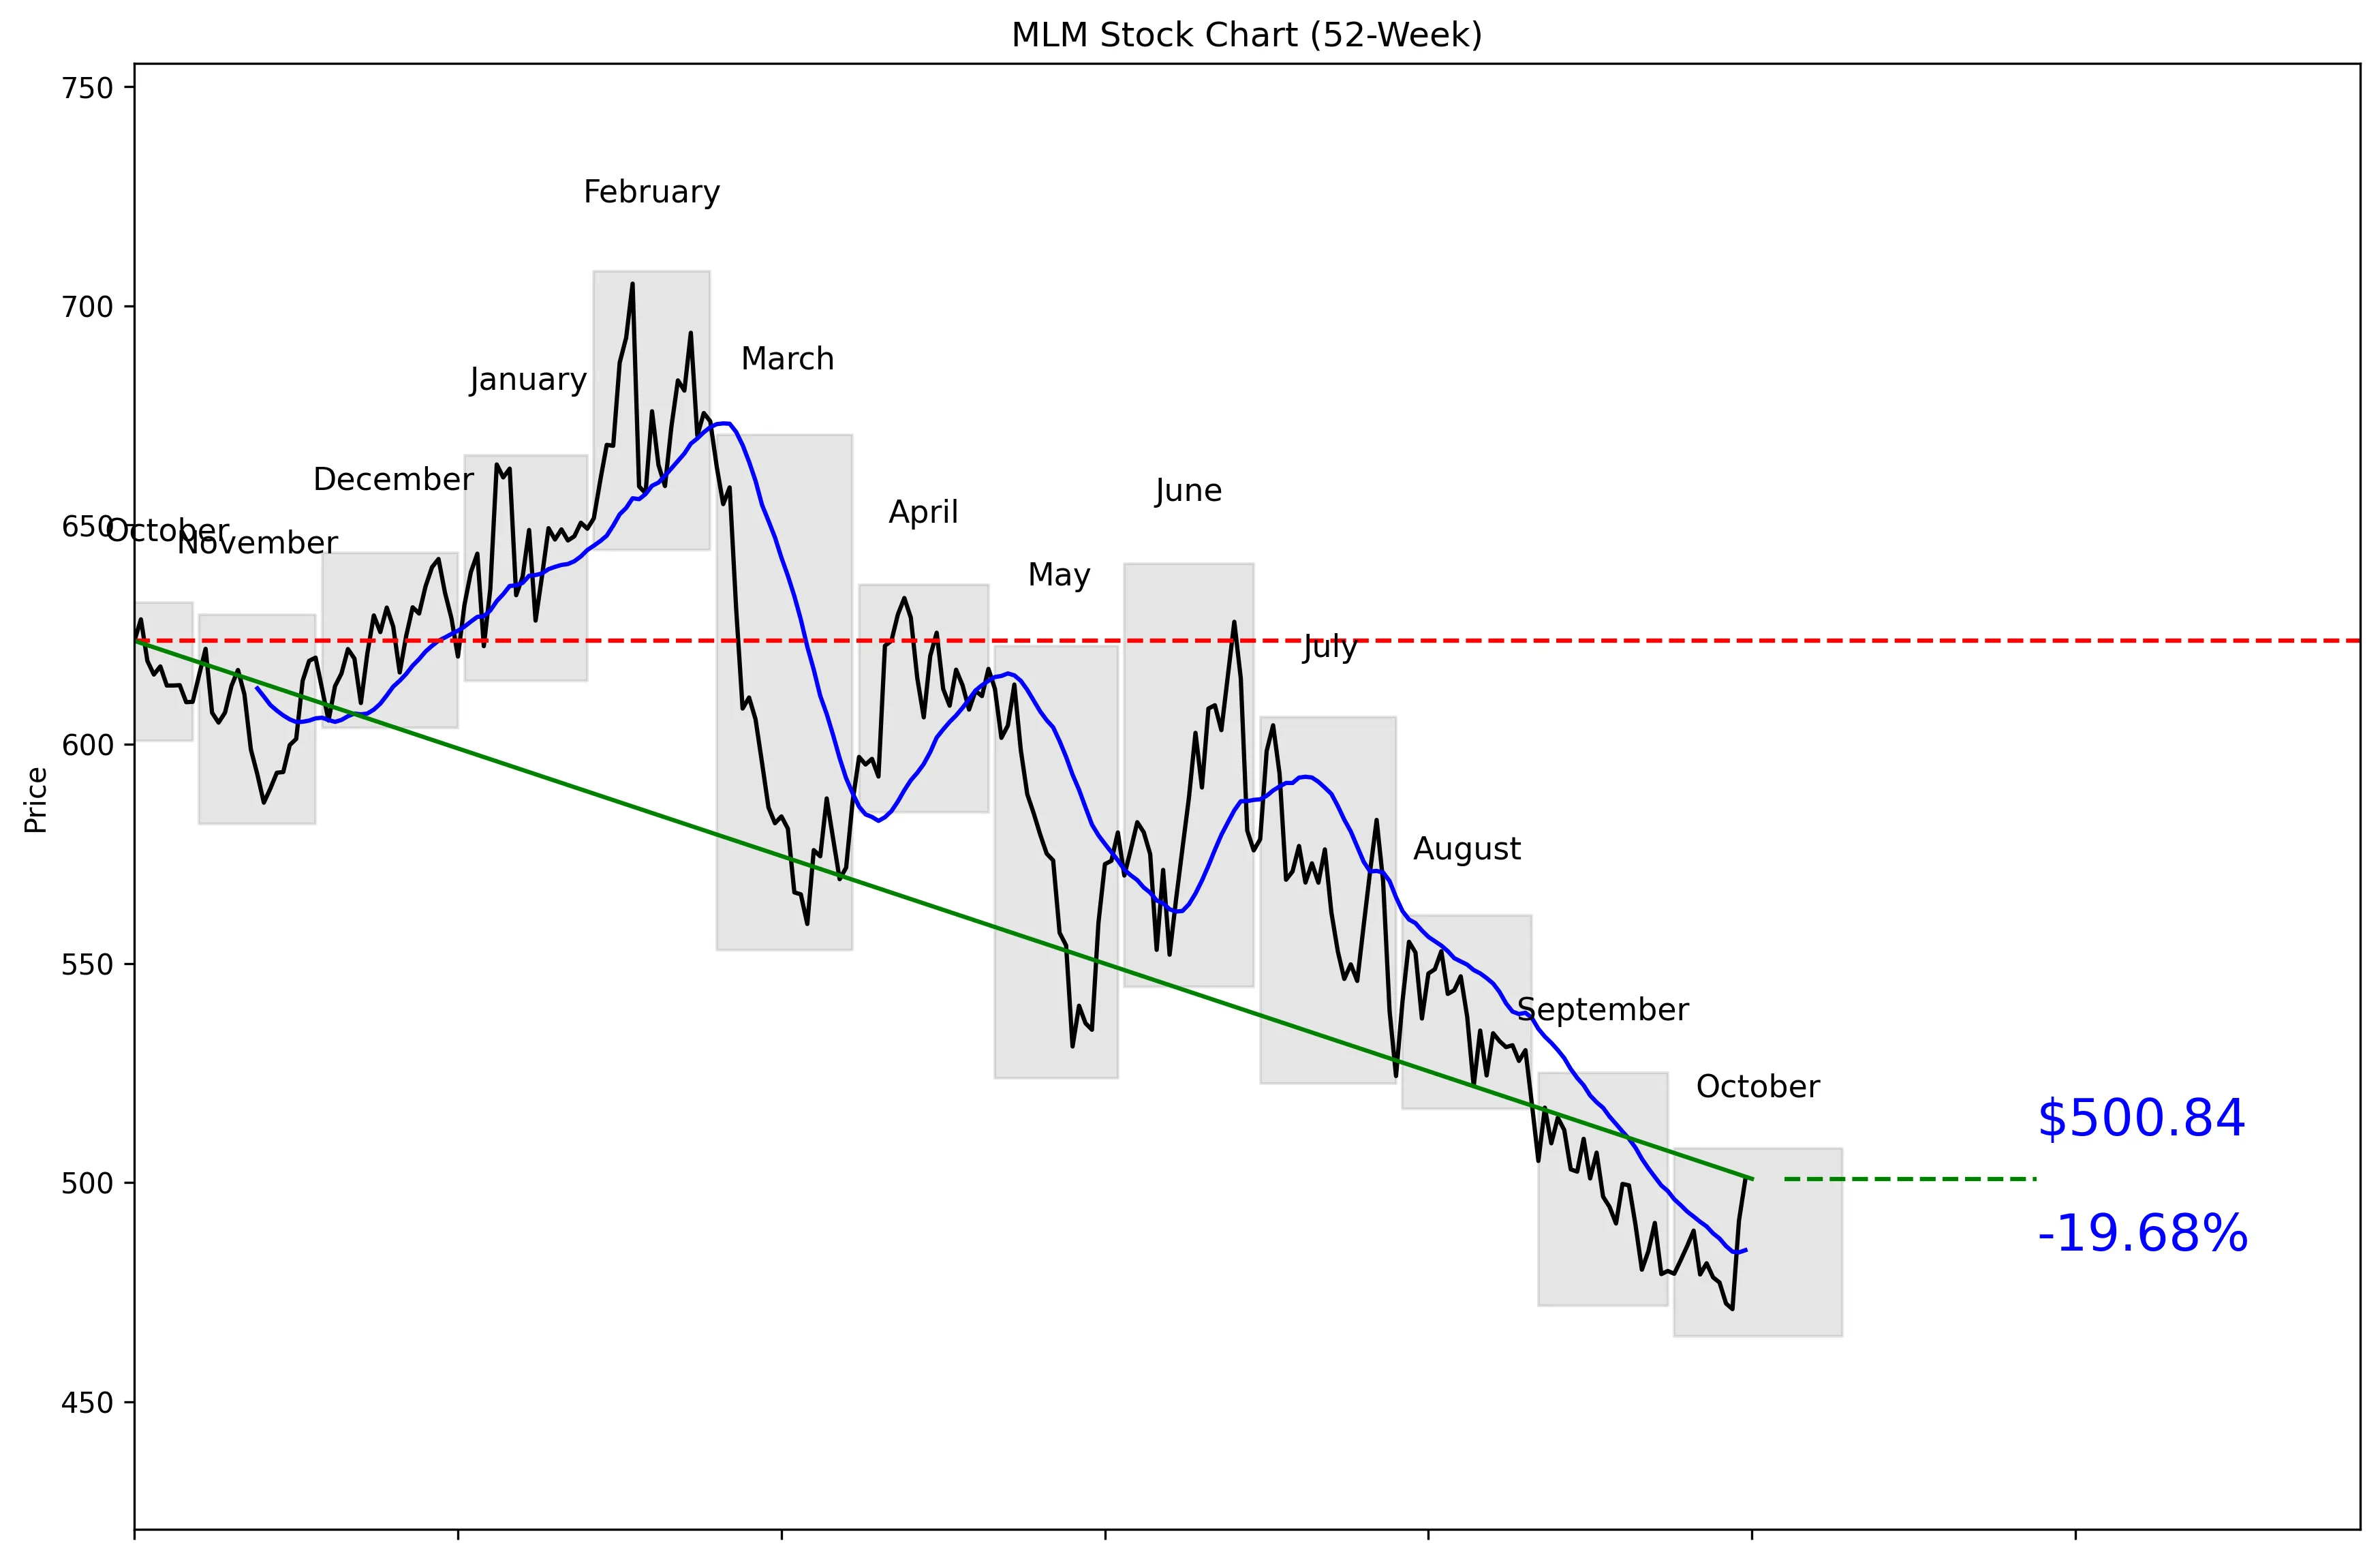
MLM 52-Week Stock Chart
Technical Analysis
MLM trades at $496.91, just 15% of the way from its 52-week low of $464.92 to its 52-week high of $707.94. The stock remains 29.25% below that high but has recovered 7.73% from the low. Price is 3.36% above the 20-day moving average of $484.56, while momentum is positive at 4.70% over five trading days and 2.08% over 20 trading days. Near-term support sits at the 30-day low of $471.10. The first resistance level is the 30-day high of $514.77.


Recent News and Developments

DA Davidson upgrades MLM to Buy

DA Davidson upgraded Martin Marietta from Neutral to Buy and set a $610 price target. The firm called the stock’s 20.8% year-to-date decline overdone and sees an attractive entry before third-quarter earnings. Source: Investing.com

Raymond James cuts MLM target to $640

Raymond James lowered its Martin Marietta price target from $660 to $640 while keeping an Outperform rating. MLM closed at $500.84 on October 16, up 1.96%, leaving the revised target 27.78% above the share price. Source: AD HOC NEWS

JPMorgan trims MLM target before earnings

JPMorgan cut its Martin Marietta price target from $680 to $650 but kept its Overweight rating. The firm expects construction-materials companies to reduce fiscal 2026 guidance as higher diesel costs, weak pricing and subdued demand pressure margins. Source: TipRanks


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is growing 21.0%, giving investors a concrete reason to consider buying the pullback. MLM generates $6.69 billion in revenue and carries a $35.29 billion market capitalization. The stock trades at $496.91, well below the $633.92 consensus analyst target. All 24 analysts behind the listed recommendation collectively rate MLM a buy, with targets ranging from $496.00 to $800.00. DA Davidson upgraded the stock to Buy with a $610 target after calling the 20.8% year-to-date decline overdone. Raymond James and JPMorgan remain positive despite lowering their targets to $640 and $650, respectively. The bull case is straightforward: strong revenue growth, positive analyst sentiment and a share price sitting near the bottom of its annual range create a credible recovery setup.
Bear Case
MLM is not obviously cheap at 32.23 times earnings, even after falling 29.25% from its 52-week high. The balance sheet carries $6.34 billion in total debt against only $112.00 million in cash. That debt load reduces the room for error if operating conditions weaken. JPMorgan expects construction-materials companies to reduce fiscal 2026 guidance because of higher diesel costs, weak pricing and subdued demand. Those pressures could squeeze margins and make the current valuation harder to defend. Raymond James cut its target from $660 to $640, while JPMorgan reduced its target from $680 to $650, showing that bullish analysts are becoming less aggressive. A break below $471.10 would put the recent $464.92 low back into focus and weaken the rebound thesis.
What to Watch
Third-quarter earnings are the next stated catalyst, although the supplied news does not provide an earnings date. Revenue growth needs to remain strong relative to the current 21.0% rate to support a P/E of 32.23. Investors should watch management’s fiscal 2026 guidance for evidence of the higher diesel costs, weak pricing and subdued demand flagged by JPMorgan. On the chart, $514.77 is the immediate resistance level; clearing it would strengthen the rebound. The 20-day moving average at $484.56 is the first trend checkpoint, followed by support at $471.10 and the 52-week low at $464.92. Investors should also track whether analysts continue cutting targets from the current $633.92 consensus. The thesis improves with sustained growth and a move above $514.77, but deteriorates if guidance falls and the stock breaks $471.10.
Analyst Consensus
BUY

Based on 24 analyst opinions
Low Target
$496.00
Mean Target
$633.92
High Target
$800.00


Earnings and Financial Data

Sector
Basic Materials
Industry
Building Materials
Employees
9,600
Earnings & Dividends
Next Earnings
Nov 03, 2026
EPS (Trailing)
$15.42
Dividend Yield
68.0%
Payout Ratio
21.6%

Frequently Asked Questions

Is MLM a good stock to buy?
MLM has a buy recommendation from 24 analysts, 21.0% revenue growth and a $633.92 consensus target versus a $496.91 share price. The clear takeaway is that the supplied data supports a bullish view, but the 32.23 P/E and $6.34 billion debt load raise the risk.
What is MLM’s price target?
The consensus analyst target is $633.92, with individual targets ranging from $496.00 to $800.00. The takeaway is that analysts see upside overall, although the bottom of the range is slightly below the current $496.91 price.
Is MLM stock undervalued?
MLM trades 29.25% below its 52-week high and only 7.73% above its 52-week low, but its P/E is 32.23. The takeaway is that the stock is depressed relative to its yearly range, but the earnings valuation is not cheap.
What are MLM’s support and resistance levels?
Near-term support is $471.10, while near-term resistance is $514.77. The takeaway is that these are the key levels for judging whether the rebound continues or fails.
Does MLM pay a dividend?
The supplied key and technical data do not include dividend information. The takeaway is that no dividend conclusion can be made from the available data.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 18, 2026.