ALTSTATION.IO

Freeport-McMoRan Inc. (FCX) Stock Analysis

By Nova Skye | AltStation.io | Updated October 19, 2026

Price
$69.59
Change
-0.67%
Market Cap
$99.93B
Avg Volume
13.0M

Company Overview

Headquartered in Phoenix, Arizona, Freeport-McMoRan Inc. operates in the basic materials sector as one of the premier copper producers in the world. The company mines and sells copper alongside valuable by-products like gold, molybdenum, and silver from major open-pit and underground operations across North America, South America, and Indonesia. Its primary customers are global smelters, refiners, and industrial manufacturers that process raw concentrate and cathode into wiring and components for power grids, electronics, and construction. Across its portfolio, which includes Arizona hubs like Morenci and Peru’s Cerro Verde, Freeport generated $25.91 billion in revenue for 2025.

Freeport is a clear market leader, producing roughly 70% of all copper mined in the United States and accounting for approximately 7% of total global mined output. Its core advantage stems from tier-one assets like the Grasberg minerals district in Indonesia, where massive gold and molybdenum by-products generate substantial cash credits that sharply reduce net copper production costs. The trade-off is operational and geopolitical risk, giving diversified competitors like BHP, Rio Tinto, and Southern Copper a broader safety cushion against regional mine disruptions. Even with single-asset vulnerabilities, Freeport holds the strongest pure-play copper footprint among the majors.

Right now, Freeport is managing an operational turnaround while scaling low-cost domestic extraction technology. The company is executing a phased production recovery at its Grasberg mine following a late 2025 operational disruption, moving from roughly 50% capacity in mid-2026 toward 65% in the second half of the year. In the United States, its innovative leaching initiative reached an annual run rate of 240 million pounds of copper in late 2025, with management targeting 300 million pounds in 2026 from existing stockpiles. With trailing twelve-month revenue sitting at $26.42 billion, Freeport is prioritizing disciplined organic volume growth over splashy acquisitions while global demand from electrification and data centers keeps market supply tight.

Key Financials
Market Cap
$99.93B
Revenue
$25.87B
EBITDA
$9.55B
Gross Margin
38.3%
Profit Margin
11.4%
Revenue Growth
-7.3%
Total Cash
$4.08B
Total Debt
$10.36B
Free Cash Flow
$2.16B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
34.28
Forward P/E
16.08
Beta
1.39
52-Week High
$80.24
52-Week Low
$38.54
EPS
$2.03
50-Day Avg
$72.01
200-Day Avg
$64.59
Price/Book
4.97
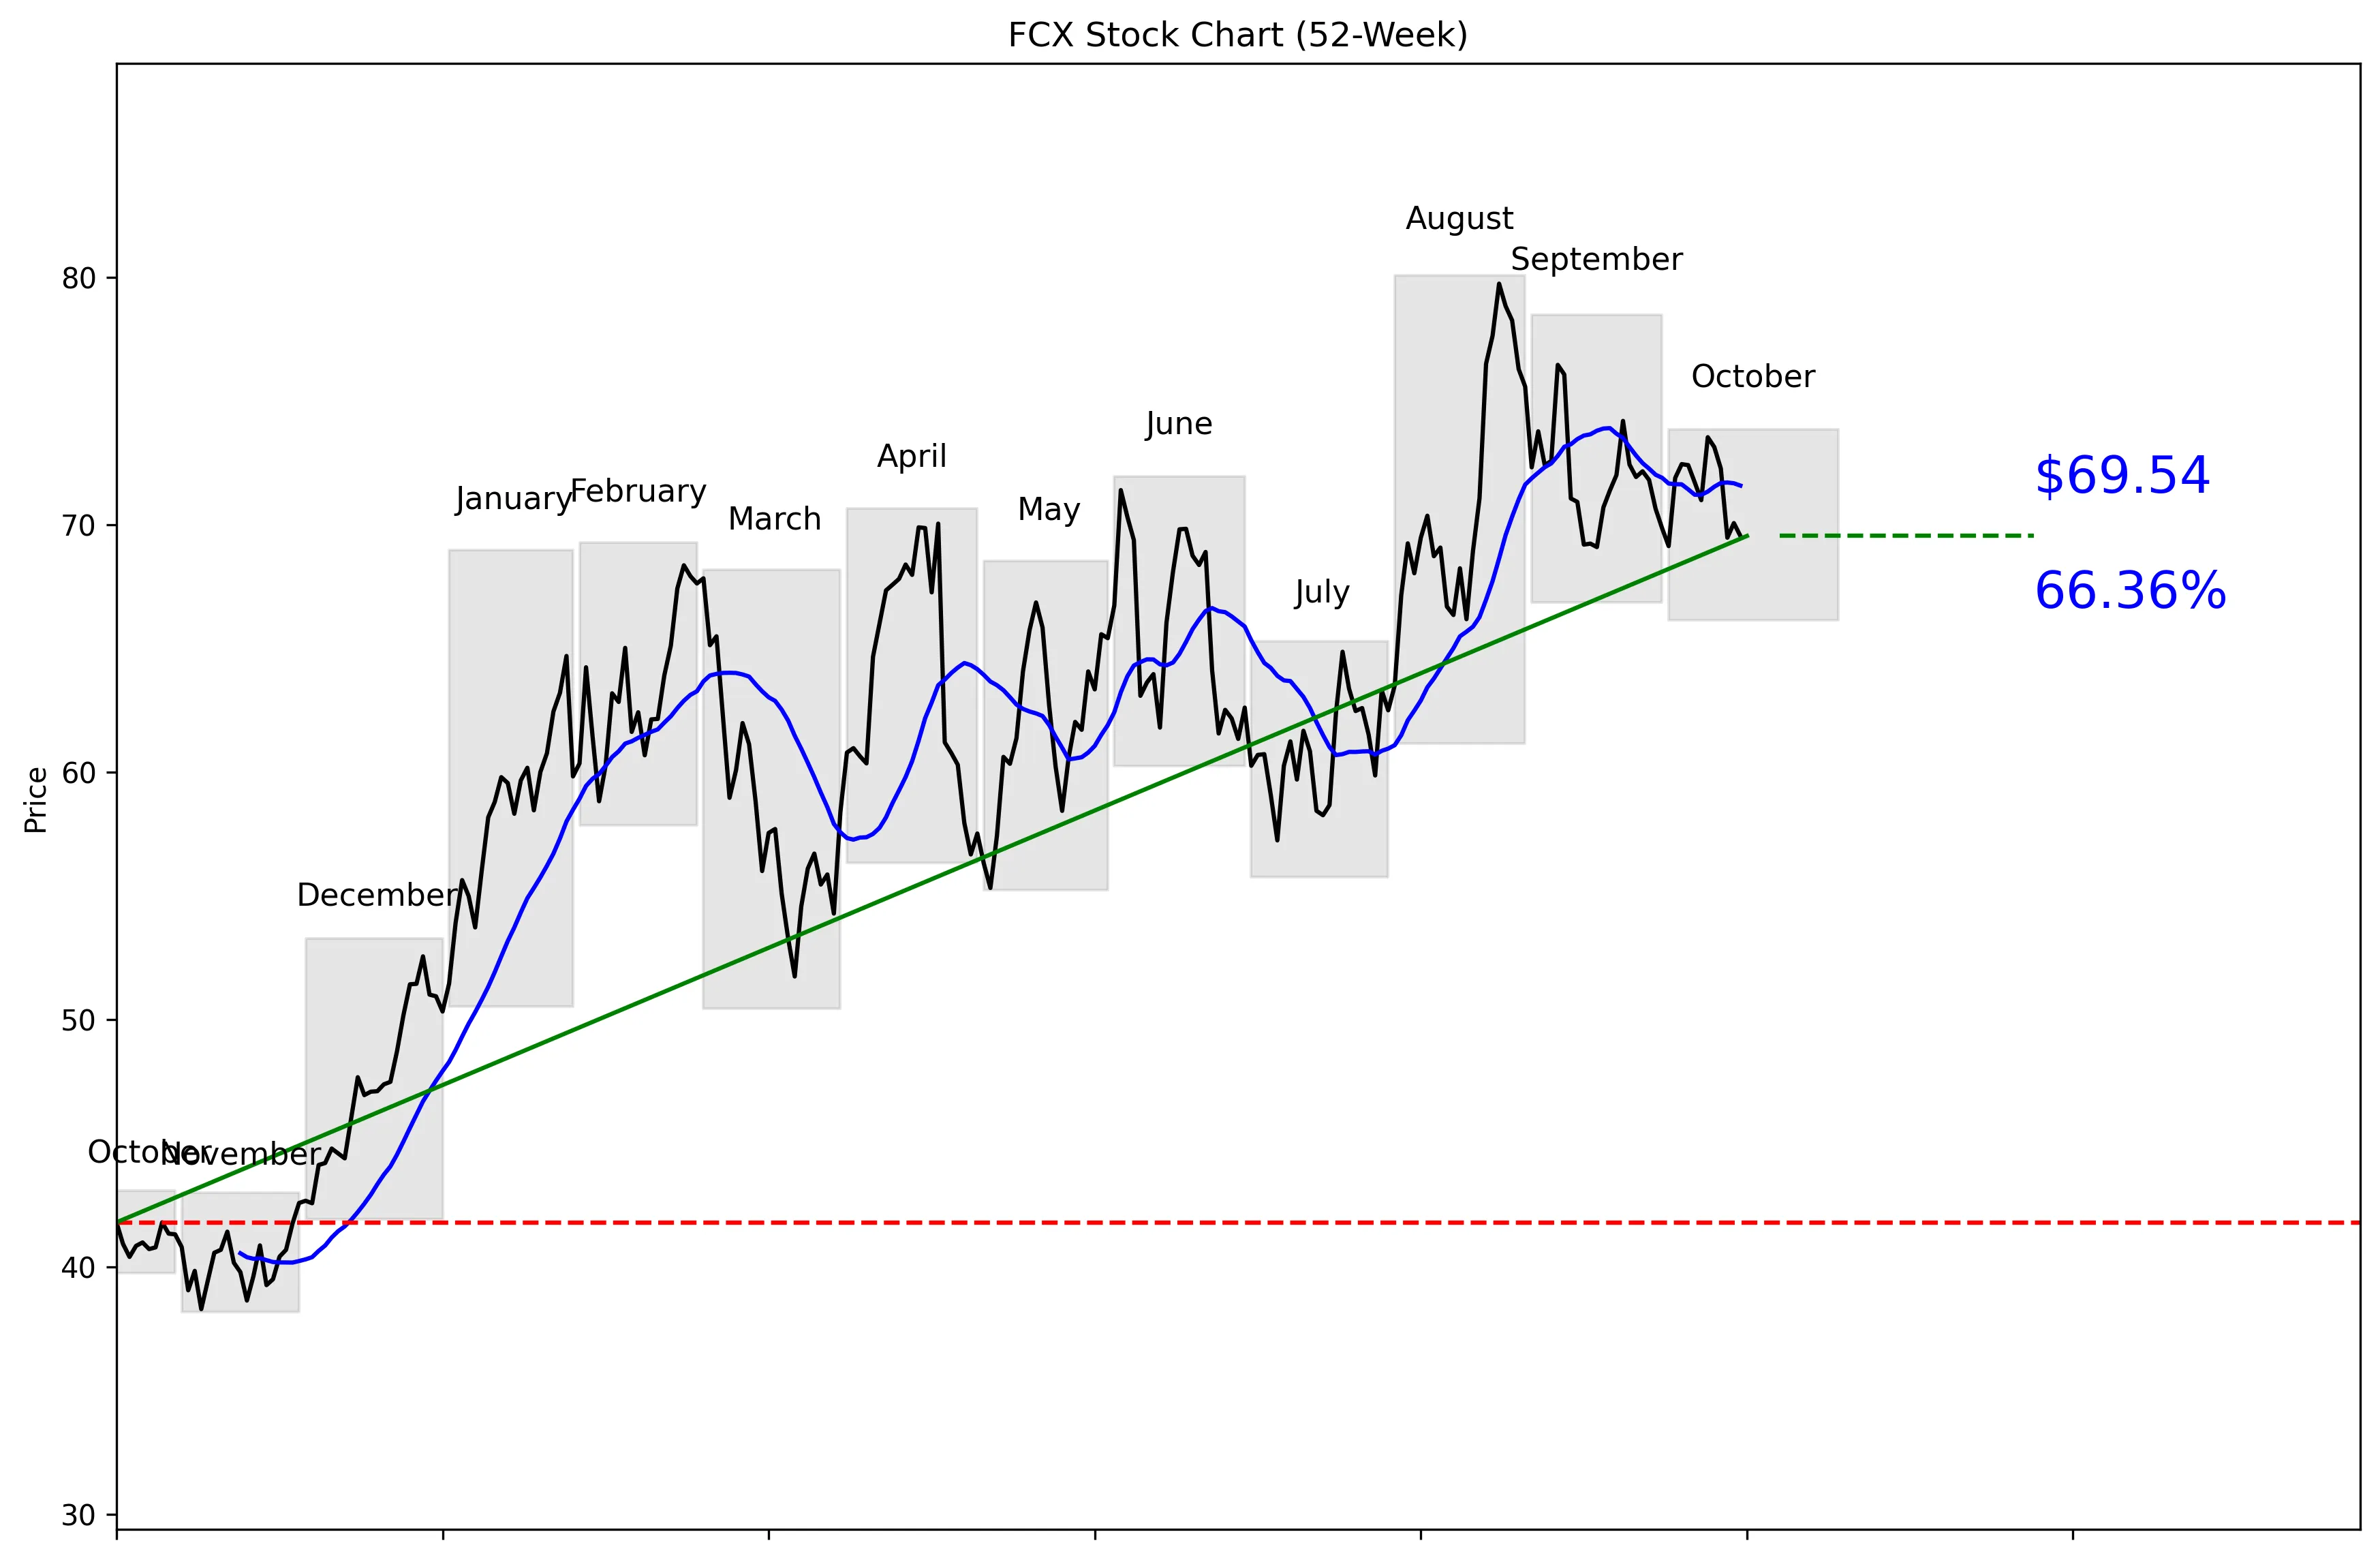
FCX 52-Week Stock Chart
Technical Analysis
FCX trades at $69.59, 75% of the way from its $38.18 52-week low to its $80.07 high. The stock remains 13.15% below that high but stands 82.12% above the low. Price is 2.85% below the 20-day moving average of $71.58. Momentum is negative, with declines of 5.43% over five trading days and 2.59% over 20 trading days. Near-term support is $69.09, while resistance sits at $76.45.


Recent News and Developments

Bernstein lifts FCX target but stays cautious

Bernstein SocGen maintained its Hold rating on October 16 and raised its FCX price target from $47.00 to $54.50. The new target was still 21.63% below the share price shown by the source, making this a bearish valuation call despite the increase. Source: Investing.com

FCX drops 3.89% in one session

Freeport-McMoRan closed at $69.60 on October 14, down 3.89%. That was materially worse than the S&P 500’s 1.11% decline and the Nasdaq’s 1.88% drop. Source: Zacks Equity Research

FCX shareholders lock in $0.15 dividend

October 15 was the record date for Freeport-McMoRan’s combined $0.15-per-share quarterly dividend. The payout consists of a $0.075 base dividend and a $0.075 variable dividend, both scheduled for November 2. Source: Freeport-McMoRan


Market Sentiment and Analyst Recommendations

Bull Case
FCX has a $99.93 billion market cap and generates $25.87 billion in revenue. The analyst consensus is buy across 22 analysts, with a target of $78.73. The top of the analyst range reaches $92.00, showing that some analysts see substantial upside from $69.59. The stock is still 13.15% below its 52-week high, leaving room for recovery if momentum improves. Shareholders on record October 15 secured a combined quarterly dividend of $0.15 per share, scheduled for November 2. The bull case is straightforward: hold the $69.09 support level, reclaim the $71.58 moving average, and the stock has a credible path back toward $76.45 and the analyst target.
Bear Case
The P/E ratio of 34.28 is demanding for a company with revenue growth of negative 7.3%. Total debt of $10.36 billion also stands well above total cash of $4.08 billion. Near-term price action is weak, with FCX down 5.43% over five trading days and 2.59% over 20 trading days. The stock is below its $71.58 moving average and sits only $0.50 above near-term support at $69.09. On October 14, FCX dropped 3.89%, compared with declines of 1.11% for the S&P 500 and 1.88% for the Nasdaq. Bernstein SocGen raised its target from $47.00 to $54.50 on October 16 but kept a Hold rating, and that target remained 21.63% below the source’s share price.
What to Watch
The first test is whether FCX can hold the $69.09 near-term support level. A recovery above the $71.58 20-day moving average would show that the recent 5.43% five-day decline is losing force. The next technical hurdle is $76.45, the 30-day high and stated near-term resistance. Investors should also compare the current $69.59 price with the $78.73 analyst target and the much wider target range of $32.00 to $92.00. The combined $0.15-per-share quarterly dividend is scheduled for November 2 after the October 15 record date. Fundamentally, the key question is whether revenue growth improves from negative 7.3%, because a 34.28 P/E leaves little room for continued contraction.
Analyst Consensus
BUY

Based on 22 analyst opinions
Low Target
$32.00
Mean Target
$78.73
High Target
$92.00


Earnings and Financial Data

Sector
Basic Materials
Industry
Copper
Employees
29,000
Earnings & Dividends
Next Earnings
Oct 27, 2026
EPS (Trailing)
$2.03
Dividend Yield
86.0%
Payout Ratio
29.6%

Frequently Asked Questions

Is FCX a good stock to buy?
The recommendation is buy based on 22 analysts, but FCX trades at a P/E of 34.28 while revenue growth is negative 7.3%. The takeaway is that analysts are positive, but the valuation requires stronger growth.
What is FCX’s analyst price target?
The analyst target is $78.73, with estimates ranging from $32.00 to $92.00. The takeaway is that the consensus sits above the current $69.59 price, but analyst expectations vary widely.
What are FCX’s support and resistance levels?
Near-term support is $69.09, and near-term resistance is $76.45. The takeaway is that FCX is trading close to support at its current price of $69.59.
Is FCX near its 52-week high?
FCX is 13.15% below its technical 52-week high of $80.07 and sits 75% of the way from its $38.18 low to that high. The takeaway is that the stock is in the upper part of its annual range but remains below the peak.
How strong is FCX’s balance sheet?
FCX has $4.08 billion in total cash and $10.36 billion in total debt. The takeaway is that debt is substantially higher than cash.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 19, 2026.