ALTSTATION.IO

Vulcan Materials Company (VMC) Stock Analysis

By Nova Skye | AltStation.io | Updated October 24, 2026

Price
$263.37
Change
-1.99%
Market Cap
$34.13B
Avg Volume
1.1M

Company Overview

Vulcan Materials Company produces and supplies construction aggregates in the United States. It operates through three segments: Aggregates, Asphalt, and Concrete. The company provides crushed stone, sand and gravel, sand, and other aggregates for use in construction and maintenance of highways, str

Key Financials
Market Cap
$34.13B
Revenue
$8.12B
EBITDA
$2.34B
Gross Margin
27.5%
Profit Margin
13.7%
Revenue Growth
2.5%
Total Cash
$194.20M
Total Debt
$4.94B
Free Cash Flow
$843.60M


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
31.06
Forward P/E
25.26
Beta
1.05
52-Week High
$331.09
52-Week Low
$237.03
EPS
$8.48
50-Day Avg
$256.60
200-Day Avg
$281.25
Price/Book
4.03
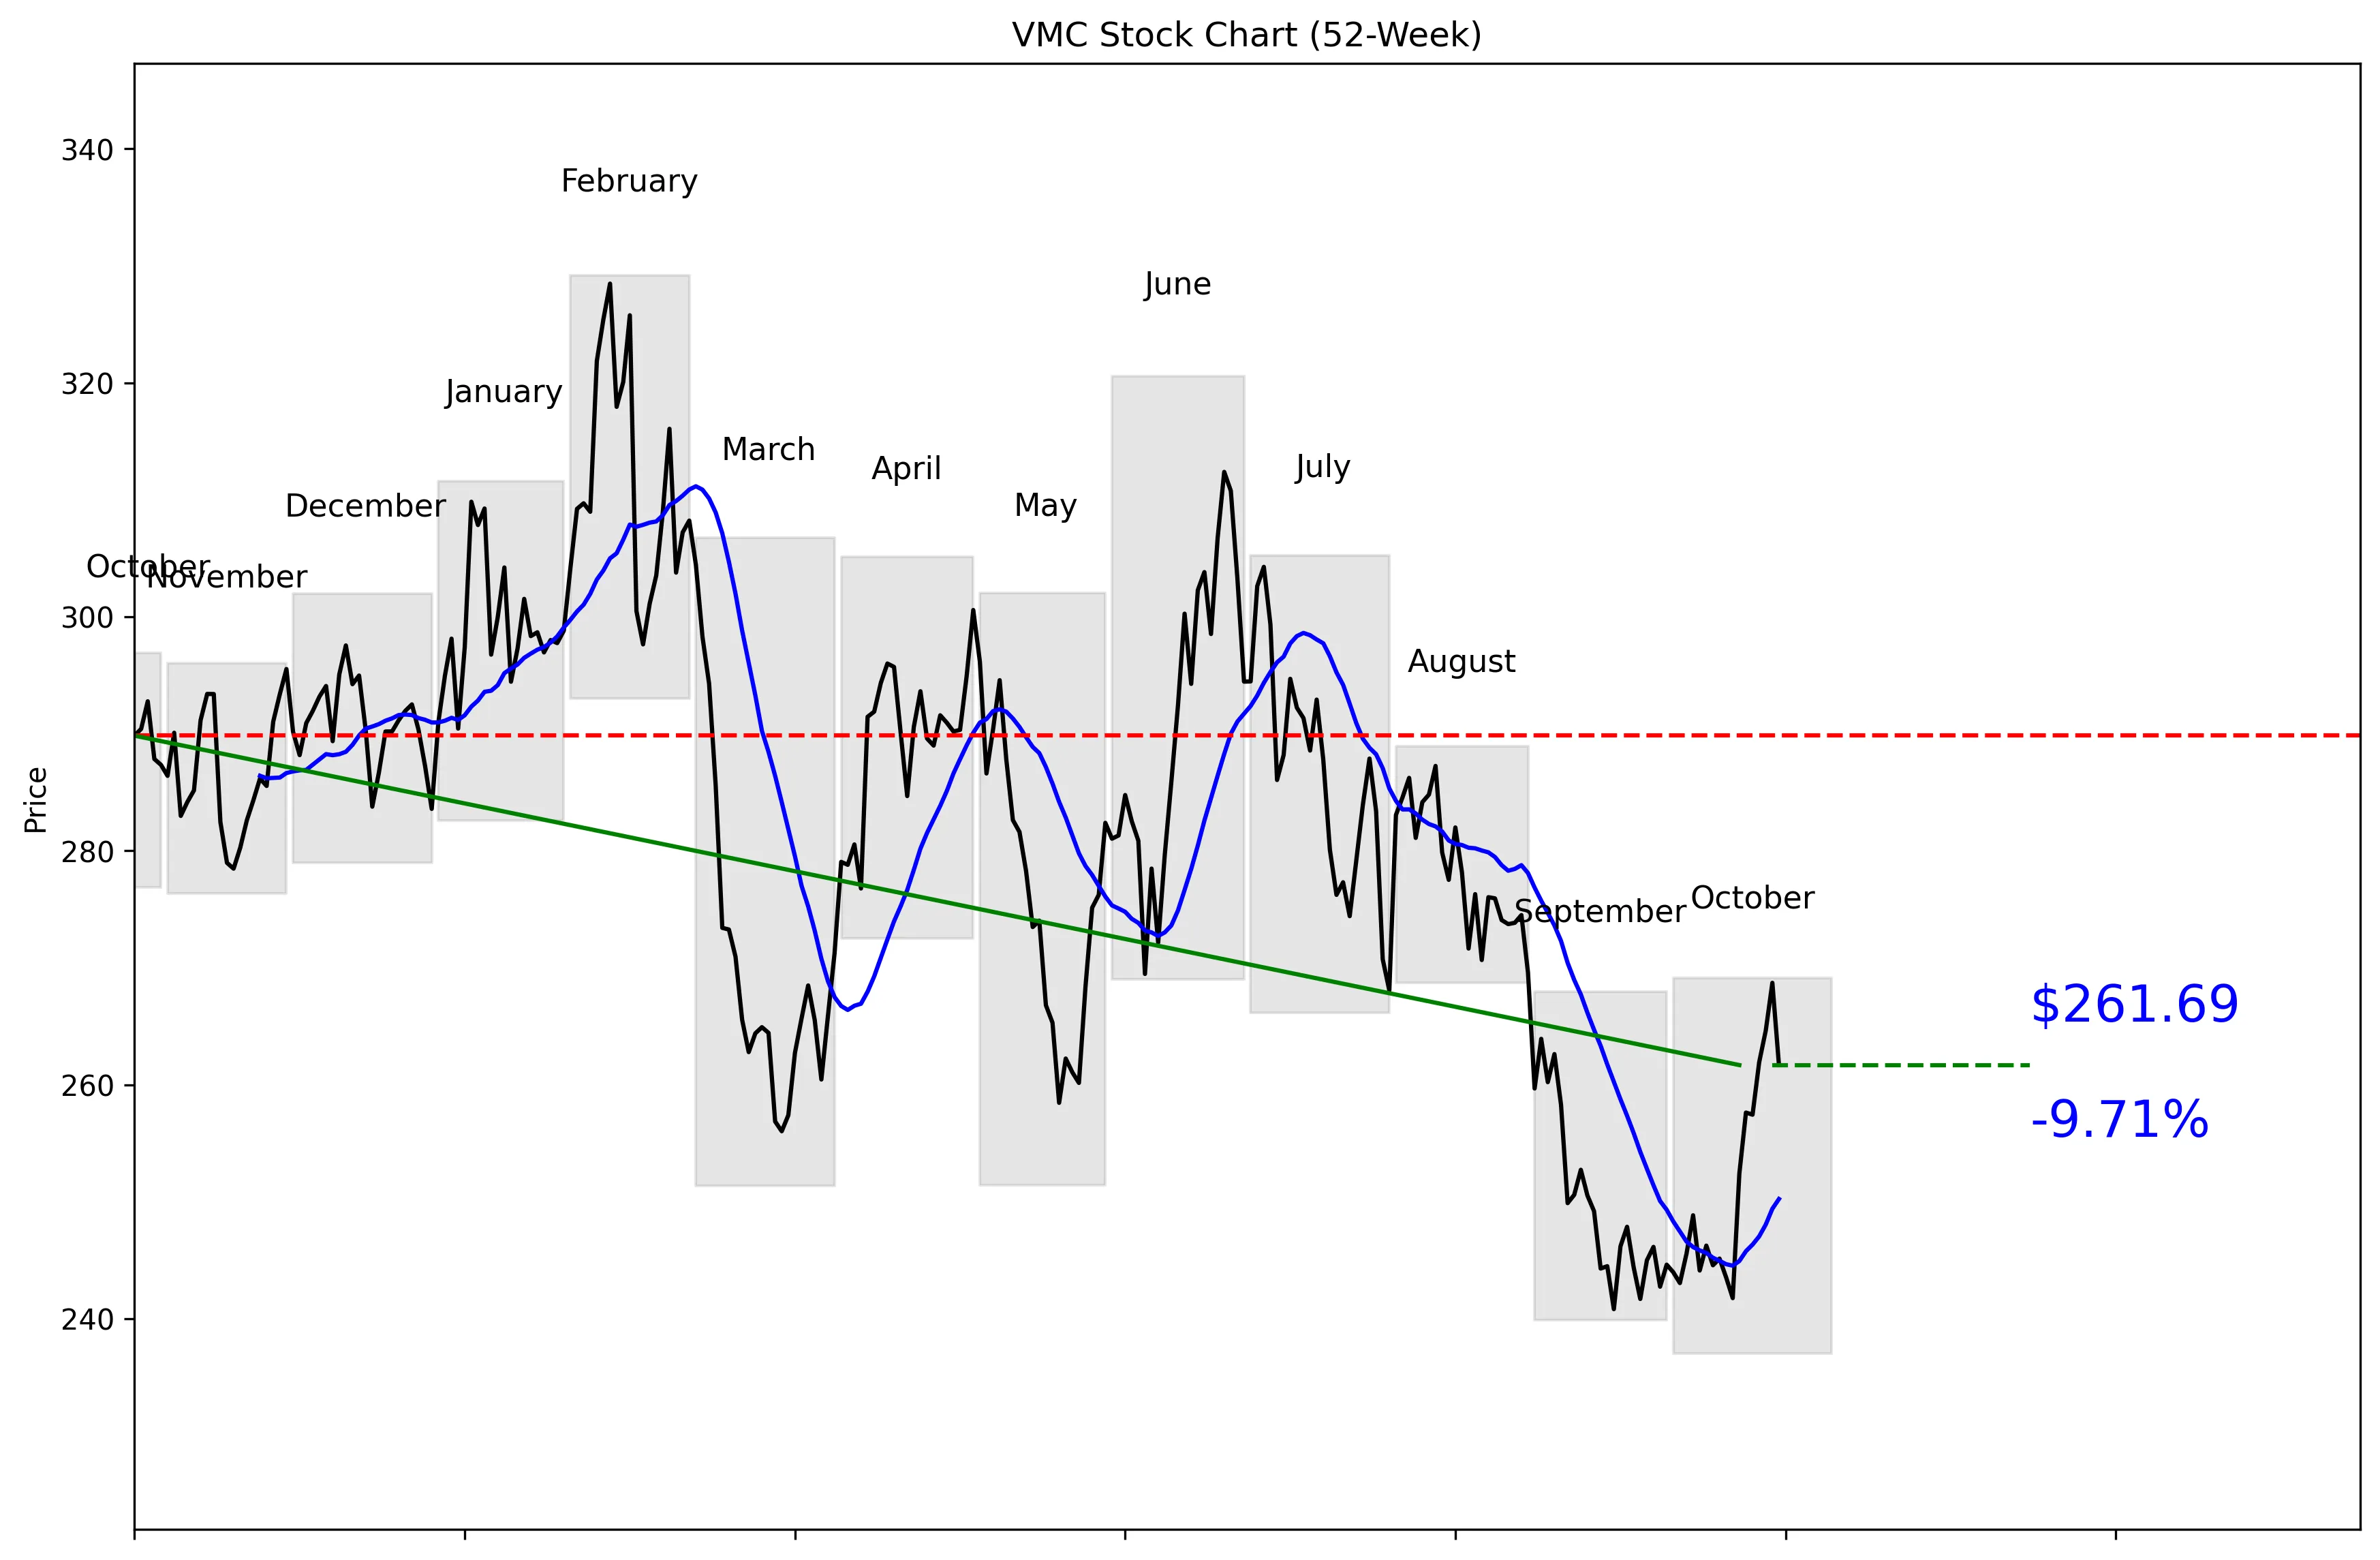
VMC 52-Week Stock Chart
Technical Analysis
VMC trades at $263.37, 27% of the way from its $237.03 52-week low to its $329.20 52-week high. The stock is 20.51% below that high and 10.40% above the low. Price sits 4.57% above the 20-day moving average of $250.24, backed by 1.58% momentum over five trading days and 6.81% over 20 trading days. Near-term support is $240.83, while resistance is $268.72. The trend has improved, but VMC still needs to break $268.72 to confirm more upside.


Recent News and Developments

Jefferies sees relief-rally potential in VMC

Jefferies said Vulcan is positioned for a relief rally after the building-products selloff. January price-increase letters run 8% to 10%, while the firm sees mid-single-digit realized pricing as a potential 2027 catalyst. Source: StreetInsider

Diesel costs put VMC margins under pressure

Wall Street expects third-quarter earnings of $2.86 per share on $2.26 billion in revenue, according to Earnings Whispers. VMC has fallen 12.3% since its previous report while the S&P 500 gained 3.9%, making diesel costs and the company’s $2.4 billion to $2.6 billion full-year adjusted EBITDA target the key issues for the October 29 report. Source: Finviz

Senior operations executive plans retirement

David P. Clement, Vulcan’s senior vice president of operations support and procurement, notified the company on October 19 that he plans to retire in the first quarter of 2027. Vulcan disclosed the planned departure in an SEC filing dated October 22. Source: U.S. Securities and Exchange Commission


Market Sentiment and Analyst Recommendations

Bull Case
VMC has $8.12 billion in revenue and a $34.13 billion market cap, giving investors exposure to a large construction-materials business. Revenue growth is positive at 2.5%, even with diesel costs pressuring margins. Jefferies sees relief-rally potential after the building-products selloff. January price-increase letters of 8% to 10% show pricing power, while mid-single-digit realized pricing could become a 2027 catalyst. The analyst target is $308.30, with the highest estimate at $365.00, and 23 analysts rate the stock a buy. With VMC at $263.37 and 20.51% below its 52-week high, the buy case is straightforward: improving momentum plus stronger realized pricing could close part of that gap.
Bear Case
The P/E ratio of 31.06 is expensive for a company growing revenue by only 2.5%. VMC carries $4.94 billion in total debt against just $194.20 million in cash, leaving little balance-sheet cushion. Diesel costs are pressuring margins and could offset the benefit of higher prices. The stock has fallen 12.3% since its previous report while the S&P 500 gained 3.9%, showing clear relative weakness. Wall Street expects third-quarter earnings of $2.86 per share on $2.26 billion in revenue, putting pressure on management to deliver. The lowest analyst target is $238.00, close to the $237.03 52-week low, so the downside case is real if margins disappoint.
What to Watch
The October 29 earnings report is the immediate catalyst, with Wall Street expecting $2.86 per share on $2.26 billion in revenue. Watch whether management maintains its $2.4 billion to $2.6 billion full-year adjusted EBITDA target. Diesel costs are the key margin risk, so pricing gains need to absorb that pressure. Investors should track whether the January price-increase letters of 8% to 10% translate into mid-single-digit realized pricing. On the chart, a move above $268.72 would clear near-term resistance, while a drop below $240.83 would break near-term support. David P. Clement’s planned retirement in the first quarter of 2027 and the undisclosed transaction involving John F. Steele Jr. also deserve monitoring for operational or strategic implications.
Analyst Consensus
BUY

Based on 23 analyst opinions
Low Target
$238.00
Mean Target
$308.30
High Target
$365.00


Earnings and Financial Data

Sector
Basic Materials
Industry
Building Materials
Employees
11,548
Earnings & Dividends
Next Earnings
Oct 29, 2026
EPS (Trailing)
$8.48
Dividend Yield
77.0%
Payout Ratio
23.8%

Frequently Asked Questions

Is VMC a good stock to buy?
VMC has a buy recommendation from 23 analysts, positive 2.5% revenue growth, and 6.81% momentum over the last 20 trading days. The clear takeaway is that analysts favor the stock, but its 31.06 P/E demands continued execution.
What is VMC’s price target?
The analyst target is $308.30, with estimates ranging from $238.00 to $365.00. The clear takeaway is that Wall Street’s central target sits above the current $263.37 price.
What are VMC’s support and resistance levels?
Near-term support is the 30-day low of $240.83, and near-term resistance is the 30-day high of $268.72. The clear takeaway is that those are the key levels to watch around the current $263.37 price.
Is VMC overvalued?
VMC trades at a P/E ratio of 31.06 while revenue growth is 2.5%. The clear takeaway is that the valuation is demanding relative to the reported growth rate.
Does VMC pay a dividend?
The provided data does not include dividend information, so no dividend claim can be made. The clear takeaway is to verify the current dividend directly before making an income-focused investment decision.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 24, 2026.