
PulteGroup, Inc. (PHM) Stock Analysis
By Nova Skye | AltStation.io | Updated October 17, 2026
Company Overview
Headquartered in Atlanta, United States, and founded in 1950, PulteGroup, Inc. builds and sells homes in the residential construction industry within the consumer cyclical sector. The company develops land to construct single-family detached houses as well as townhomes, condominiums, and duplexes. It sells across three distinct buyer categories: first-time buyers through its Centex brand (roughly 38% of business), move-up buyers via Pulte Homes and John Wieland (around 40%), and active-adult retirees through Del Webb and DiVosta (about 22%). PulteGroup also operates in-house mortgage banking, title, and insurance businesses to capture financing revenue directly at the closing table.
PulteGroup is an established market leader, consistently ranking as one of the top three largest homebuilders in the nation behind D.R. Horton and Lennar. Its edge comes from geographic scale across more than 45 markets in over 25 states and a premier brand in Del Webb that dominates the less rate-sensitive active-adult cohort. The biggest threat to its momentum is housing affordability, where steep mortgage rates squeeze entry-level buyers and intensify pricing competition against rivals like D.R. Horton. Still, its multi-brand setup gives it better customer diversification than single-niche builders.
PulteGroup is growing and executing with strong operational efficiency rather than pulling back. For the full year 2024, the company closed 31,219 homes, pulling in $17.3 billion in home sale revenue, $3.1 billion in net income, and $14.69 in diluted earnings per share. Home sale gross margins held firm between 27.5% and 28.8% in the second half of 2024, showing that pricing discipline stayed intact despite macro volatility. PulteGroup is using that cash flow to prioritize land options and share repurchases, keeping its balance sheet cleaner and far more resilient than in previous housing downturns.
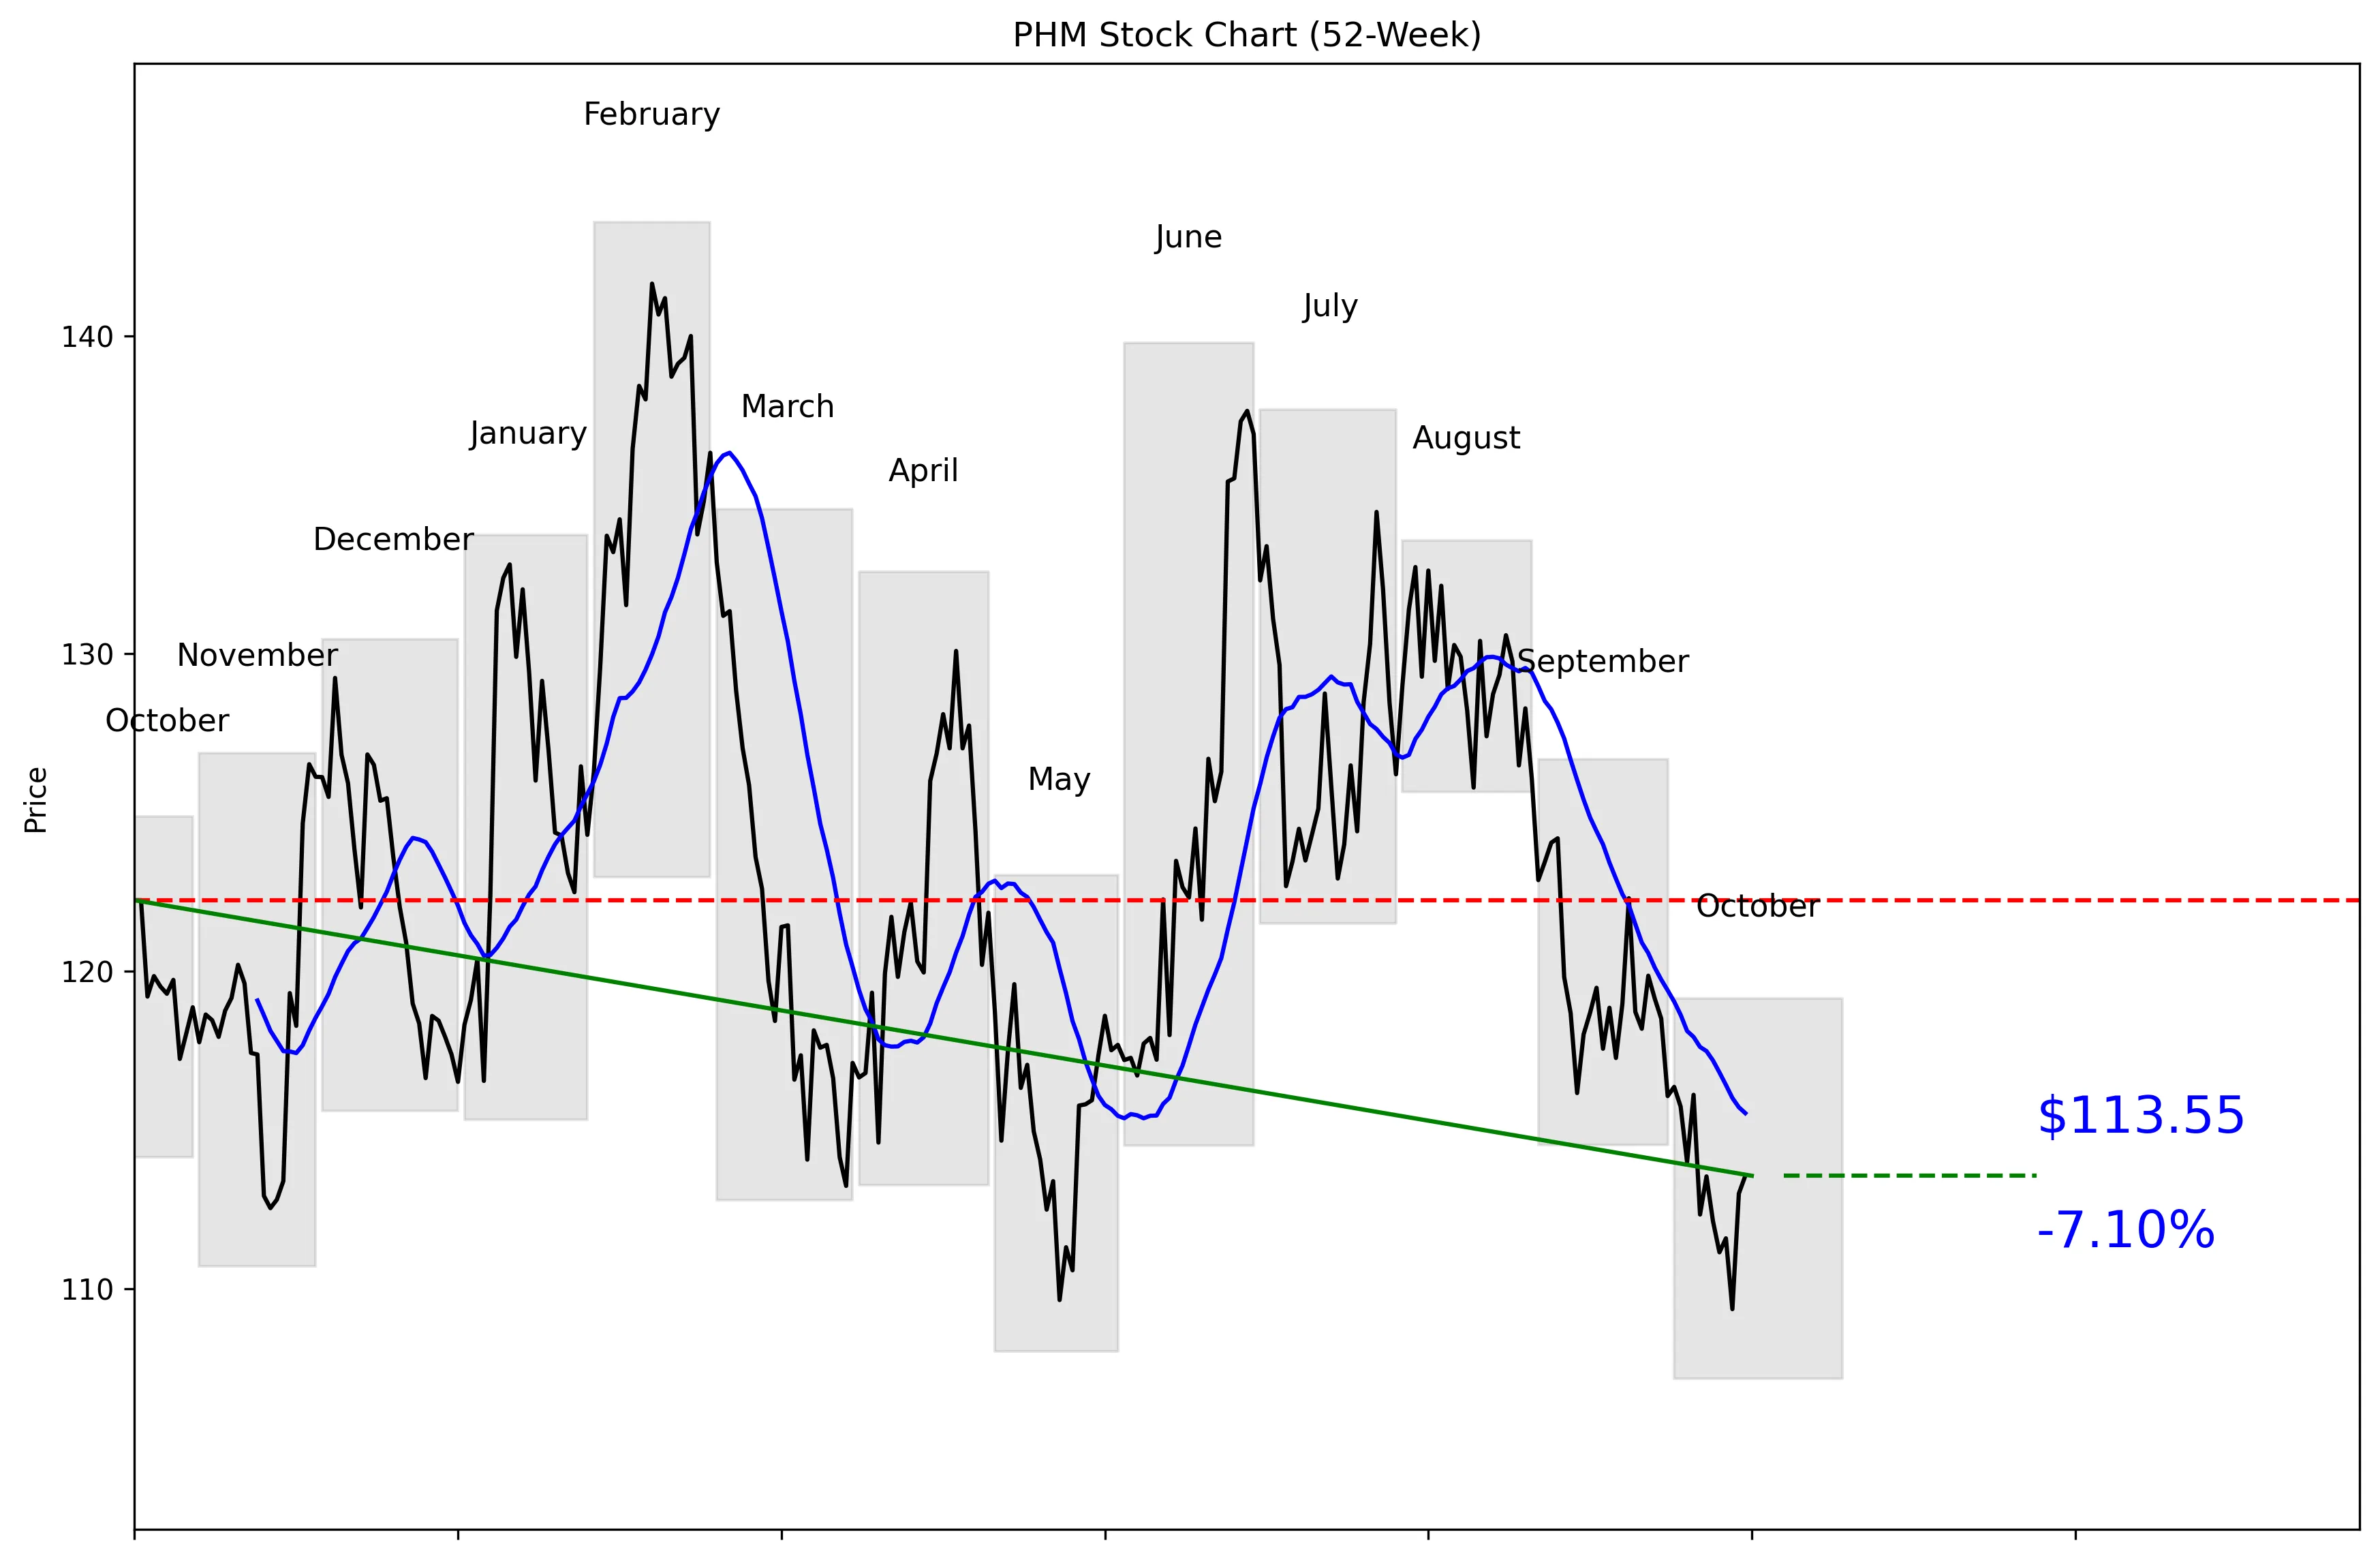
52-Week Price Performance Analysis
Recent News and Developments
Citi lowered its PHM price target from $134 to $122 on October 15 while keeping a Neutral rating. The firm expects another decline in construction activity during October. Source: The Fly
RBC Capital lowered its PHM target from $116 to $111 on October 15 and maintained its Sector Perform rating. The $111 target was below the stock’s $112.99 closing price that day. Source: AD HOC NEWS
Goldman Sachs lowered its PHM price target from $146 to $138 on October 12. The firm reiterated its Hold rating. Source: TipRanks
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports