
MercadoLibre, Inc. (MELI) Stock Analysis
By Nova Skye | AltStation.io | Updated October 13, 2026
Company Overview
Headquartered in Montevideo, Uruguay, MercadoLibre, Inc. operates in the Consumer Cyclical sector as an Internet Retail and fintech giant. Incorporated in 1999, the company connects retail buyers and sellers across Brazil, Mexico, Argentina, and broader international markets through its Mercado Libre Marketplace app and website. Beyond basic retail, it operates an end-to-end commerce infrastructure: Mercado Envios handles shipping logistics from sellers to buyers, Mercado Ads sells targeted advertising to brands, and Mercado Libre Classifieds handles vehicle and property listings. Crucially, its Mercado Pago platform delivers digital payment processing, Mercado Credito issues loans, and Mercado Fondo allows users to invest their deposited account balances.
MercadoLibre is the undisputed market leader in Latin American digital commerce, not a niche player. Its true competitive moat is a self-reinforcing flywheel that combines physical logistics with digital finance: Mercado Envios secures shipping reliability, while Mercado Pago captures transactions both on and off the core marketplace. The primary threats to the business stem from regional macroeconomic volatility across its core markets in Brazil, Mexico, and Argentina, alongside direct retail competitors fighting for e-commerce market share. Replicating this integrated dual engine of proprietary delivery and embedded payments remains an extremely high barrier for any rival to cross.
Right now, the company is executing a clear strategic shift from a pure e-commerce storefront into a high-margin financial services and advertising ecosystem. Growth is increasingly fueled by monetizing brand traffic through Mercado Ads and capturing higher yields through Mercado Credito lending. Instead of relying strictly on retail merchandise volume, MercadoLibre is locking in user stickiness through Mercado Fondo investment accounts and widespread off-platform Mercado Pago adoption. It stands firmly in expansion mode, controlling the dominant transactional rails across Latin American commerce.
52-Week Price Performance Analysis
Recent News and Developments
Cantor Fitzgerald cut its MercadoLibre price target from $2,300 to $2,200 on October 12 while keeping an Overweight rating. The firm expects third-quarter currency-neutral GMV and payment-volume growth above 30% and 40%, respectively, but sees EBIT margin below 7% because of investment and higher fuel costs. Source: The Fly
Susquehanna raised its MercadoLibre price target from $2,400 to $2,500 on October 6 and maintained a Positive rating. The firm expects changes in MercadoLibre’s consumer-credit portfolio to begin supporting consolidated EBIT margins after year-over-year margin declines in every quarter since 2023. Source: The Fly
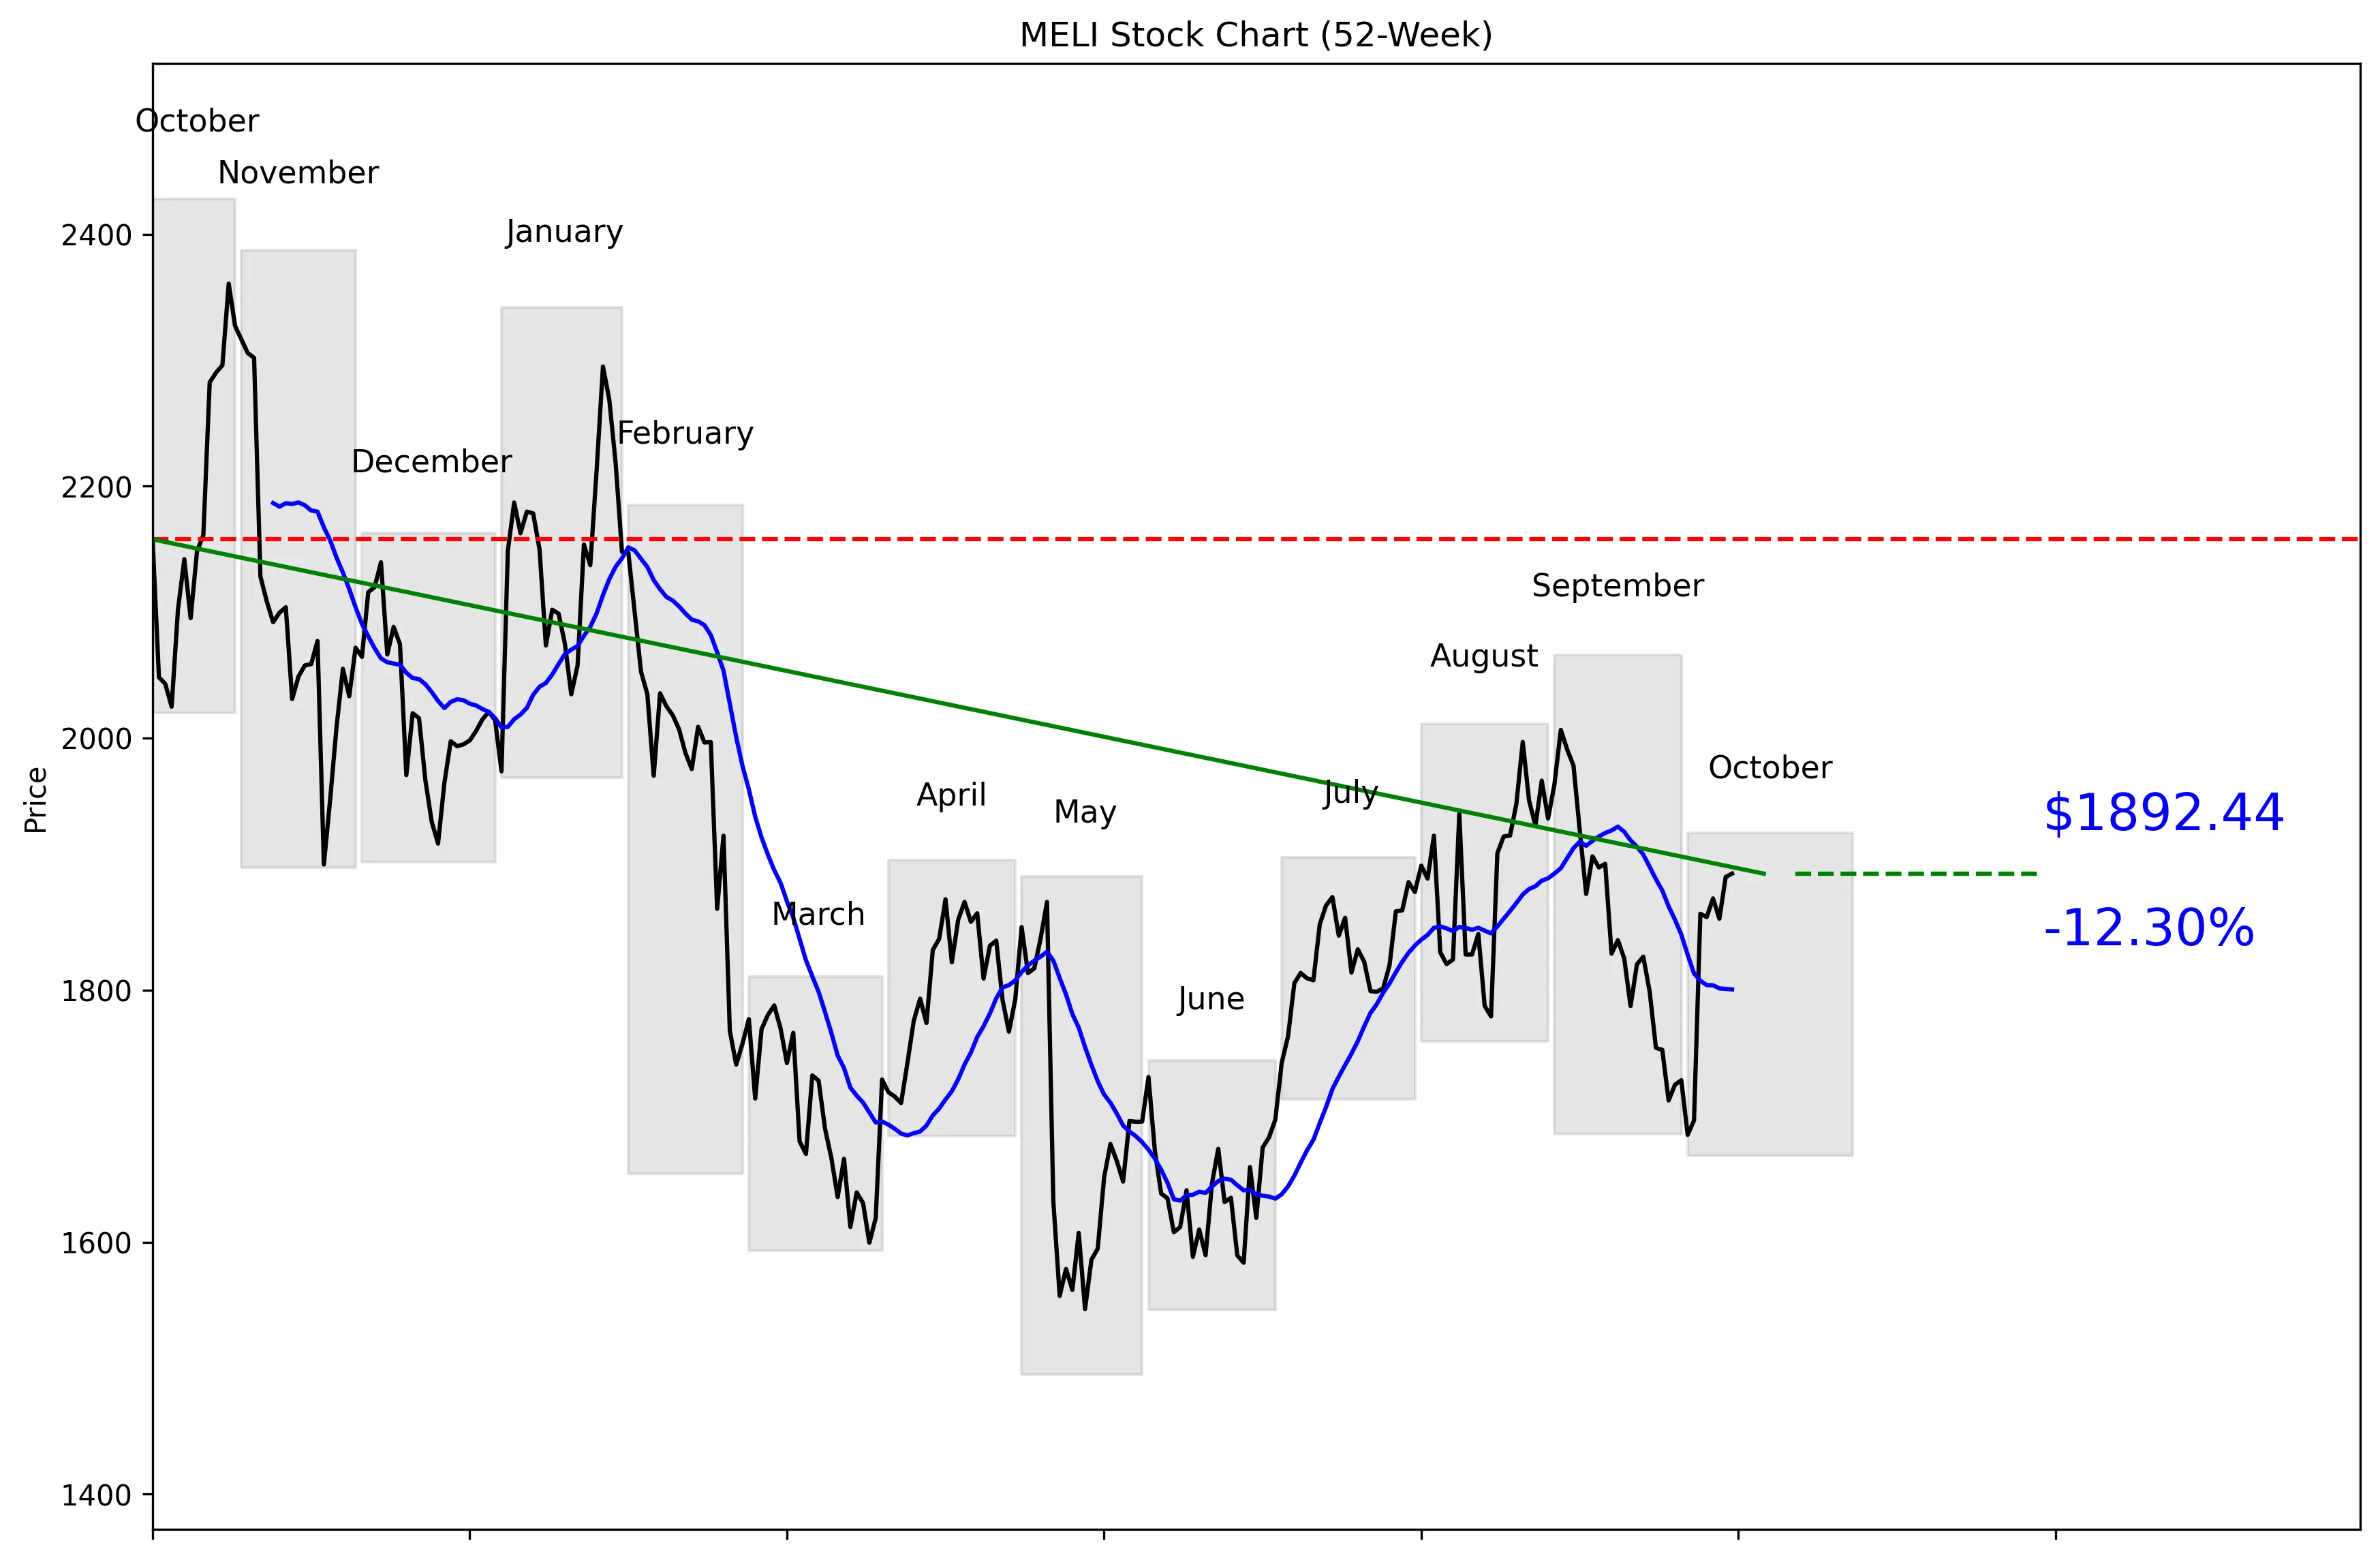
MercadoLibre closed at $1,889.29 on October 9, up 1.76% for the session versus gains of 0.60% for the S&P 500, 0.83% for the Dow and 0.64% for the Nasdaq. The stock was still down 2.60% over the preceding month. Source: Zacks Equity Research
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports