ALTSTATION.IO

Booking Holdings Inc. (BKNG) Stock Analysis

By Nova Skye | AltStation.io | Updated November 01, 2026

Price
$148.13
Change
-1.53%
Market Cap
$111.30B
Avg Volume
7.0M

Company Overview

Booking Holdings runs the booking engine for global travel from its headquarters in Norwalk, Connecticut. Operating in the travel services segment of the consumer cyclical sector, the company connects travelers and diners with accommodations, flights, rental cars, and restaurant tables. Its core consumer footprint spans five major brands: Booking.com, Priceline, Agoda, KAYAK, and OpenTable. In addition to consumer transactions across the United States, the United Kingdom, the Netherlands, and international markets, the business sells payment facilitation, travel insurance, restaurant software, and advertising.

Booking Holdings holds a dominant market leader position in online travel by controlling both direct booking channels and meta-search comparison tools. Its main competitive edge is geographic and functional diversification, leveraging Agoda for regional reach, Priceline for discount packages, and KAYAK to capture comparison shoppers. The biggest structural vulnerability is its cyclical exposure to discretionary consumer spending, alongside constant competition from direct airline and hotel booking portals. Managing both meta-search aggregators and direct booking platforms creates an inherent tension, but it keeps users inside the company’s ecosystem.

Founded in 1997 and renamed from The Priceline Group in February 2018, the company has shifted from a discount-focused booking agent to a full-stack travel and dining network. Instead of relying solely on room commissions, Booking Holdings now monetizes payment processing, travel insurance, and restaurant operations through OpenTable. That multi-product setup broadens its revenue base across the entire trip lifecycle, giving it more staying power than single-niche travel competitors.

Key Financials
Market Cap
$111.30B
Revenue
$28.24B
EBITDA
$10.41B
Gross Margin
87.2%
Profit Margin
25.5%
Revenue Growth
8.1%
Total Cash
$17.21B
Total Debt
$20.92B
Free Cash Flow
$7.73B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
16.42
Forward P/E
11.97
Beta
1.13
52-Week High
$220.81
52-Week Low
$146.28
EPS
$9.02
50-Day Avg
$171.26
200-Day Avg
$176.83
Price/Book
-10.41
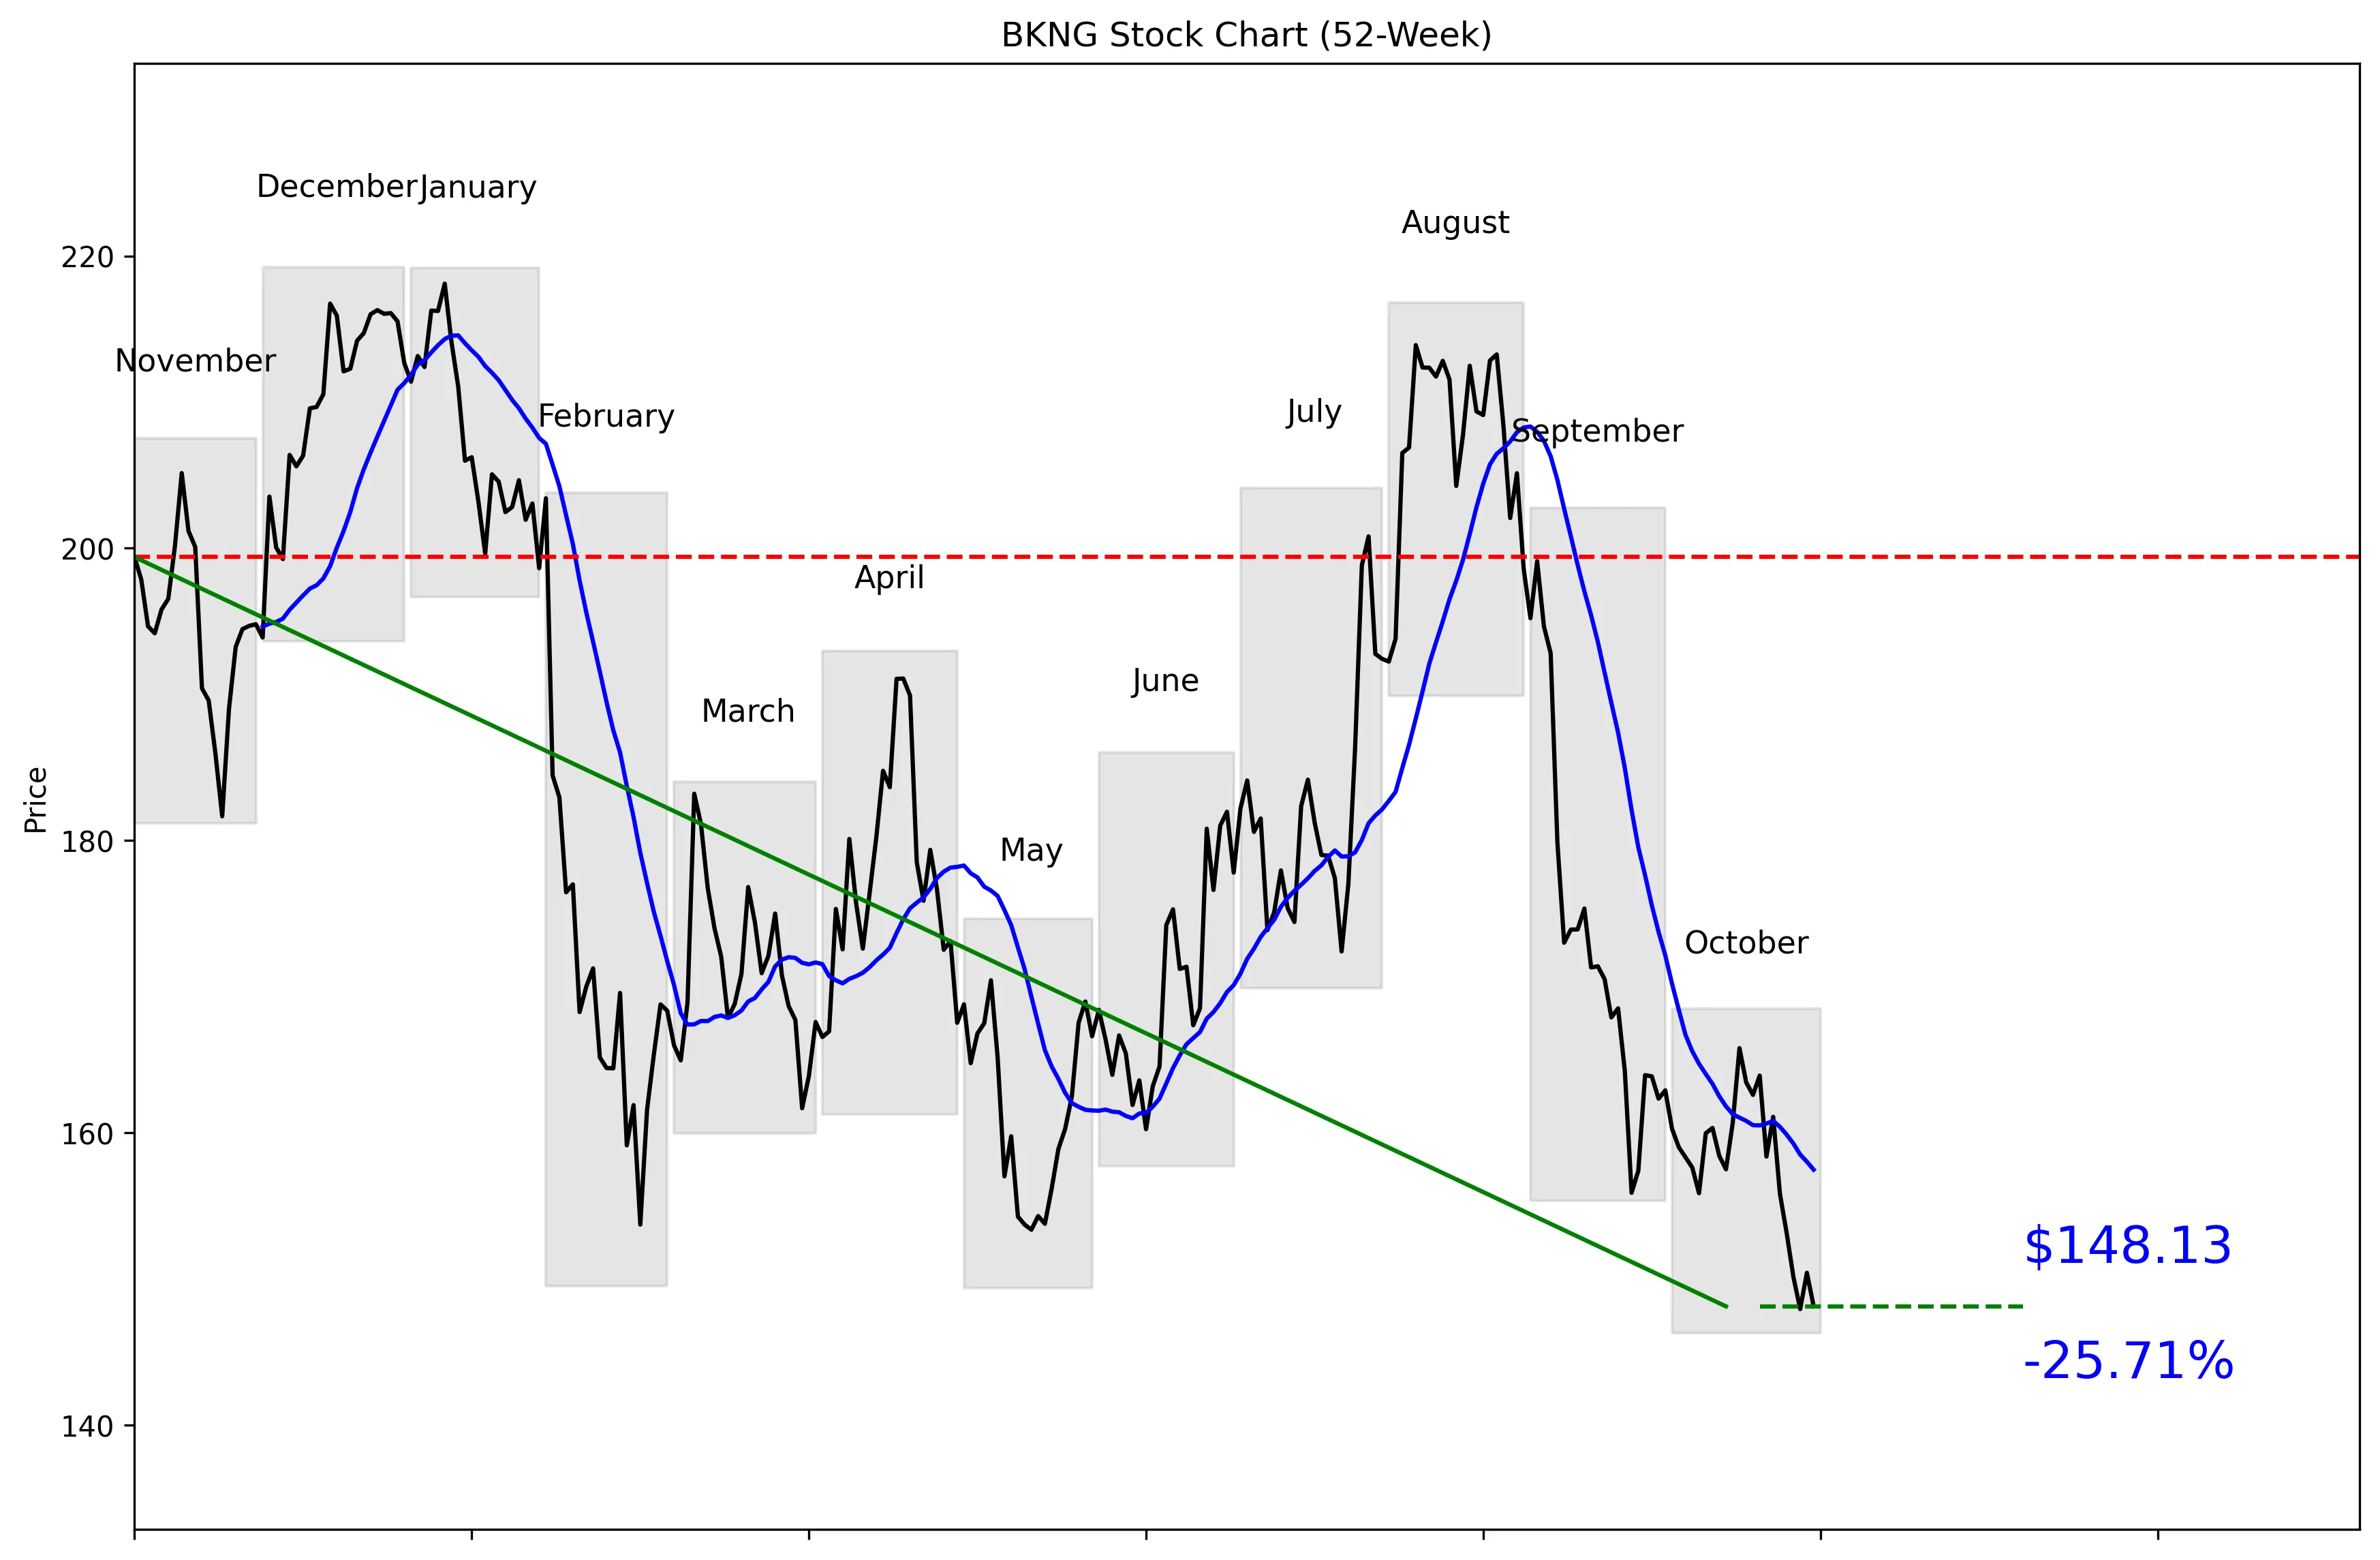
BKNG 52-Week Stock Chart
Technical Analysis
BKNG trades at $148.13, just 3% of the way from its $146.28 52-week low to its $219.22 52-week high. The stock is 32.43% below that high and only 1.26% above the low. Price sits 5.94% below the 20-day moving average of $157.48. Momentum remains negative, with declines of 4.94% over five trading days and 6.85% over 20 trading days. Near-term support is $147.94, while resistance is $168.52.


Recent News and Developments

Baird and Wells Fargo cut BKNG price targets

Baird lowered its Booking Holdings target to $223 from $230 on October 27 while keeping a Buy rating. Wells Fargo cut its target to $190 from $220 on October 26 and maintained a Hold rating. Source: TipRanks

BofA trims target despite stronger Q3 estimates

BofA reduced its BKNG price target to $232 from $234 but kept its Buy rating. The firm raised its Q3 estimates to 342 million room nights, $53.0 billion in gross bookings, $9.61 billion in revenue and $4.52 in earnings per share. Source: Investing.com

BKNG loses ground before earnings

BKNG closed at $150.14 on October 27 after falling 1.96%, then dropped another 1.46% to $147.94 on October 28. Shares recovered 1.68% on October 29 before falling 1.25% to $148.55 on October 30. Source: FinanceCharts


Market Sentiment and Analyst Recommendations

Bull Case
Booking Holdings generated $28.24 billion in revenue, with revenue growing 8.1%. Wall Street expects Q3 earnings of $4.48 per share, up 12.6%, on revenue of $9.56 billion, up 6.2%. BofA’s stronger Q3 estimates call for 342 million room nights, $53.0 billion in gross bookings, $9.61 billion in revenue and $4.52 per share in earnings. The company also holds $17.21 billion in cash, giving it substantial financial capacity. At 16.42 times earnings, the valuation is not demanding relative to the expected earnings growth. The consensus recommendation is buy across 35 analysts, with a $232.71 target and a high estimate of $301.00. The bull case is simple: expectations are rising while the stock trades close to its 52-week low.
Bear Case
The chart is weak, with BKNG down 32.43% from its 52-week high and trading 5.94% below its 20-day moving average. Five-day momentum is negative 4.94%, while 20-day momentum is negative 6.85%. The stock is only 1.26% above its 52-week low, leaving little technical room before that low is tested again. Total debt of $20.92 billion exceeds total cash of $17.21 billion. Analysts have also become less aggressive: Baird cut its target from $230 to $223, BofA reduced its target from $234 to $232, and Wells Fargo lowered its target from $220 to $190. Wells Fargo maintained a Hold rating, which conflicts with the broader buy consensus. The analyst range of $170.00 to $301.00 shows substantial disagreement about what BKNG is worth.
What to Watch
The next major test is the Q3 report, although the reporting date was not provided. Investors should compare reported earnings with the $4.48-per-share consensus and BofA’s $4.52 estimate. Revenue needs to hold near the $9.56 billion consensus or BofA’s $9.61 billion estimate. Operating demand should be measured against forecasts of 338.61 million room nights, 17.88 million airline tickets and 22.45 million rental-car days; BofA expects 342 million room nights and $53.0 billion in gross bookings. On the chart, $147.94 is the immediate support level, and a break below the $146.28 52-week low would weaken the setup further. A recovery above the $157.48 20-day moving average would be the first sign that momentum is improving, while $168.52 is the next resistance level. Investors should also watch whether additional firms follow the October 26 Wells Fargo target cut and October 27 Baird cut or move back toward the $232.71 consensus target.
Analyst Consensus
BUY

Based on 35 analyst opinions
Low Target
$170.00
Mean Target
$232.71
High Target
$301.00


Earnings and Financial Data

Sector
Consumer Cyclical
Industry
Travel Services
Employees
25,550
Earnings & Dividends
Next Earnings
Nov 03, 2026
EPS (Trailing)
$9.02
Dividend Yield
113.0%
Payout Ratio
17.8%

Frequently Asked Questions

Is BKNG a good stock to buy?
The consensus recommendation is buy based on 35 analysts, and revenue growth is 8.1%. The clear takeaway is that analysts remain bullish, but the stock’s negative momentum raises near-term risk.
What is BKNG’s price target?
The analyst target is $232.71, with estimates ranging from $170.00 to $301.00. The takeaway is that analysts see upside from $148.13, but their valuation range is wide.
Is BKNG stock undervalued?
BKNG trades at a P/E ratio of 16.42 and is 32.43% below its 52-week high. The takeaway is that the valuation and depressed price may appeal to value-focused investors, but neither guarantees a rebound.
How strong is Booking Holdings’ balance sheet?
Booking Holdings has $17.21 billion in cash and $20.92 billion in debt. The takeaway is that its cash position is substantial, but debt is higher than cash.
What are BKNG’s key support and resistance levels?
Near-term support is $147.94, and near-term resistance is $168.52. The takeaway is that BKNG is currently trading much closer to support than resistance.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated November 01, 2026.