ALTSTATION.IO

Carnival Corporation Ltd. (CCL) Stock Analysis

By Nova Skye | AltStation.io | Updated October 19, 2026

Price
$26.20
Change
-1.00%
Market Cap
$35.22B
Avg Volume
21.2M

Company Overview

Headquartered in Miami, Florida, Carnival Corporation is the world’s largest leisure travel provider, operating in the Consumer Cyclical sector within Travel Services. Founded in 1972, the company sells ocean cruises and land-based vacations to retail travelers across nine global brands, including Carnival Cruise Line, Princess Cruises, and Holland America Line. Beyond its fleet of over 90 ships, Carnival generates revenue by running private port destinations, hotels, lodges, and glass-domed railcars. It sells these vacations directly to consumers and through travel agents across four operating segments, led by North America and Europe.

Carnival is the undisputed volume leader in the cruise business, commanding roughly 41.5% of global passenger volume and about 36% of total industry revenue. Its massive scale gives it port leverage and unit-cost efficiencies that competitors like Royal Caribbean Group and Norwegian Cruise Line Holdings cannot easily match at the budget tier. The main threat is its heavy reliance on middle-income household budgets, leaving it vulnerable to inflation and fuel price spikes in the cyclical travel market. Unlike luxury-only operators, Carnival has to keep booking volumes high year-round to feed its massive fixed-cost ship footprint.

Carnival is in clear expansion mode after driving a massive operational rebound. The business generated $25.02 billion in revenue in 2024 and grew to a record $26.6 billion in 2025, boosting operating income 25% to $4.5 billion. Management is actively pruning older assets from secondary brands while expanding flagship fleets like Carnival Cruise Line, which now operates 29 vessels. With strong forward bookings locked in at higher ticket prices, the strategic focus has firmly shifted from capacity recovery to cash generation.

Key Financials
Market Cap
$35.22B
Revenue
$27.59B
EBITDA
$7.29B
Gross Margin
55.4%
Profit Margin
11.4%
Revenue Growth
3.5%
Total Cash
$1.22B
Total Debt
$25.16B
Free Cash Flow
$1.81B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
11.54
Forward P/E
10.23
Beta
2.38
52-Week High
$34.03
52-Week Low
$21.45
EPS
$2.27
50-Day Avg
$24.94
200-Day Avg
$27.30
Price/Book
2.50
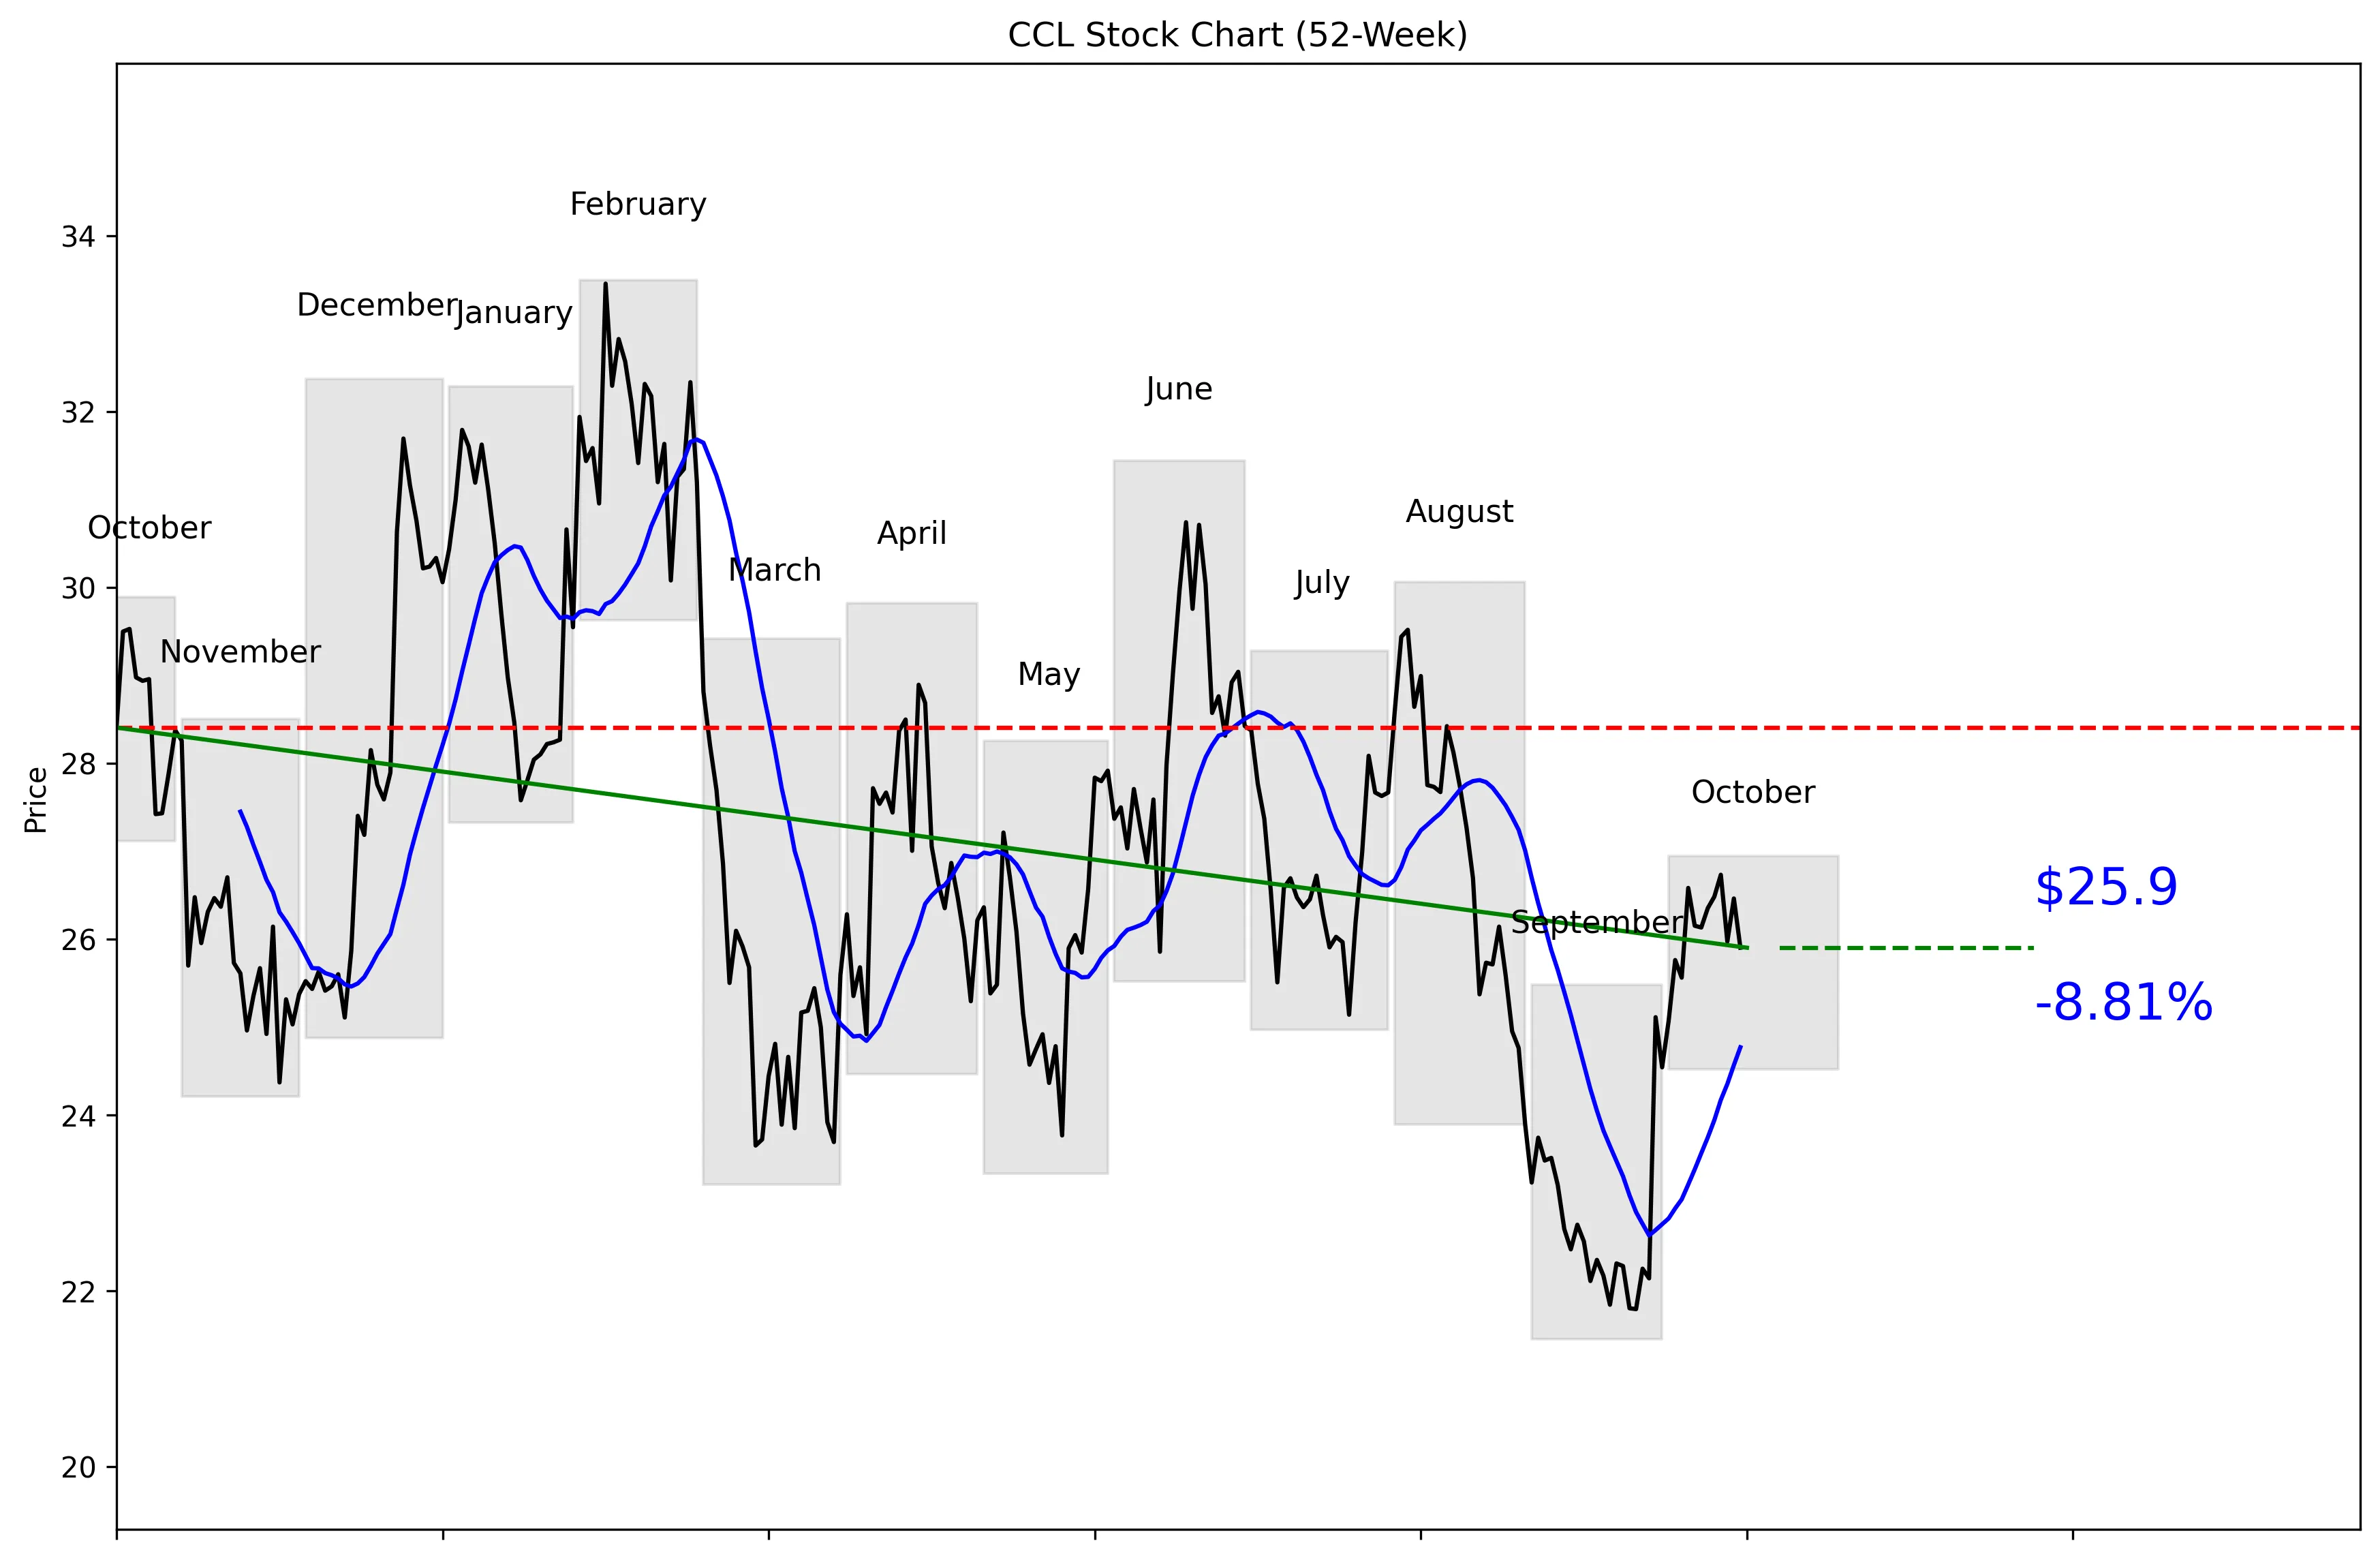
CCL 52-Week Stock Chart
Technical Analysis
CCL trades at $26.20, 37% of the way from its $21.45 52-week low to its $33.49 52-week high. The stock is 22.67% below that high and 20.75% above the low. Price is 4.57% above the 20-day moving average of $24.77, while 20-day momentum remains strong at 18.59%. The shorter trend has weakened, with five-day momentum at -1.71%. Near-term support sits at $21.79, while resistance is $26.73.


Recent News and Developments

Carnival cuts its Australian fleet in half

Carnival will pull Carnival Luminosa and Carnival Adventure from Australia in March 2028, reducing its local fleet from four ships to two. The company cited the need for long-term regulatory certainty and globally competitive operating conditions. Source: ABC News

Carnival launches four bundled FunPacks

Carnival introduced four packages combining Wi-Fi, drinks, dining, excursions and other extras, claiming savings of 35% to 55% versus separate purchases. The company will also introduce dynamic pricing for beverage packages and Wi-Fi plans on December 1, 2026. Source: Carnival Cruise Line

Carnival returns to Acapulco after 17 years

Holland America Line’s Eurodam completed Carnival Corporation’s first scheduled Acapulco call in 17 years. Carnival’s eight cruise lines have more than 1,300 calls scheduled across 14 Mexican ports in 2026, with approximately 4.6 million visitors expected. Source: Carnival Corporation


Market Sentiment and Analyst Recommendations

Bull Case
Carnival is generating $27.59 billion in revenue with 3.5% revenue growth. The stock trades at 11.54 times earnings, which is a reasonable valuation if growth continues and debt comes down. Analysts are bullish, with 26 analysts rating CCL a buy and an average target of $33.89. The target range runs from $28.70 to $43.00, entirely above the current $26.20 price. Carnival’s new FunPacks bundle Wi-Fi, drinks, dining and excursions while claiming customer savings of 35% to 55%, giving the company another way to sell onboard extras. Carnival also has more than 1,300 scheduled calls across 14 Mexican ports in 2026, with approximately 4.6 million visitors expected, supporting the case for sustained demand.
Bear Case
Debt is the central risk: Carnival has $25.16 billion in total debt against only $1.22 billion in cash. Revenue growth of 3.5% is positive but modest for a company carrying that balance-sheet burden. The stock remains 22.67% below its 52-week high, showing that investors are not fully convinced by the recovery. Five-day momentum is negative at -1.71%, and the shares recently lost 1.7% for the week ended October 16. Carnival will cut its Australian fleet from four ships to two in March 2028, citing regulatory uncertainty and operating conditions that are not globally competitive. At $26.20, the stock is also close to near-term resistance at $26.73, so the current rally could stall without stronger operating results.
What to Watch
The first technical test is $26.73, the 30-day high and near-term resistance level. A move back below the $24.77 20-day moving average would weaken the current trend, while a drop toward $21.79 would put near-term support under pressure. Investors should watch whether 20-day momentum of 18.59% survives the current five-day decline of 1.71%. Carnival will introduce dynamic pricing for beverage packages and Wi-Fi plans on December 1, 2026, making pricing execution an important upcoming catalyst. Revenue growth needs to improve from 3.5%, especially with $25.16 billion of debt and $1.22 billion of cash. The analyst target range of $28.70 to $43.00 sets a bullish benchmark, but the company must show that bundled extras and expanded Mexican port activity can translate into stronger financial performance.
Analyst Consensus
BUY

Based on 26 analyst opinions
Low Target
$28.70
Mean Target
$33.89
High Target
$43.00


Earnings and Financial Data

Sector
Consumer Cyclical
Industry
Travel Services
Employees
160,000
Earnings & Dividends
Next Earnings
Dec 18, 2026
EPS (Trailing)
$2.27
Dividend Yield
170.0%
Payout Ratio
19.8%

Frequently Asked Questions

Is CCL a good stock to buy?
The analyst recommendation is buy based on 26 analysts, and the stock trades at a P/E ratio of 11.54. Takeaway: Wall Street is bullish, but investors must weigh that valuation against $25.16 billion in debt.
What is CCL’s price target?
The average analyst target is $33.89, with estimates ranging from $28.70 to $43.00. Takeaway: Every listed analyst target is above the current $26.20 price.
Is CCL stock undervalued?
CCL trades at 11.54 times earnings and is 22.67% below its 52-week high. Takeaway: The valuation and price position suggest upside potential, but they do not eliminate the company’s balance-sheet risk.
What are CCL’s support and resistance levels?
Near-term support is $21.79, and near-term resistance is $26.73. Takeaway: With the stock at $26.20, resistance is the closer technical level.
How strong is CCL’s momentum?
CCL has gained 18.59% over the last 20 trading days but lost 1.71% over the last five trading days. Takeaway: The broader short-term trend is positive, but momentum has cooled.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 19, 2026.