
Royal Caribbean Cruises Ltd. (RCL) Stock Analysis
By Nova Skye | AltStation.io | Updated October 06, 2026
Company Overview
Royal Caribbean Cruises Ltd. is a global vacation provider headquartered in Miami, Florida, operating in the Consumer Cyclical sector under the Travel Services industry. Founded in 1968, the company sells ocean cruise vacations and onboard experiences to leisure travelers worldwide. Its business runs through three core brands: Royal Caribbean International for mass-market family vacations, Celebrity Cruises for premium travelers, and Silversea Cruises for ultra-luxury clients. Customers buy travel itineraries ranging from short regional sailings to multi-week international voyages.
Royal Caribbean is an industry heavyweight, controlling roughly 31% of global cruise capacity and sitting alongside Carnival Corporation in a market oligopoly. Its primary edge comes from massive ship scale and tiered branding, which allows the company to extract higher onboard spending across all income demographics. The main risks are straightforward: high capital expenditure requirements, balance-sheet leverage from shipbuilding, and direct pricing pressure from rivals like Carnival and Norwegian Cruise Line. Because travel services are discretionary, any pullback in consumer spending directly hits ticket yields.
The company is in an active growth phase, operating a global fleet of 69 ships as of December 31, 2025, and deploying new flagship builds like the Icon class to push yields higher. Booking volumes and pricing power have remained solid, allowing the operator to convert high vessel utilization into serious cash flow. The key operational focus right now is using that cash generation to manage long-term fleet debt while maintaining high occupancy rates across global itineraries. If consumer travel budgets soften, Royal Caribbean’s heavy fixed costs will squeeze margins, but its scale gives it a much stronger defensive moat than smaller peers.
52-Week Price Performance Analysis
Recent News and Developments
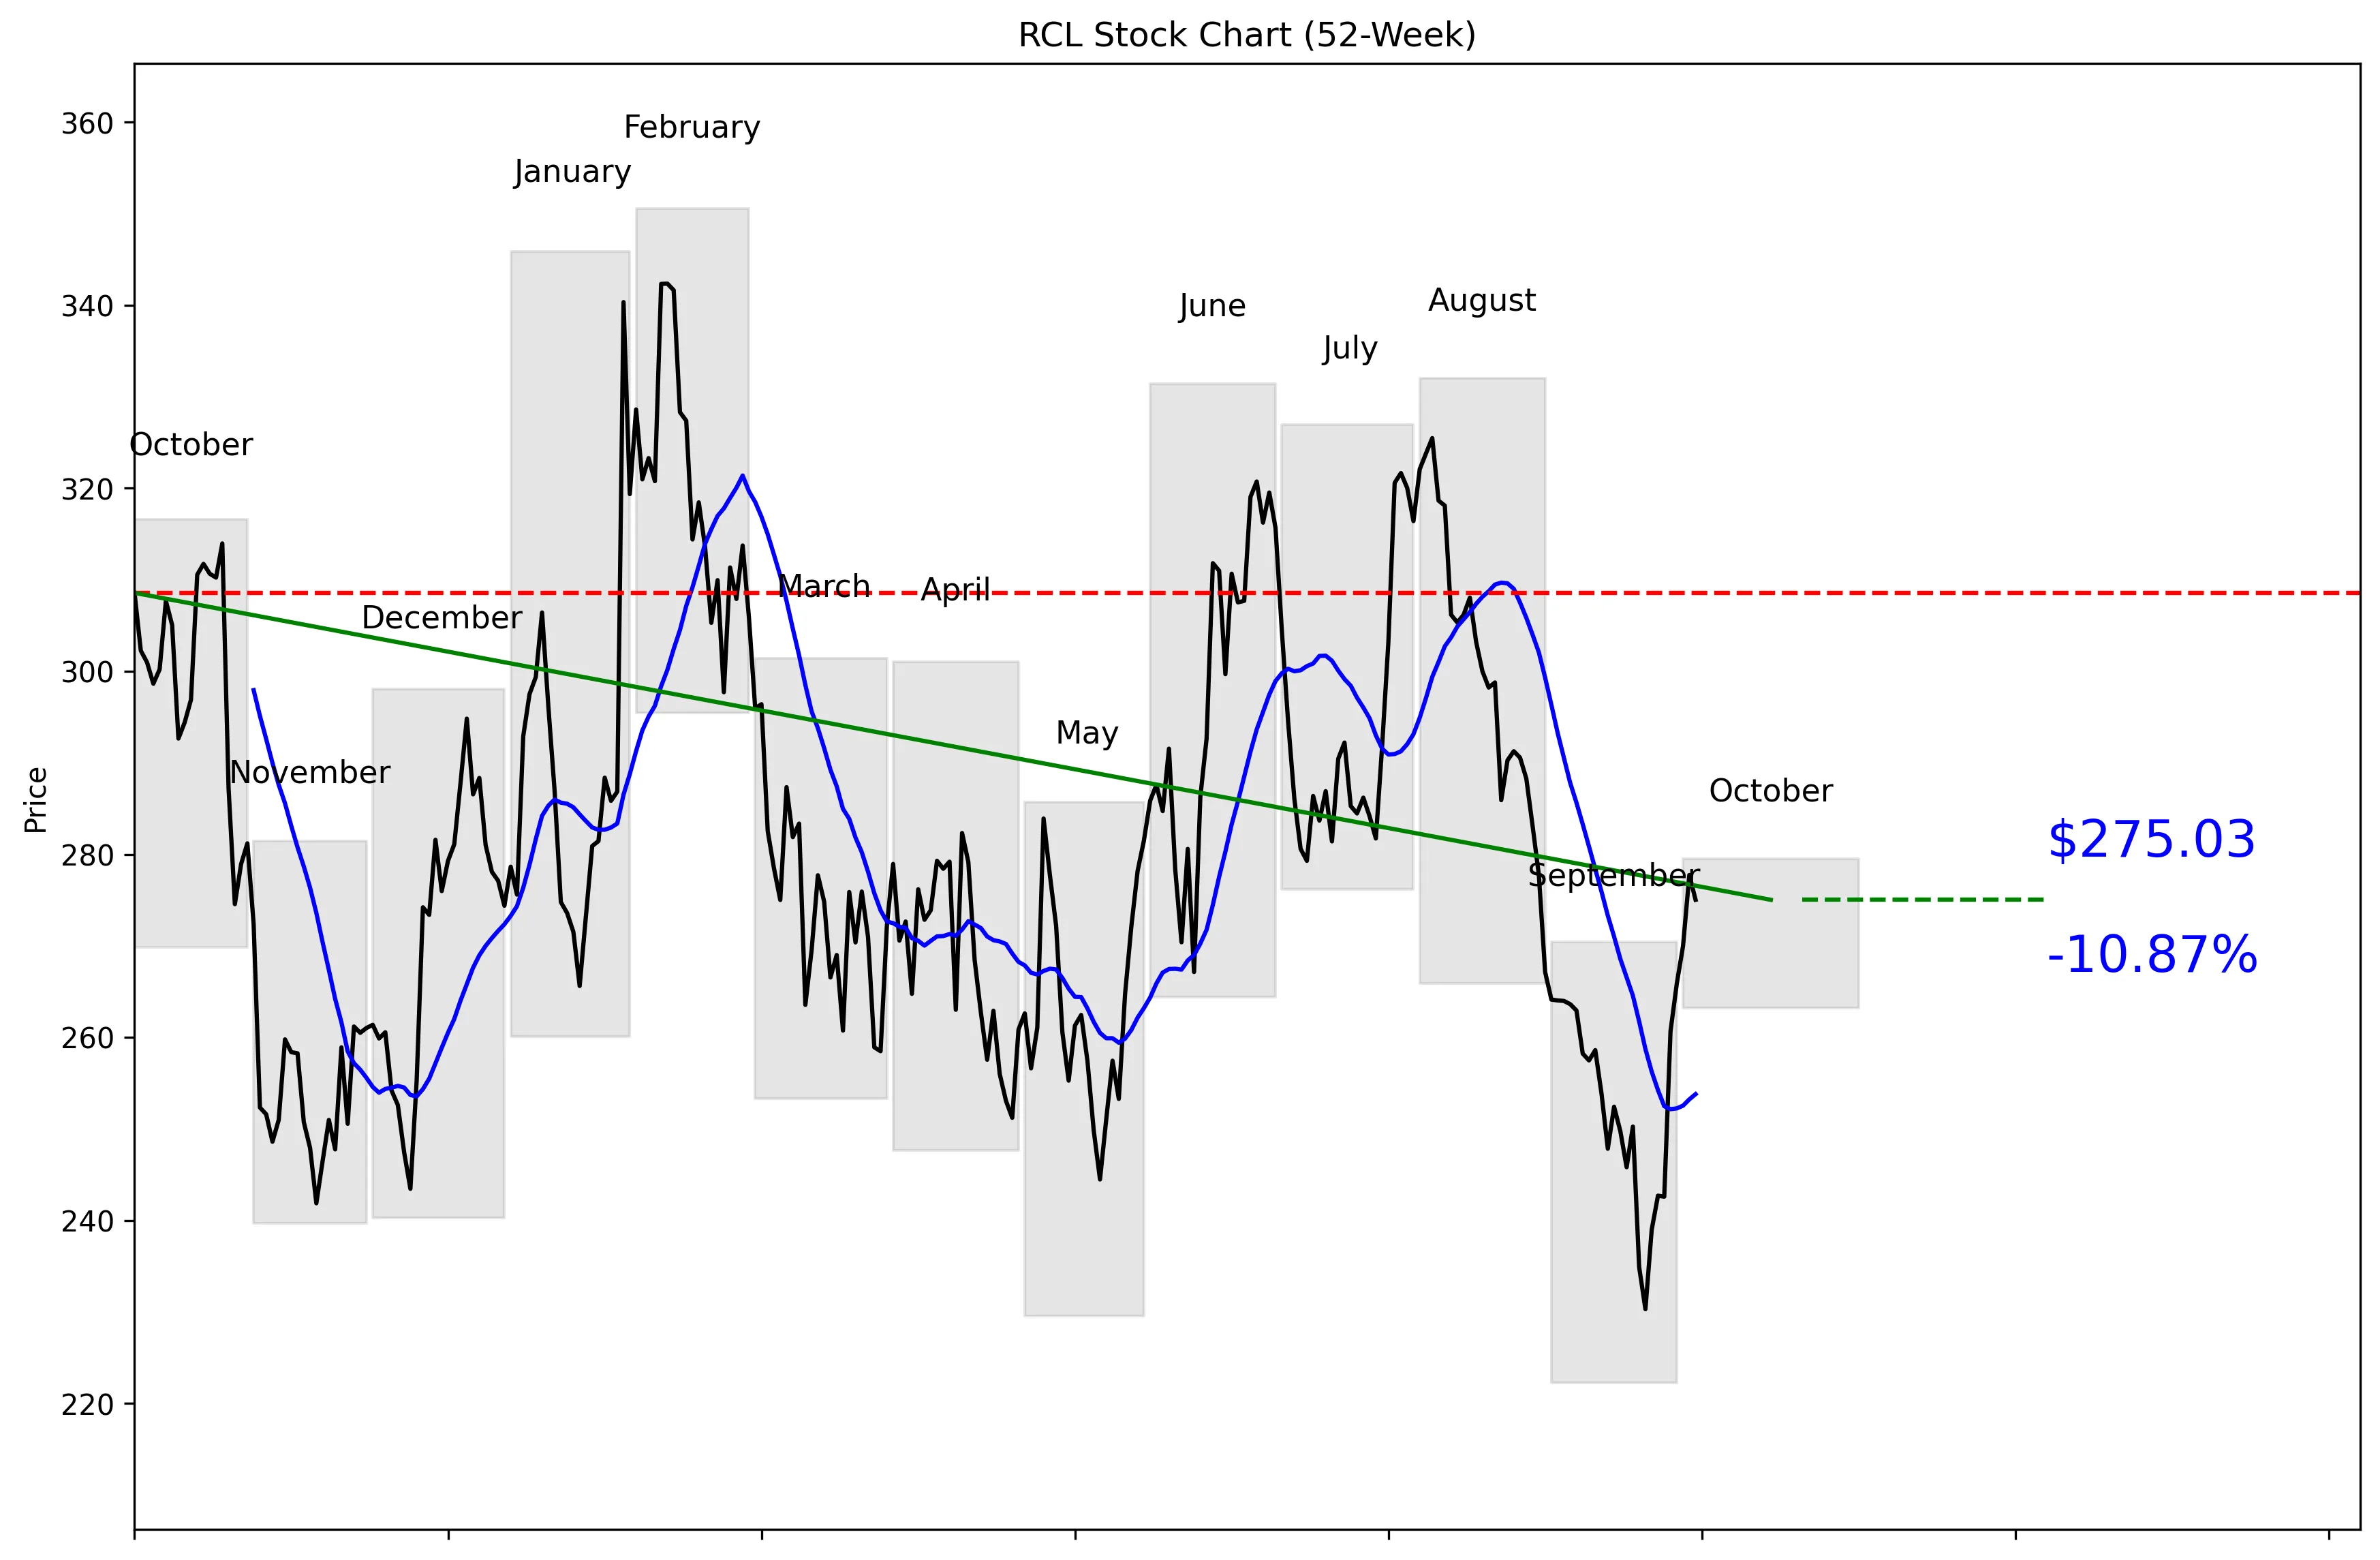
Bank of America upgraded Royal Caribbean from Neutral to Buy on September 28 and maintained a $330 price target. Analyst Andrew Didora argued that the shares had become too cheap after falling nearly 26% in less than two months. Source: Benzinga
Deutsche Bank upgraded Royal Caribbean from Hold to Buy on September 28 while keeping its $299 price target. That target represented 23% upside from the September 25 closing price of $242.70. Source: The Fly via TipRanks
RCL rallied on September 29 after Carnival reported adjusted quarterly earnings of $1.43 per share, beating the $1.36 consensus, and raised full-year adjusted EPS guidance to approximately $2.24. Royal Caribbean closed that session at $260.67, up 7.45%. Source: Benzinga
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports