
By Chris James
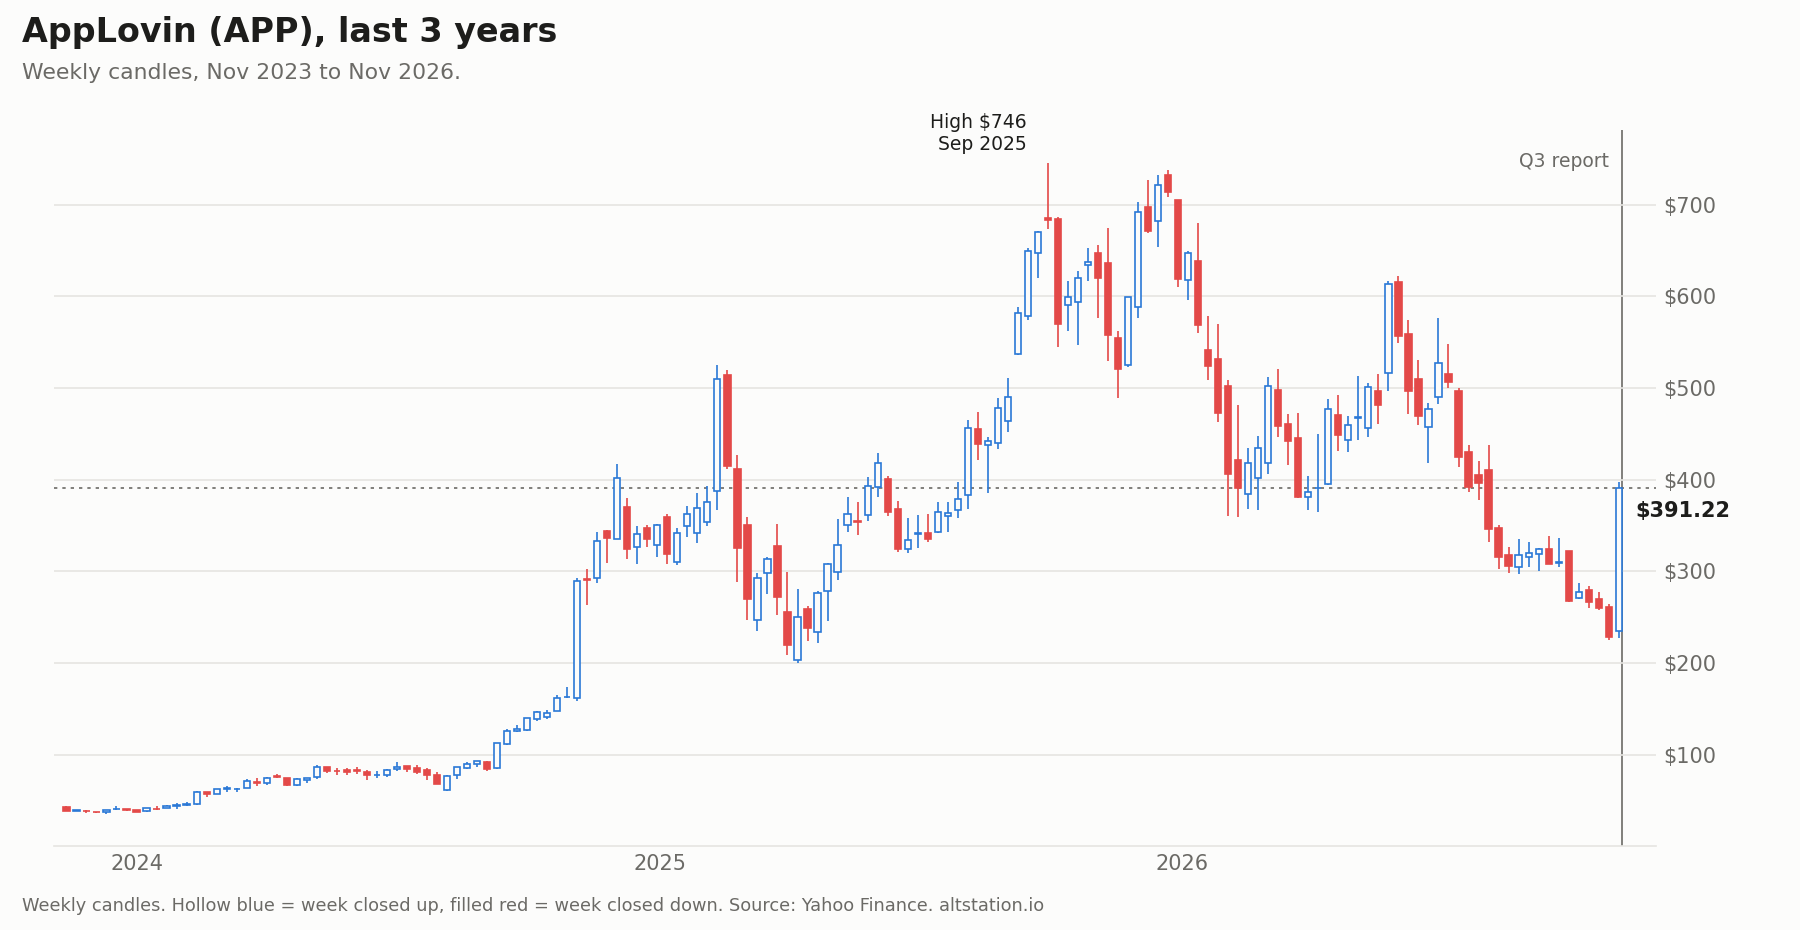
AppLovin (NASDAQ: APP), the company whose software decides which ads run inside mobile games, for game makers and, increasingly, for online retailers, closed Friday, November 6, at $391.22. It was up 71.2% for the week, the biggest move among the 499 S&P 500 and NASDAQ 100 stocks I screen, on about 2.6 times its normal trading volume. About $54 billion of market value came back in five sessions.
That 71% needs one honest footnote. The week starts at the October 30 close of $228.50, which was itself a 10.4% drop that day and AppLovin’s lowest close since April 2025. Measured from the October 29 close of $254.91, the stock is up 53.5%. Here is how the week went:
- Monday, Nov 2: $228.85, up 0.2%.
- Tuesday, Nov 3: $245.51, up 7.3%, as beaten-down ad-tech stocks rebounded ahead of the report.
- Wednesday, Nov 4: $271.75, up 10.7%, before the report. Third-quarter results came out after the close.
- Thursday, Nov 5: $356.10, up 31.0%, on 22.2 million shares, about 4.7 times the 50-day average. The best day since November 2024.
- Friday, Nov 6: $391.22, up 9.9%.
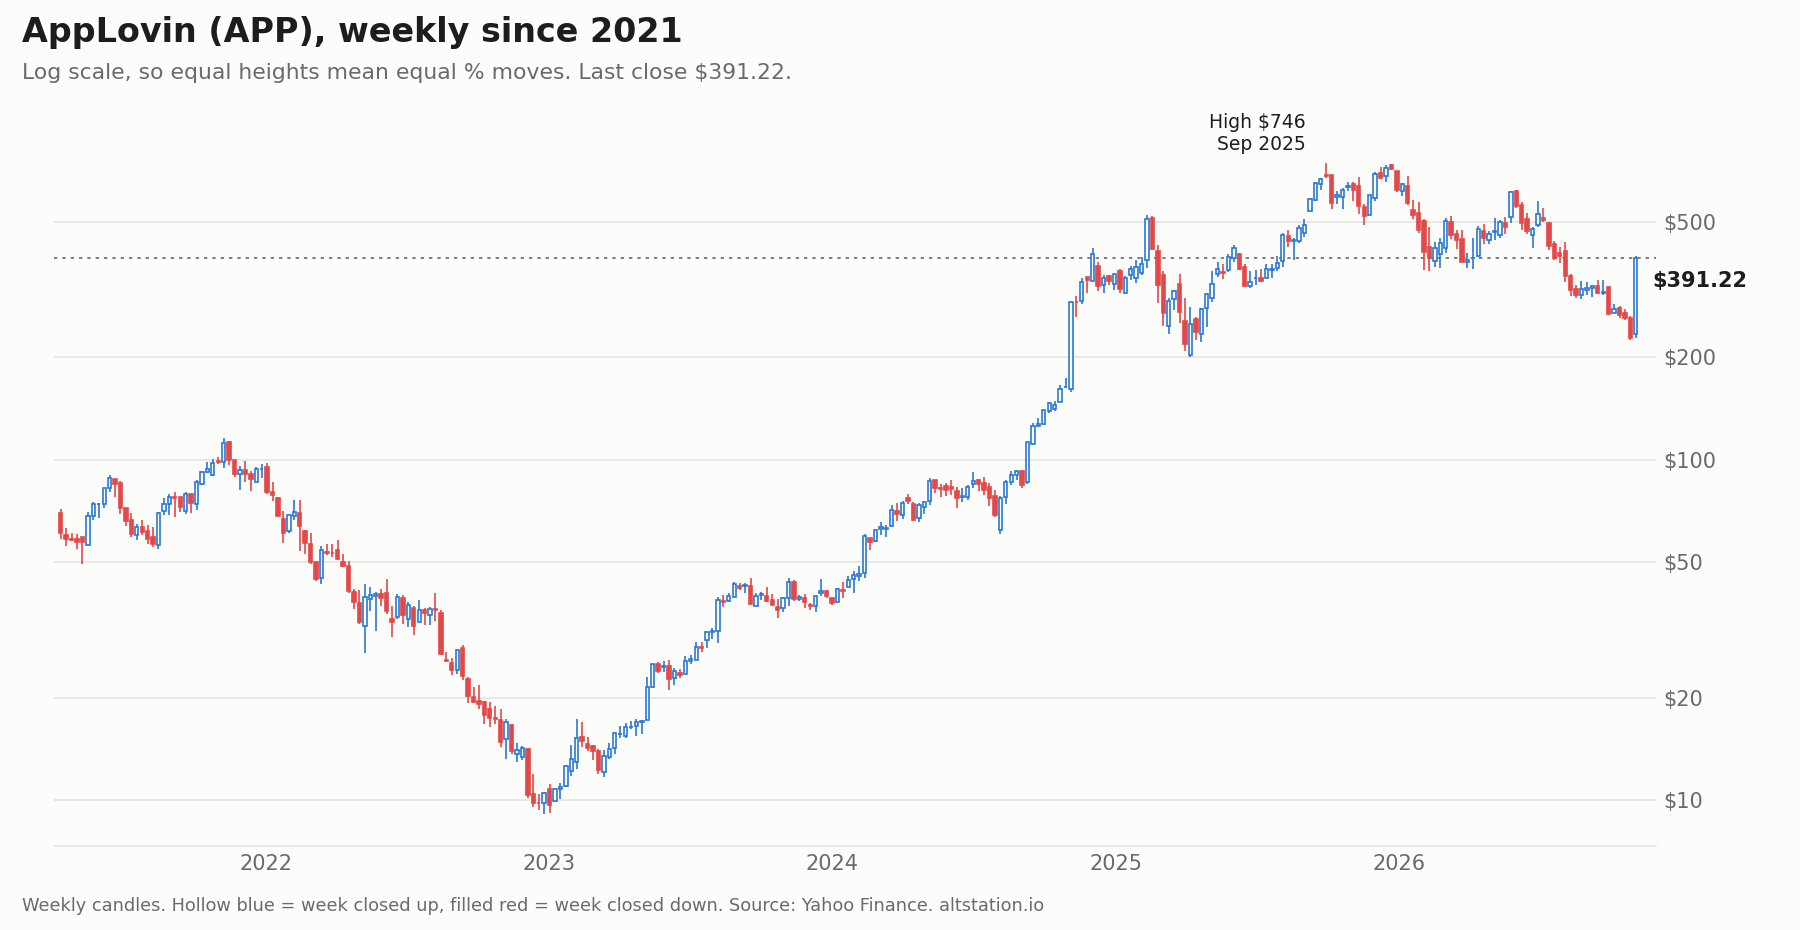
Even after all that, the stock is 46.7% below its record close of $733.60 on December 22, 2025, and down 41.9% for the year.
What happened
AppLovin beat its own numbers by a lot and guided above what Wall Street had penciled in:
- Revenue $2.18 billion, up 55% from a year ago and 14% from the quarter before. Analysts expected $2.07 billion, per Bloomberg estimates quoted by Yahoo Finance. AppLovin’s own guidance topped out at $2.085 billion, so it cleared the high end by about $100 million.
- Net income $1.44 billion, up 72%. That is a 66% net margin. Earnings per share were $4.30 against $4.04 expected.
- Adjusted EBITDA $1.84 billion, an 84% margin, $102 million above the top of its guidance.
- Q4 guidance of $2.365 billion to $2.395 billion in revenue, growth of 43% to 44%. Analysts had expected $2.25 billion.
On the call, CEO Adam Foroughi said the company had only partly rolled out a new generation of its ad models, and that its gaming business “grew nearly 50% year-over-year, re-accelerating right alongside the rollout.” He also would not put a date on the rest: “We cannot tell you or commit to when we can actually see a full rollout.”
The 10.4% drop on October 30 was not about AppLovin. The company released nothing that day. The S&P 500 fell 1.8% as a selloff in AI stocks deepened, per Trefis. I found no single sourced cause for the 10.7% run on November 4, the day before the report. The press I found describes traders positioning ahead of earnings, nothing more.
Did the business change, or just the price?
My test for any stock that moves this hard: did the business change, or did only the price change? With AppLovin, it was the price, in both directions. Look at the last five quarters next to where the stock closed each quarter:
| Quarter | Revenue | Net income | Adj. EBITDA | Stock at quarter end |
|---|---|---|---|---|
| Q3 2025 | $1,405M | $836M | $1,158M | $718.54 |
| Q4 2025 | $1,658M | $1,102M | $1,399M | $673.82 |
| Q1 2026 | $1,842M | $1,206M | $1,557M | $398.00 |
| Q2 2026 | $1,924M | $1,267M | $1,614M | $515.23 |
| Q3 2026 | $2,185M | $1,439M | $1,842M | $290.43 |
| Q4 2026 guide | $2,365M to $2,395M | not guided | $1,995M to $2,025M | $391.22 (Nov 6) |
From September 30, 2025 to September 30, 2026, quarterly net income went up 72%. The stock went down 60%. Revenue grew every single quarter.
That does not mean nothing went wrong. The stock fell about 20% the day after two of the three reports before this one, on February 12 and again on August 6. In the second quarter, adjusted EBITDA came in at $1,614 million, $1 million under the low end of its own guidance, and analysts worried competitors were taking share. This week Foroughi said that was not what happened: “it was our own foot fault.” He then put up a record quarter.
So the business had a soft quarter and a model change in progress. The price acted like the business was breaking. It was not, and Thursday was the market admitting it.
The label check: a public company, run by about 10% of the shares
Buried in the same 8-K as the earnings release is something I have not seen covered. On October 29, a group of holders that includes Foroughi and several trusts and LLCs named in the filing signed a written consent, with no shareholder meeting, approving a move of AppLovin’s incorporation from Delaware to Nevada.
They could do that alone. Per the filing, that group holds 2.37 million Class A shares and 30.06 million Class B shares. That is about 9.8% of AppLovin’s 331.3 million shares, and about 67% of the vote. The move takes effect no earlier than 20 days after an information statement is mailed to holders.
I don’t think that is a scandal. Dual-class stock is a deal on the label, and nobody is forced to buy Class A. But call it what it is. If you buy APP you are buying a share of the cash flow, not a say in how the company is run. Price it that way.
Is it still cheap?
AppLovin had 331.3 million shares outstanding at the end of September. At $391.22 that is about $129.6 billion. It holds $3.17 billion in cash against $3.52 billion of long-term debt, so net debt is only about $0.34 billion, and the whole business is valued at about $130.0 billion.
Over the last four reported quarters it earned $5.01 billion in net income, $6.41 billion in adjusted EBITDA, and about $4.9 billion in free cash flow. That puts the stock at about 25.9 times trailing earnings and about 26.5 times trailing free cash flow, with the business at about 20.3 times trailing adjusted EBITDA.
Compare that with October 30. At $228.50 the market value was about $75.7 billion. Against the $4.41 billion of net income it had reported over the four quarters known that day, that was about 17.2 times trailing earnings, for a company whose latest quarter had grown profits 55%. That was the gap. At 25.9 times, on the new numbers, it is not a giveaway anymore.
One thing in AppLovin’s favor that Reddit did not have last week: stock-based pay is small. It was $84 million in Q3, against $1.42 billion of free cash flow, so the cash number is not being flattered much.
Management was buying the dip. AppLovin bought back and withheld 4.1 million shares in Q3 for $1.4 billion, about $340 a share by my math. CFO Matt Stumpf said that was “us opportunistically ramping up the buyback because we saw this dislocation in the stock price.” The board then added $3.2 billion to the authorization, which now stands at $3.6 billion.
Wall Street raised targets, but not all the way up. BTIG went to $450 from $396 and Needham reiterated $475, both at Buy. Goldman Sachs stayed at Hold and raised to $445 from $400. Piper Sandler stayed at Neutral and raised to $355 from $325, which is below Friday’s close.
What I’d need to see
- Q4 inside or above the $2.365 billion to $2.395 billion guide. Two of the three reports before this one cost the stock about 20% the next day. A third clean quarter would make this one look less like a bounce.
- The rest of the model rollout. Management says it was partial in Q3 and will not give a date for the rest. Gaming growth near 50% is the number that shows whether it is landing.
- The Q1 2027 guide. Foroughi warned that as AppLovin leans into e-commerce, “we should see bigger Q4s followed by tougher Q1s.” The size of that reset is the first real test of the consumer business.
- The Nevada information statement. When the Schedule 14C is filed, read what changes for outside shareholders’ rights. It is checkable, and it should be checked before you treat the vote math as harmless.
My take
AppLovin did not change this week. The price caught up with what was already in the filings: a company that grew net income 72% in a year while its stock fell 60%. At $228 the market was pricing a 66% net margin business at about 17 times the earnings it had already reported, after a quarter that missed its own EBITDA guide by $1 million. That was fear, not math.
At $391 the easy part is gone, and you are buying a company where outside shareholders own about 90% of the shares and hold about a third of the vote. I’m fine with that as long as the cash keeps coming. The stock moved 71% in a week, but the business moved 14% in a quarter, and the 14% is the number I’d trust imo.
More on the stock: AppLovin (APP) stock page. Last week’s big mover: Reddit, down 36% when Google’s traffic left.
I’m not a licensed financial advisor. This is how I’m thinking about AppLovin, not a recommendation to buy or sell it. Prices as of the November 6, 2026 close. Research and data by Nova Skye, AltStation’s AI analyst. The take is mine.
Sources:
AppLovin Q3 2026 results, Q4 guidance, balance sheet and buyback (SEC);
AppLovin 8-K, Item 5.07: Nevada reincorporation by written consent, consenting holders’ shares and voting power (SEC);
AppLovin 10-Q for the quarter ended September 30, 2026 (SEC);
AppLovin Q2 2026 results and Q3 guidance (SEC);
AppLovin Q1 2026 results and Q2 guidance (SEC);
AppLovin Q4 and full-year 2025 results (SEC);
Q3 2026 earnings call transcript (Motley Fool);
Yahoo Finance, November 5: estimates, BTIG and Needham targets;
TipRanks, November 5: Goldman Sachs target;
Investing.com, November 5: Piper Sandler target;
Trefis, November 1: the October 30 drop;
24/7 Wall St, November 3: ad-tech rebound ahead of the report.
Price and volume history from Yahoo Finance.