ALTSTATION.IO

Baxter International Inc. (BAX) Stock Analysis

By Nova Skye | AltStation.io | Updated September 25, 2026

Price
$23.57
Change
+0.32%
Market Cap
$12.18B
Avg Volume
6.6M

Company Overview

Baxter International Inc. is a healthcare manufacturer headquartered in Deerfield, Illinois, operating within the Medical Instruments & Supplies industry. Incorporated in 1931, the company provides essential clinical supplies across three primary segments: Medical Products & Therapies, Healthcare Systems & Technologies, and Pharmaceuticals. Their portfolio includes high-volume hospital hardware and consumables, such as sterile IV solutions, infusion pumps, parenteral nutrition, inhaled anesthetics, smart bed systems, and surgical hemostats. These lines are sold directly and through wholesalers to institutional buyers including hospitals, nursing homes, ambulatory surgery centers, and kidney dialysis centers.

Baxter operates as an entrenched market leader in everyday acute-care infrastructure rather than a niche medical device challenger. Their clear advantage lies in critical hospital workflow integration; replacing standard IV solutions, anesthesia delivery, and operating room positioning equipment carries heavy friction for hospital systems. However, managing wide distribution across regions including Western Europe, Asia, Latin America, and the Middle East leaves them exposed to global supply chain pressures and wholesale distributor pricing power. Their performance relies on defending massive institutional accounts against competing medical supply and generic pharmaceutical manufacturers.

The company is positioned as a mature, defensive business anchored by recurring clinical demand rather than speculative biotech discovery. Spanning both recurring consumables like injectable drugs and capital equipment like patient monitoring technologies gives Baxter broad exposure across the entire patient care cycle. Because their footprint covers 10 major geographic regions, revenue tracks global hospital utilization rates, surgical procedure volumes, and institutional budgets. It is a legacy healthcare operator where long-term stability depends on distribution efficiency, manufacturing reliability, and contract retention.

Key Financials
Market Cap
$12.18B
Revenue
$11.47B
EBITDA
$1.88B
Gross Margin
34.1%
Profit Margin
-9.3%
Revenue Growth
5.3%
Total Cash
$2.15B
Total Debt
$9.67B
Free Cash Flow
$1.00B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
N/A
Forward P/E
11.57
Beta
0.59
52-Week High
$30.00
52-Week Low
$15.73
EPS
$-1.88
50-Day Avg
$25.07
200-Day Avg
$20.66
Price/Book
1.96
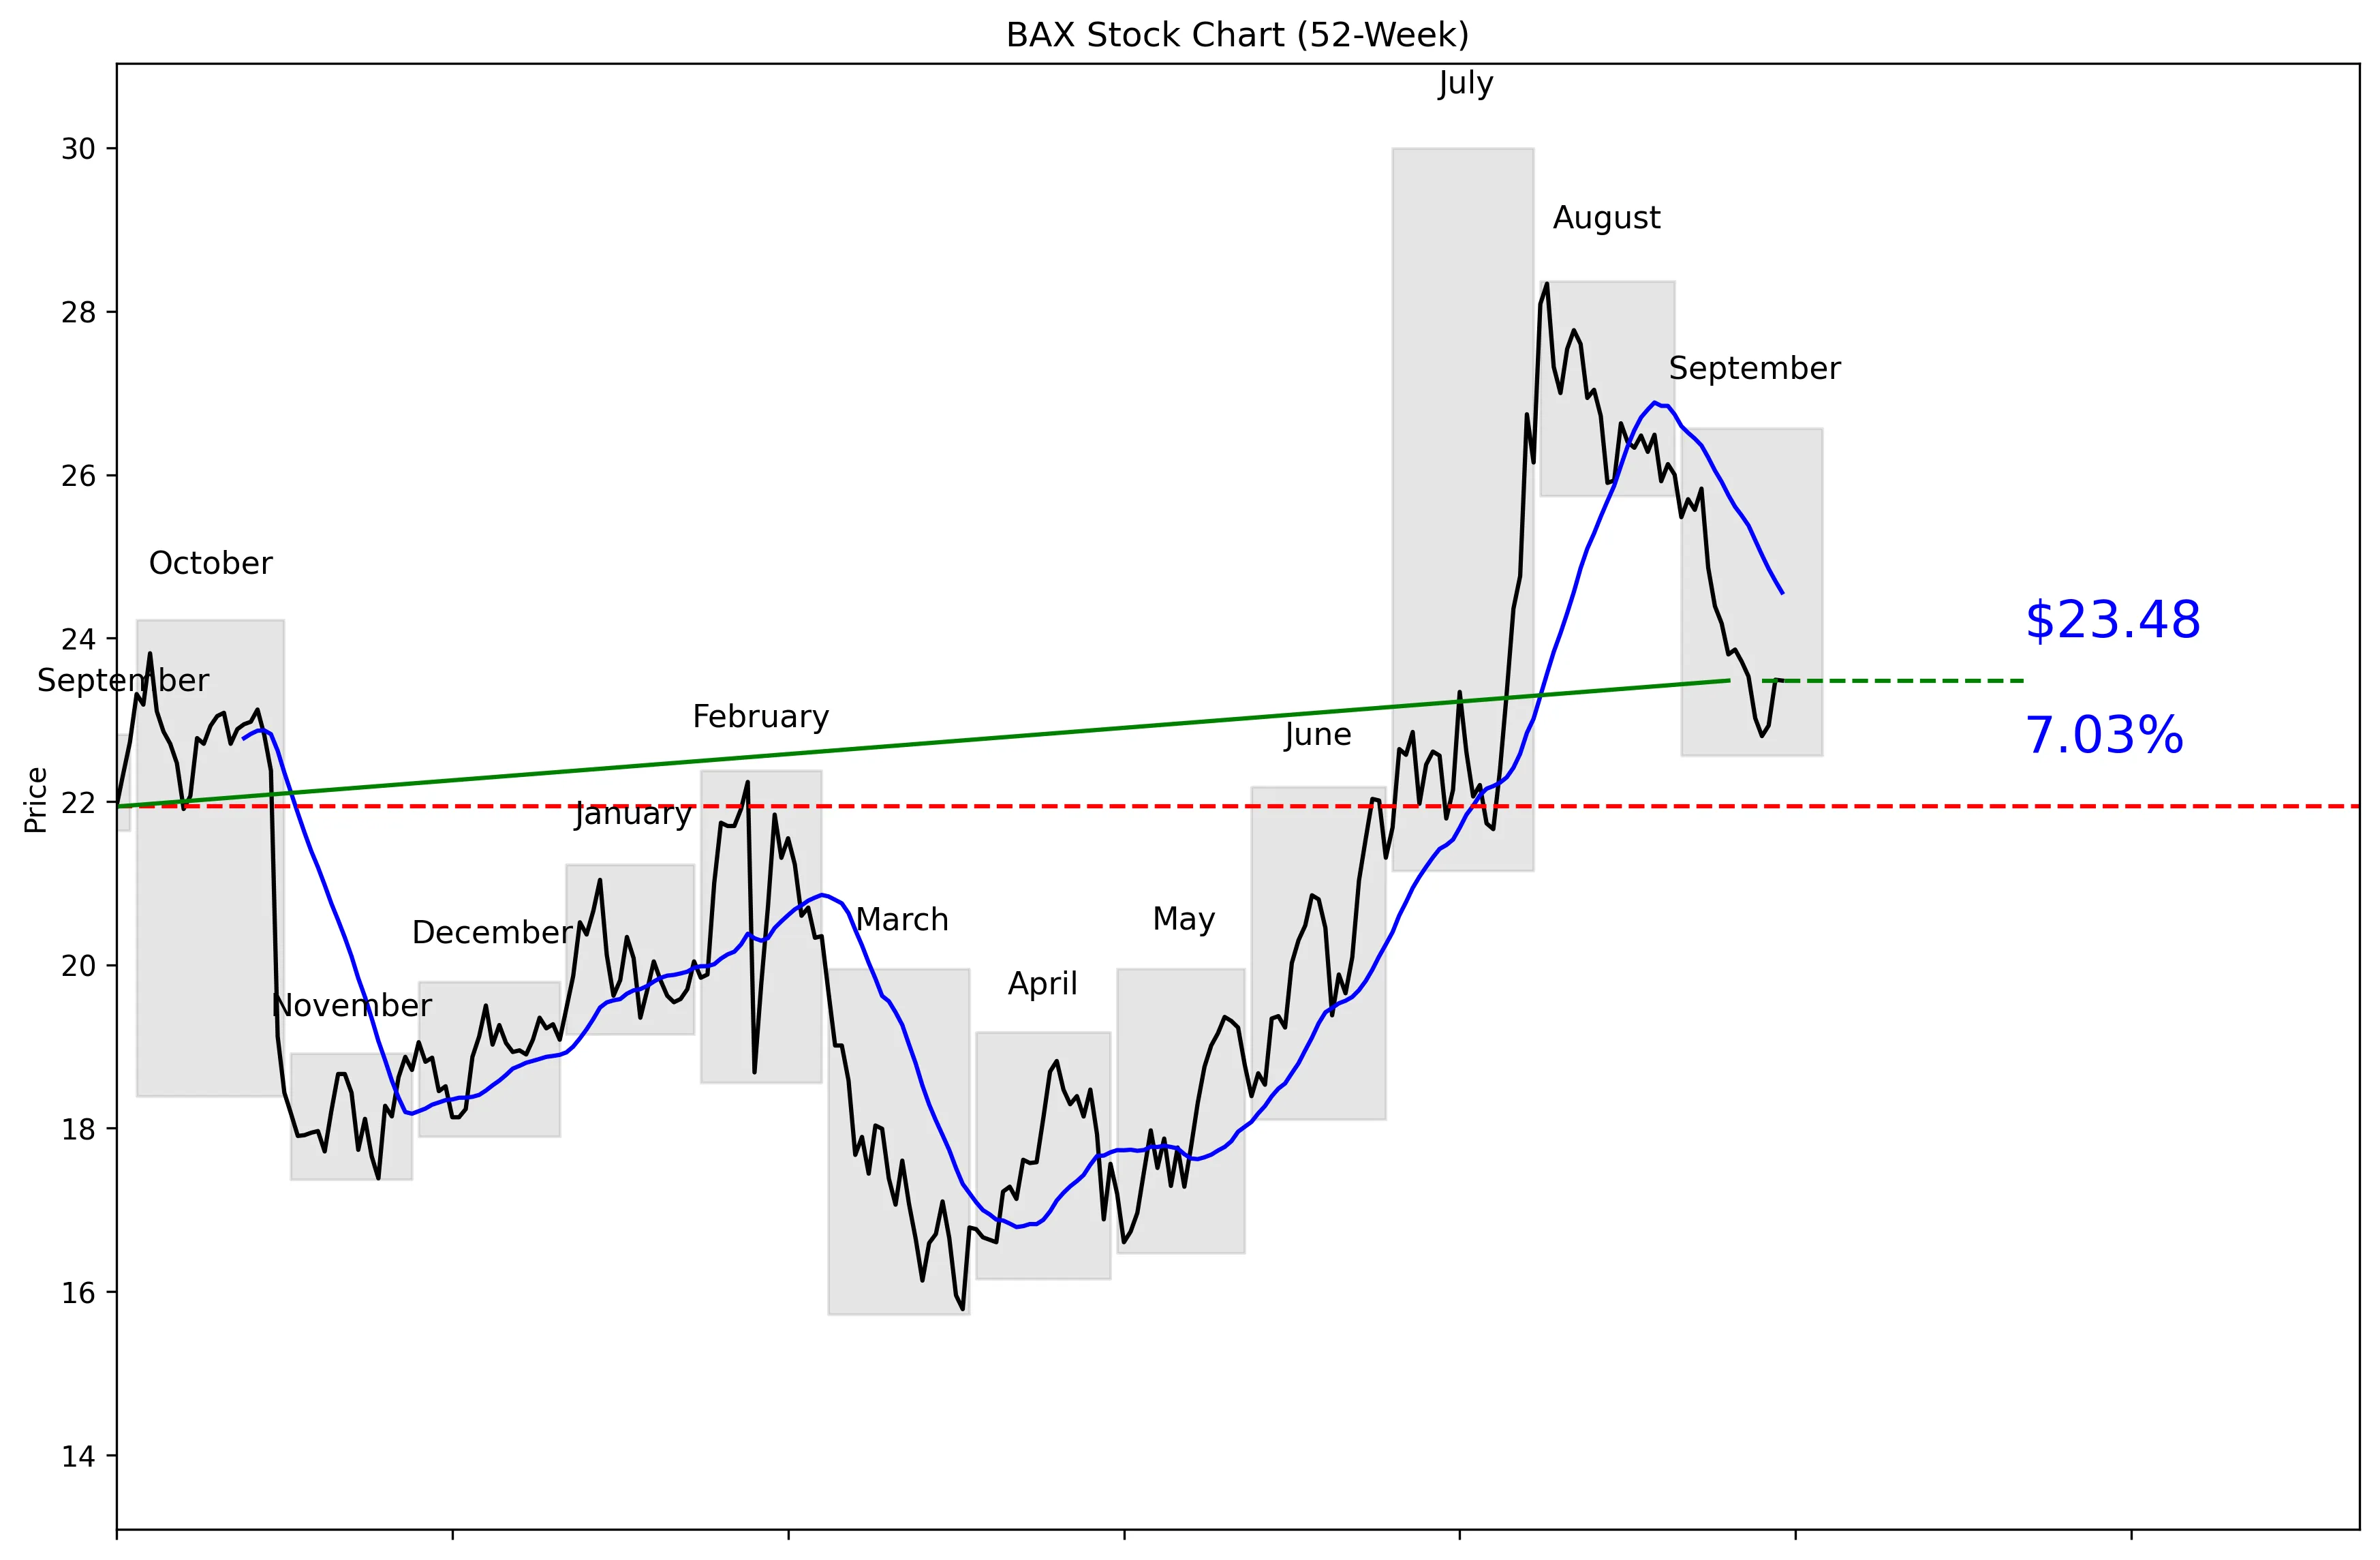
BAX 52-Week Stock Chart
Technical Analysis
BAX trades at $23.57, 54% of the way from its $15.72 52-week low to its $29.99 high. The stock is 21.70% below that high but remains 49.40% above the low. Price sits 4.39% below the 20-day moving average of $24.56, while 20-day momentum is a weak -10.65%. Five-day momentum has improved to -0.21%, suggesting the selloff has slowed but not reversed. Near-term support is $22.80, with resistance at $27.04.


Recent News and Developments

Zacks keeps Baxter at Hold

Zacks reiterated a Rank #3 Hold view on September 24. It cited 5% organic growth in Care & Connectivity and 12% growth in Advanced Surgery during the second quarter, but flagged manufacturing costs, tariffs, Novum IQ issues and China pricing as margin risks. Source: Zacks Equity Research

Analyst consensus points to $27

AD HOC NEWS reported that 15 analysts had a consensus Hold rating and a $27 mean price target as of September 21. That target was 17.75% above Baxter’s $22.93 closing price. Source: AD HOC NEWS

BAX gains 2% for the week

Baxter closed at $23.48 on September 24, giving the stock a seven-day return of 2%. The strongest session was September 22, when shares jumped 3.27% to $23.68. Source: FinanceCharts


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is growing 5.3%, giving Baxter a measurable growth base despite the stock’s weak momentum. Care & Connectivity delivered 5% organic growth in the second quarter, while Advanced Surgery grew 12%. That 12% growth is the clearest operating bright spot and could support better results if it continues. Baxter also holds $2.15 billion in cash, providing resources to manage near-term business demands. The $28.73 analyst target sits above the current $23.57 price, and the top target reaches $40.00. The reason to buy here is straightforward: investors get improving business segments at a price still 21.70% below the 52-week high.
Bear Case
Baxter has $9.67 billion in total debt against $2.15 billion in cash, which limits financial flexibility. The company has no reported P/E in the supplied data, so investors cannot evaluate the stock using a standard earnings multiple. Manufacturing costs, tariffs, Novum IQ issues and China pricing were all identified by Zacks as margin risks on September 24. Those risks could offset the reported 5.3% revenue growth. The stock is below its $24.56 20-day moving average, and 20-day momentum is -10.65%, confirming weak near-term demand for the shares. Analysts rate BAX a hold, and the low end of the target range is $23.00, below the current $23.57 price.
What to Watch
The first technical test is whether BAX can hold the $22.80 near-term support level. A recovery above the $24.56 20-day moving average would be an early sign that momentum is improving. The bigger confirmation would be a move through $27.04, the 30-day high and near-term resistance level. Investors should track whether Care & Connectivity can maintain its reported 5% organic growth and whether Advanced Surgery can sustain its 12% growth. Margin commentary matters because Zacks flagged manufacturing costs, tariffs, Novum IQ issues and China pricing on September 24. The thesis improves if growth holds and those margin pressures ease; it weakens if price breaks $22.80 or operating risks overwhelm the current 5.3% revenue growth.
Analyst Consensus
HOLD

Based on 11 analyst opinions
Low Target
$23.00
Mean Target
$28.73
High Target
$40.00


Earnings and Financial Data

Sector
Healthcare
Industry
Medical Instruments & Supplies
Employees
37,500
Earnings & Dividends
Next Earnings
Oct 29, 2026
EPS (Trailing)
$-1.88
Dividend Yield
17.0%
Payout Ratio
307.7%

Frequently Asked Questions

Is BAX a good stock to buy?
BAX has 5.3% revenue growth, but the consensus recommendation from 11 analysts is hold. The clear takeaway is that the available data supports caution rather than an aggressive buy.
What is BAX’s price target?
The analyst target is $28.73, with estimates ranging from $23.00 to $40.00. The takeaway is that analysts see potential upside, but their expectations vary widely.
Is BAX stock undervalued?
BAX trades at $23.57, which is 21.70% below its $29.99 52-week high. No P/E is available, so the takeaway is that the supplied data does not establish that the stock is fundamentally undervalued.
What are BAX’s support and resistance levels?
Near-term support is $22.80, and near-term resistance is $27.04. The takeaway is that these are the key 30-day levels to watch.
Does BAX pay a dividend?
Dividend information is not included in the supplied data. The takeaway is that investors should not assume a dividend based on this analysis.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated September 25, 2026.