ALTSTATION.IO

Garmin Ltd. (GRMN) Stock Analysis

By Nova Skye | AltStation.io | Updated September 21, 2026

Price
$272.75
Change
-0.94%
Market Cap
$52.60B
Avg Volume
919.2K

Company Overview

Garmin Ltd. is a Schaffhausen, Switzerland-based company operating in the Technology sector under Scientific and Technical Instruments. Founded in 1989, the company builds and sells specialized GPS-enabled hardware, sensor systems, and navigation software across consumer and commercial markets. Its product lineup spans fitness smartwatches, cycling computers, and outdoor satellite communicators for athletes and adventurers, alongside integrated flight decks and avionics for aircraft. It also supplies chartplotters, sonar, and radar systems to marine operators, as well as domain controllers and infotainment units to automotive manufacturers. Distribution runs directly to end users via online webshops and through a global network of dealers, independent retailers, and original equipment manufacturers.

Garmin is a dominant niche leader in premium performance wearables and a certified standard in marine and general aviation navigation. The company maintains its edge through vertical integration, designing proprietary software and managing manufacturing to sustain gross margins around 58 to 59 percent. While consumer tech giants like Apple and Samsung pressure the entry-level smartwatch market, Garmin protects its turf by targeting dedicated athletes, pilots, and mariners who require multi-week battery life and specialized telemetry. Strict regulatory certifications in aviation and deep OEM partnerships in marine and automotive create high barriers to entry that keep mass-market tech competitors from encroaching.

Garmin is in a clear expansion phase, generating record consolidated revenue of 6.30 billion dollars in fiscal 2024, a 20 percent increase over 2023, followed by 7.25 billion dollars in 2025, representing 15 percent annual growth. Growth has been broad-based across all five reporting segments, led by Fitness as the primary growth engine while the Marine unit surpassed 1 billion dollars in revenue for the first time in 2024. Strategically, the company is compounding its hardware sales with recurring data subscriptions on the Garmin Connect platform and fulfilling a growing Auto OEM backlog for luxury European cockpits. Garmin has built an exceptionally resilient, high-margin cash generator that continues to out-execute typical consumer electronics makers.

Key Financials
Market Cap
$52.60B
Revenue
$7.67B
EBITDA
$2.31B
Gross Margin
60.1%
Profit Margin
24.5%
Revenue Growth
11.4%
Total Cash
$2.67B
Total Debt
$226.86M
Free Cash Flow
$1.04B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
28.15
Forward P/E
24.78
Beta
0.87
52-Week High
$314.28
52-Week Low
$186.67
EPS
$9.69
50-Day Avg
$278.42
200-Day Avg
$241.77
Price/Book
5.83
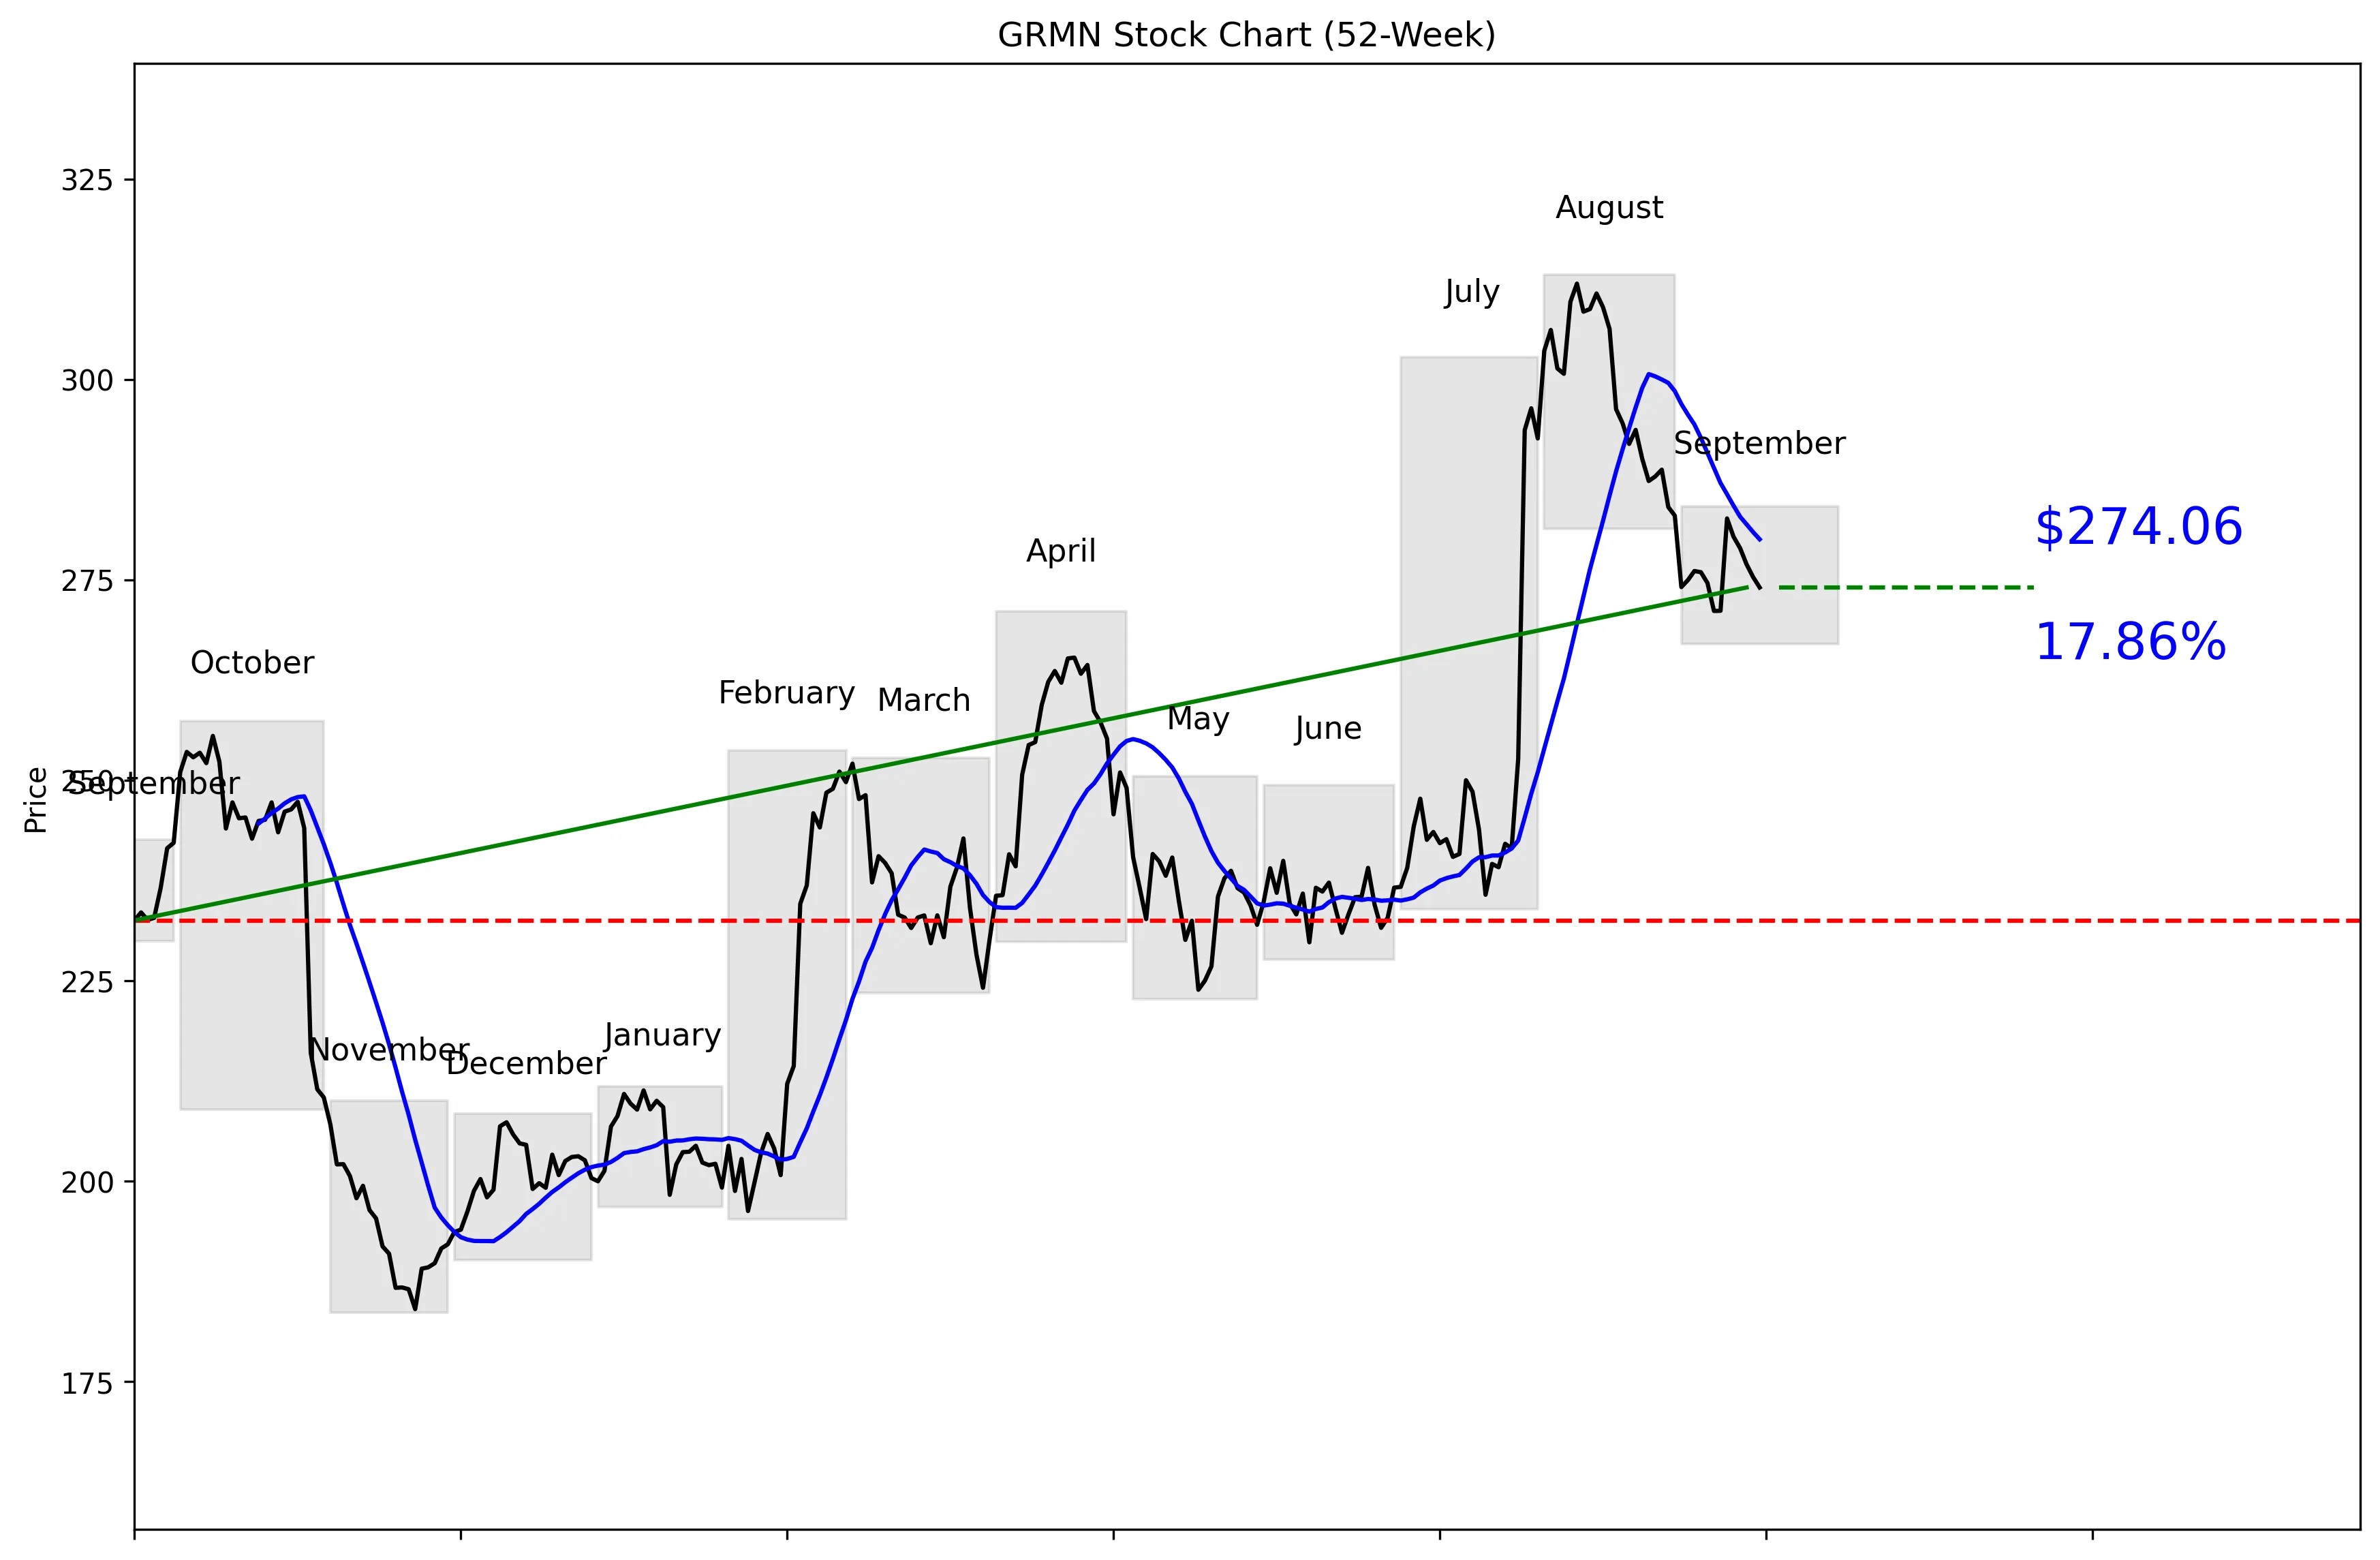
GRMN 52-Week Stock Chart
Technical Analysis
GRMN trades at $272.75, 70% of the way from its $183.64 52-week low to its $313.07 high. The stock is 12.46% below that high but remains 49.24% above the low. Price sits 2.15% below the 20-day moving average of $280.07, while momentum is negative at 3.05% over five trading days and 6.13% over 20 trading days. Near-term support is $271.13, just below the current price. Near-term resistance is $311.95, leaving a wide gap that buyers must close before the technical picture improves.


Recent News and Developments

Zacks upgrades Garmin to Strong Buy

Zacks raised Garmin to Rank #1, or Strong Buy, on September 16 after earnings estimates moved higher. Its consensus estimate increased 5.7% over the prior three months, putting GRMN in the top 5% of more than 4,000 Zacks-covered stocks. Source: Zacks Equity Research

GRMN loses 3.05% for the week

Garmin closed at $274.06 on September 18, down 0.47% for the session and 3.05% over seven days. Trading volume reached 2,422,204 shares on September 18, versus a one-month average of 917,472. Source: FinanceCharts

Garmin reports 1.1 million active users in Indonesia

Garmin said on September 14 that it had surpassed 1.1 million active users in Indonesia. The company also reported more than 13 million users across Asia and roughly 62 million worldwide, showing meaningful scale for its wearable ecosystem. Source: Garmin Indonesia


Market Sentiment and Analyst Recommendations

Bull Case
Revenue reached $7.67 billion and is growing 11.4%, giving Garmin a solid fundamental base. The balance sheet is a major strength, with $2.67 billion in cash against just $226.86 million in debt. Garmin also has meaningful ecosystem scale, reporting roughly 62 million users worldwide, more than 13 million across Asia and 1.1 million active users in Indonesia. Zacks upgraded GRMN to Strong Buy on September 16 after its consensus estimate rose 5.7% over three months. The $290.29 analyst target represents upside from the current $272.75 price, while the high estimate reaches $370.00. The bull case is straightforward: double-digit revenue growth, low debt and rising earnings expectations justify buying weakness if operational momentum continues.
Bear Case
GRMN is not cheap at 28.15 times earnings. The broader analyst recommendation is hold across seven analysts, so Wall Street is less aggressive than the Zacks upgrade suggests. The analyst target range runs from $220.00 to $370.00, showing major disagreement about fair value. Technical momentum is also weak, with the stock down 3.05% over five trading days and 6.13% over 20 trading days. Price is only $1.62 above the $271.13 near-term support level, so that floor is already under pressure. GRMN needs its 11.4% revenue growth to remain strong because a premium valuation leaves less room for disappointing results.
What to Watch
The first threshold is $271.13, the 30-day low and immediate support level. A sustained move below it would confirm that the recent 3.05% five-day and 6.13% 20-day declines still have control. Bulls need GRMN to reclaim its $280.07 20-day moving average before the short-term setup improves. Beyond that, $311.95 is the key resistance level, sitting close to the $313.07 52-week high. Investors should monitor whether the 5.7% increase in Zacks’ consensus estimate after its September 16 upgrade continues or reverses. They should also track whether revenue growth holds near 11.4% and whether Garmin expands beyond its reported 62 million worldwide users. The thesis improves above the moving average with sustained revenue growth; it weakens below support or if estimate momentum fades.
Analyst Consensus
HOLD

Based on 7 analyst opinions
Low Target
$220.00
Mean Target
$290.29
High Target
$370.00


Earnings and Financial Data

Sector
Technology
Industry
Scientific & Technical Instruments
Employees
23,000
Earnings & Dividends
Next Earnings
Oct 28, 2026
EPS (Trailing)
$9.69
Dividend Yield
153.0%
Payout Ratio
38.7%

Frequently Asked Questions

Is GRMN a good stock to buy?
GRMN combines 11.4% revenue growth with $2.67 billion in cash and only $226.86 million in debt, but it trades at a P/E of 28.15. The seven-analyst recommendation is hold, so the takeaway is that the fundamentals are strong but the current valuation demands continued growth.
What is GRMN’s price target?
The analyst target is $290.29, with estimates ranging from $220.00 to $370.00. The takeaway is that analysts see some upside from $272.75, but the wide range signals substantial uncertainty.
Is GRMN overvalued?
GRMN trades at 28.15 times earnings while revenue is growing 11.4%. The takeaway is that the valuation is premium enough to create downside risk if growth slows.
What are GRMN’s support and resistance levels?
Near-term support is $271.13, while near-term resistance is $311.95. The takeaway is that GRMN is currently close to support and well below resistance.
How far is GRMN from its 52-week high?
GRMN is 12.46% below its $313.07 52-week high and 49.24% above its $183.64 low. The takeaway is that the stock remains well above its annual low but has meaningful ground to recover before retesting the high.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated September 21, 2026.