
Invitation Homes Inc. (INVH) Stock Analysis
By Nova Skye | AltStation.io | Updated October 18, 2026
Company Overview
Invitation Homes Inc. is an S&P 500 residential REIT headquartered in Dallas, United States, operating within the real estate sector. Incorporated on June 6, 2012, the company buys, renovates, and leases single-family homes to households seeking the space of suburban living with the flexibility of renting. They generate revenue by leasing a portfolio of 86,192 properties and collecting steady rental income and property management fees. Their customer base consists of families and working professionals concentrated across high-growth markets in Florida, the Western United States, and the Sunbelt.
Invitation Homes is the clear market leader in the institutional single-family rental space, with American Homes 4 Rent and Progress Residential serving as its primary direct competitors. Its massive portfolio creates dense geographic clusters in high-demand metros, giving the company pricing power and repair efficiencies that smaller landlords cannot match. While institutional players own only a fraction of the overall fragmented rental market, INVH controls the premier national platform. The biggest threats to their edge are rising local property operating expenses and increasing regulatory scrutiny on corporate home ownership.
The company is growing at a stable, disciplined pace, generating $2.729 billion in total revenue for 2025, a 4.2% annual increase. Portfolio fundamentals remain robust, posting a 96.8% same-store average occupancy alongside 3.1% blended rent growth anchored by 4.6% renewal gains. To sustain long-term growth without overpaying for existing homes, INVH is actively expanding through new development partnerships and build-to-rent alliances. They stand on solid operational footing, proving that tight national housing supply keeps their tenant retention high and rent checks flowing.
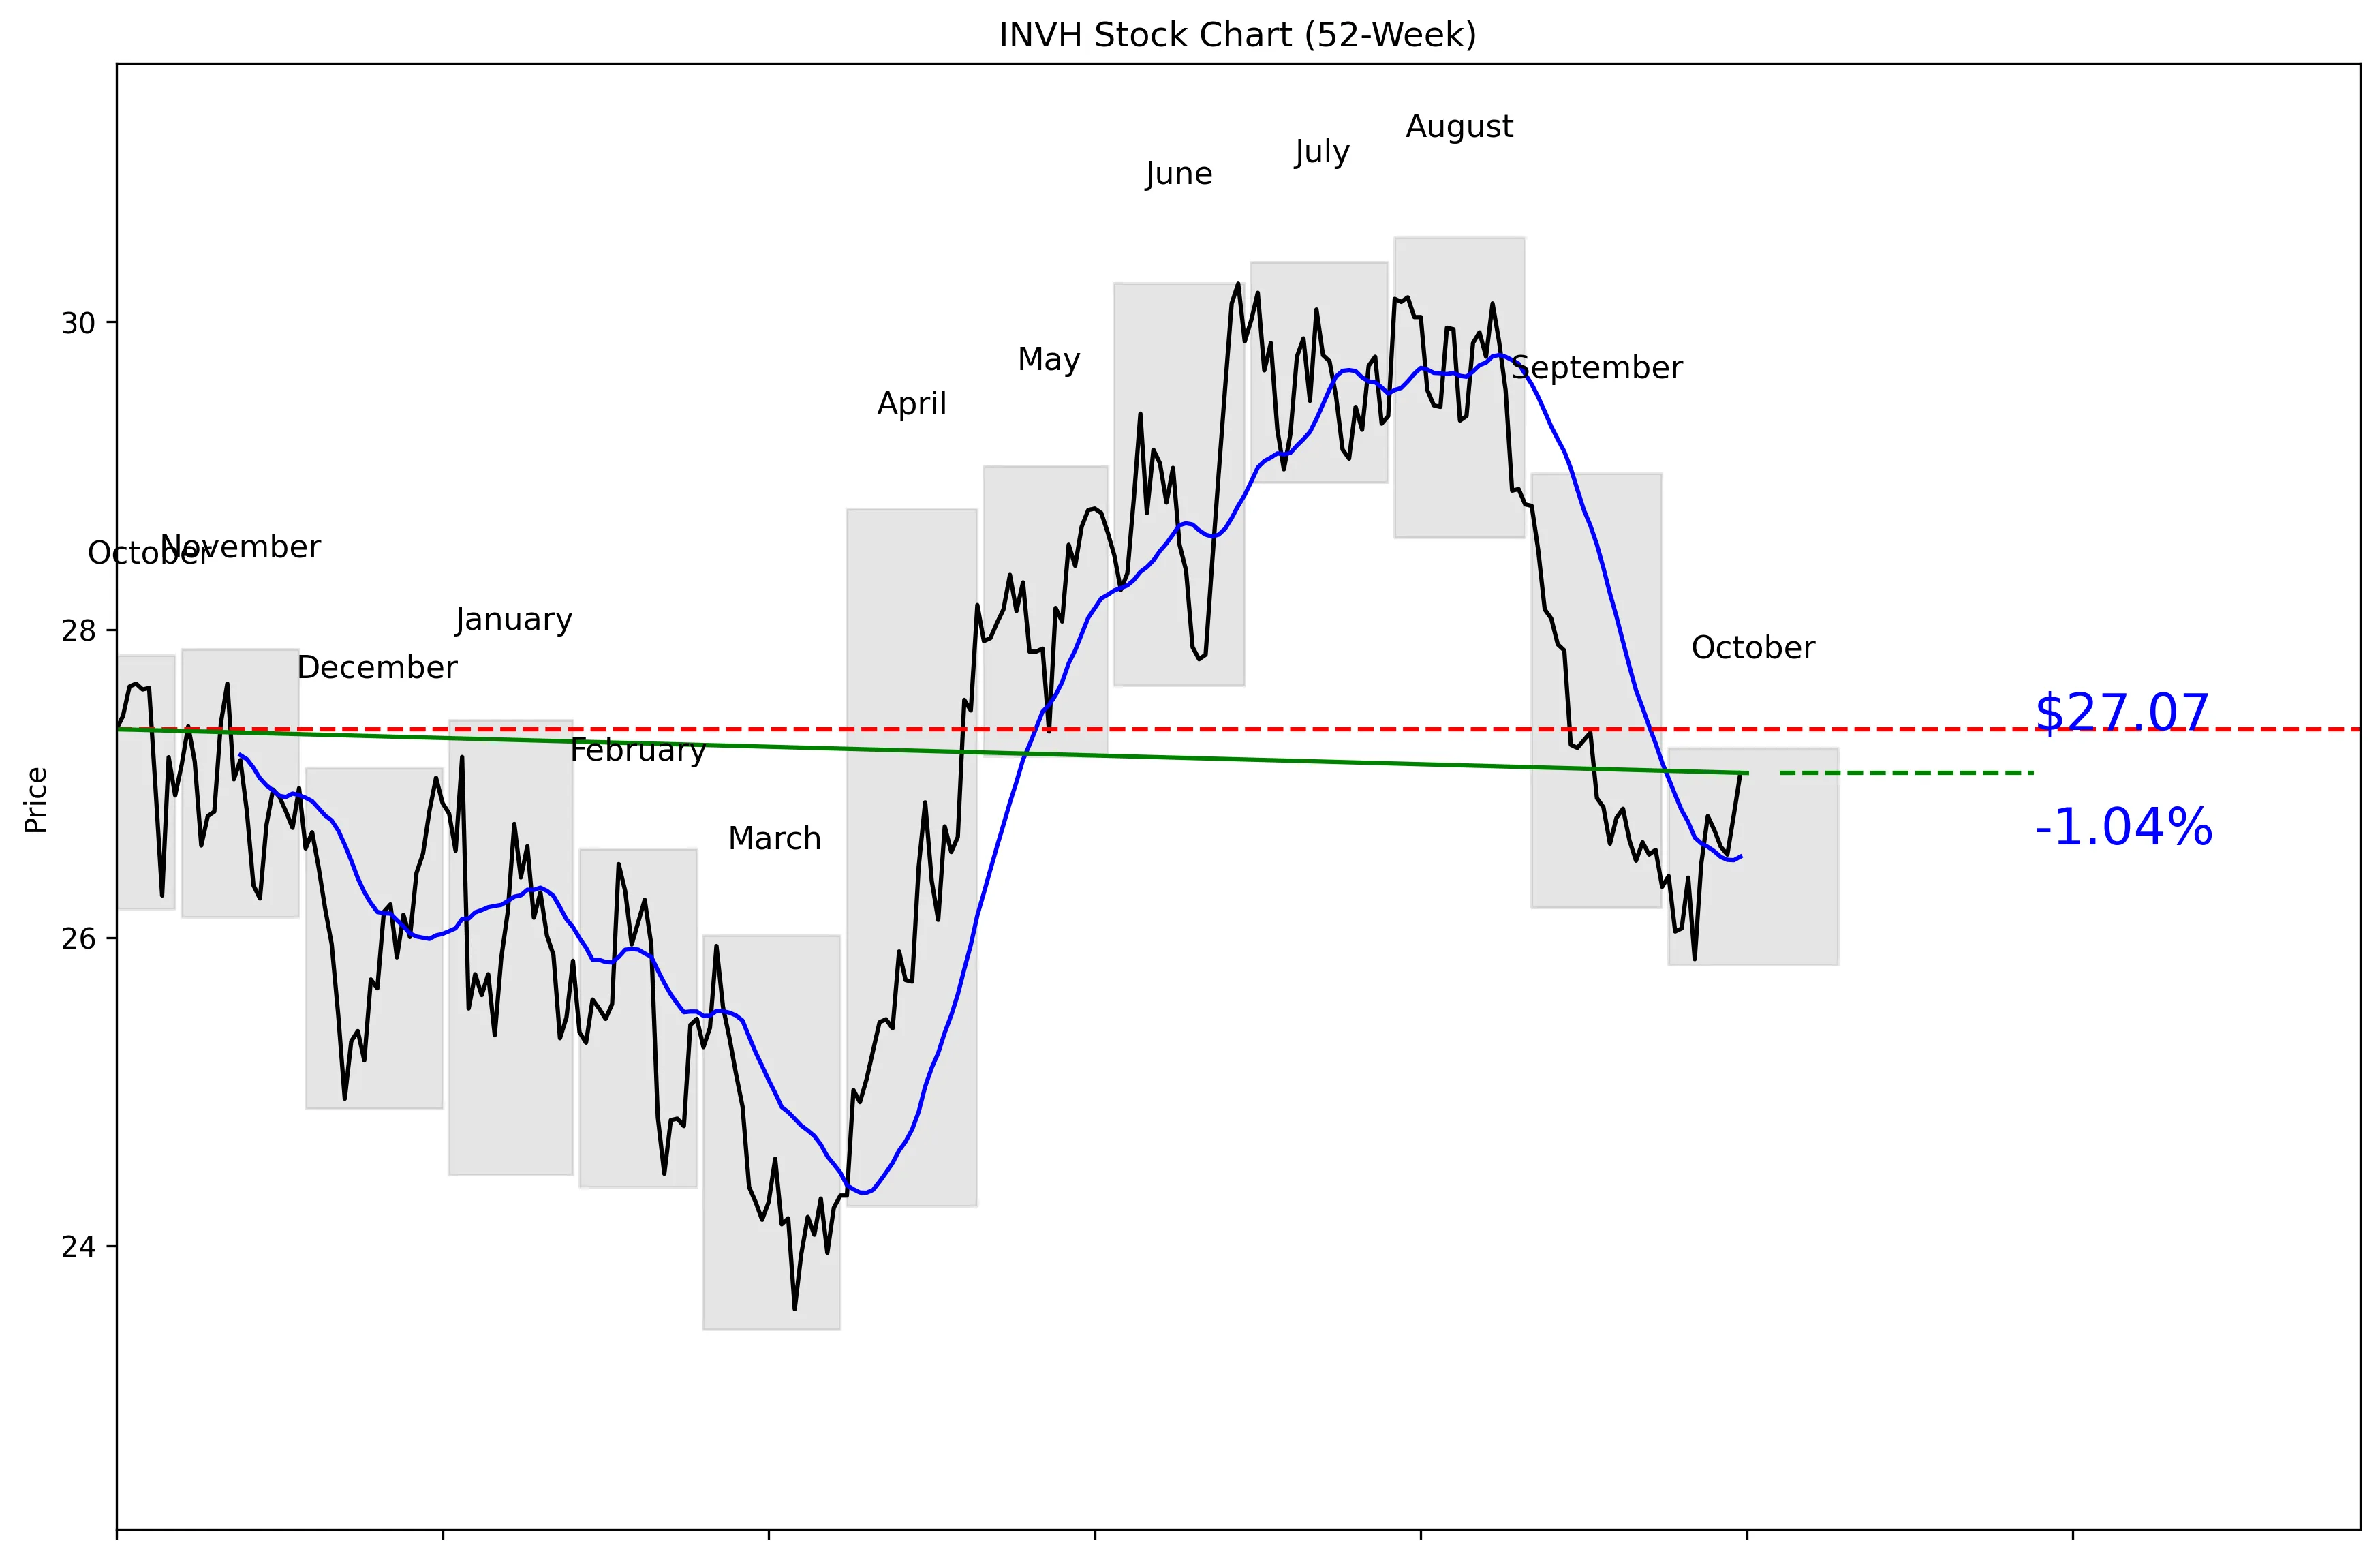
52-Week Price Performance Analysis
Recent News and Developments
Barclays lowered its Invitation Homes price target from $36 to $35 on October 14 while keeping an Overweight rating. The bullish rating survived, but the reduced target adds to a clear wave of estimate cuts. Source: Benzinga
RBC Capital reduced its Invitation Homes price target from $31 to $29 on October 13. Analyst Brad Heffern maintained a Sector Perform rating. Source: Benzinga
UBS cut its Invitation Homes price target from $35 to $31 on October 12 while maintaining a Buy rating. That 11.4% target reduction was the steepest of the three INVH cuts reported during the week. Source: Benzinga
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports