ALTSTATION.IO

The Kroger Co. (KR) Stock Analysis

By Nova Skye | AltStation.io | Updated October 14, 2026

Price
$61.16
Change
-2.24%
Market Cap
$36.12B
Avg Volume
6.9M

Company Overview

The Kroger Co. is a Cincinnati-based grocery retailer operating in the Consumer Defensive sector across the United States. Founded in 1883, the business serves everyday retail consumers through four primary store formats: combination food and drug stores, multi-department locations, marketplace stores, and price impact warehouses. Customers buy essential food, fresh organic produce, seafood, pharmaceuticals, and household goods, along with fuel from Kroger’s dedicated fuel centers. They also sell non-grocery lines like apparel, home furnishings, electronics, and automotive goods, distributing items through physical storefronts and their direct online platforms.

Kroger holds a leading position in the traditional US grocery space by operating across multiple retail tiers rather than relying on a single store model. Their biggest operational edge is vertical integration; they manufacture and process their own food products rather than purely acting as a reseller for third-party brands. This multi-format setup lets them capture budget shoppers through price impact warehouses while competing with department stores via large marketplace locations. However, operating across grocery, pharmacy, general merchandise, and fuel exposes them to heavy competition from discount warehouses, standalone pharmacies, and broad-line retail chains.

Right now, Kroger is prioritizing an omnichannel strategy that connects its physical footprint with in-house food processing and online sales platforms. Distributing across both physical aisles and digital channels gives them diversified revenue streams, but defending margins in grocery retail requires steady volume. Their primary operational test is managing complex inventory across apparel, automotive, and fresh perishables against simpler, grocery-only competitors. Kroger’s dual identity as a retailer and food manufacturer provides defensibility, but managing four distinct store formats demands tight execution.

Key Financials
Market Cap
$36.12B
Revenue
$149.33B
EBITDA
$8.04B
Gross Margin
23.9%
Profit Margin
0.7%
Revenue Growth
2.0%
Total Cash
$1.68B
Total Debt
$24.16B
Free Cash Flow
$2.54B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
33.98
Forward P/E
11.11
Beta
0.35
52-Week High
$76.58
52-Week Low
$54.15
EPS
$1.80
50-Day Avg
$58.42
200-Day Avg
$63.44
Price/Book
6.24
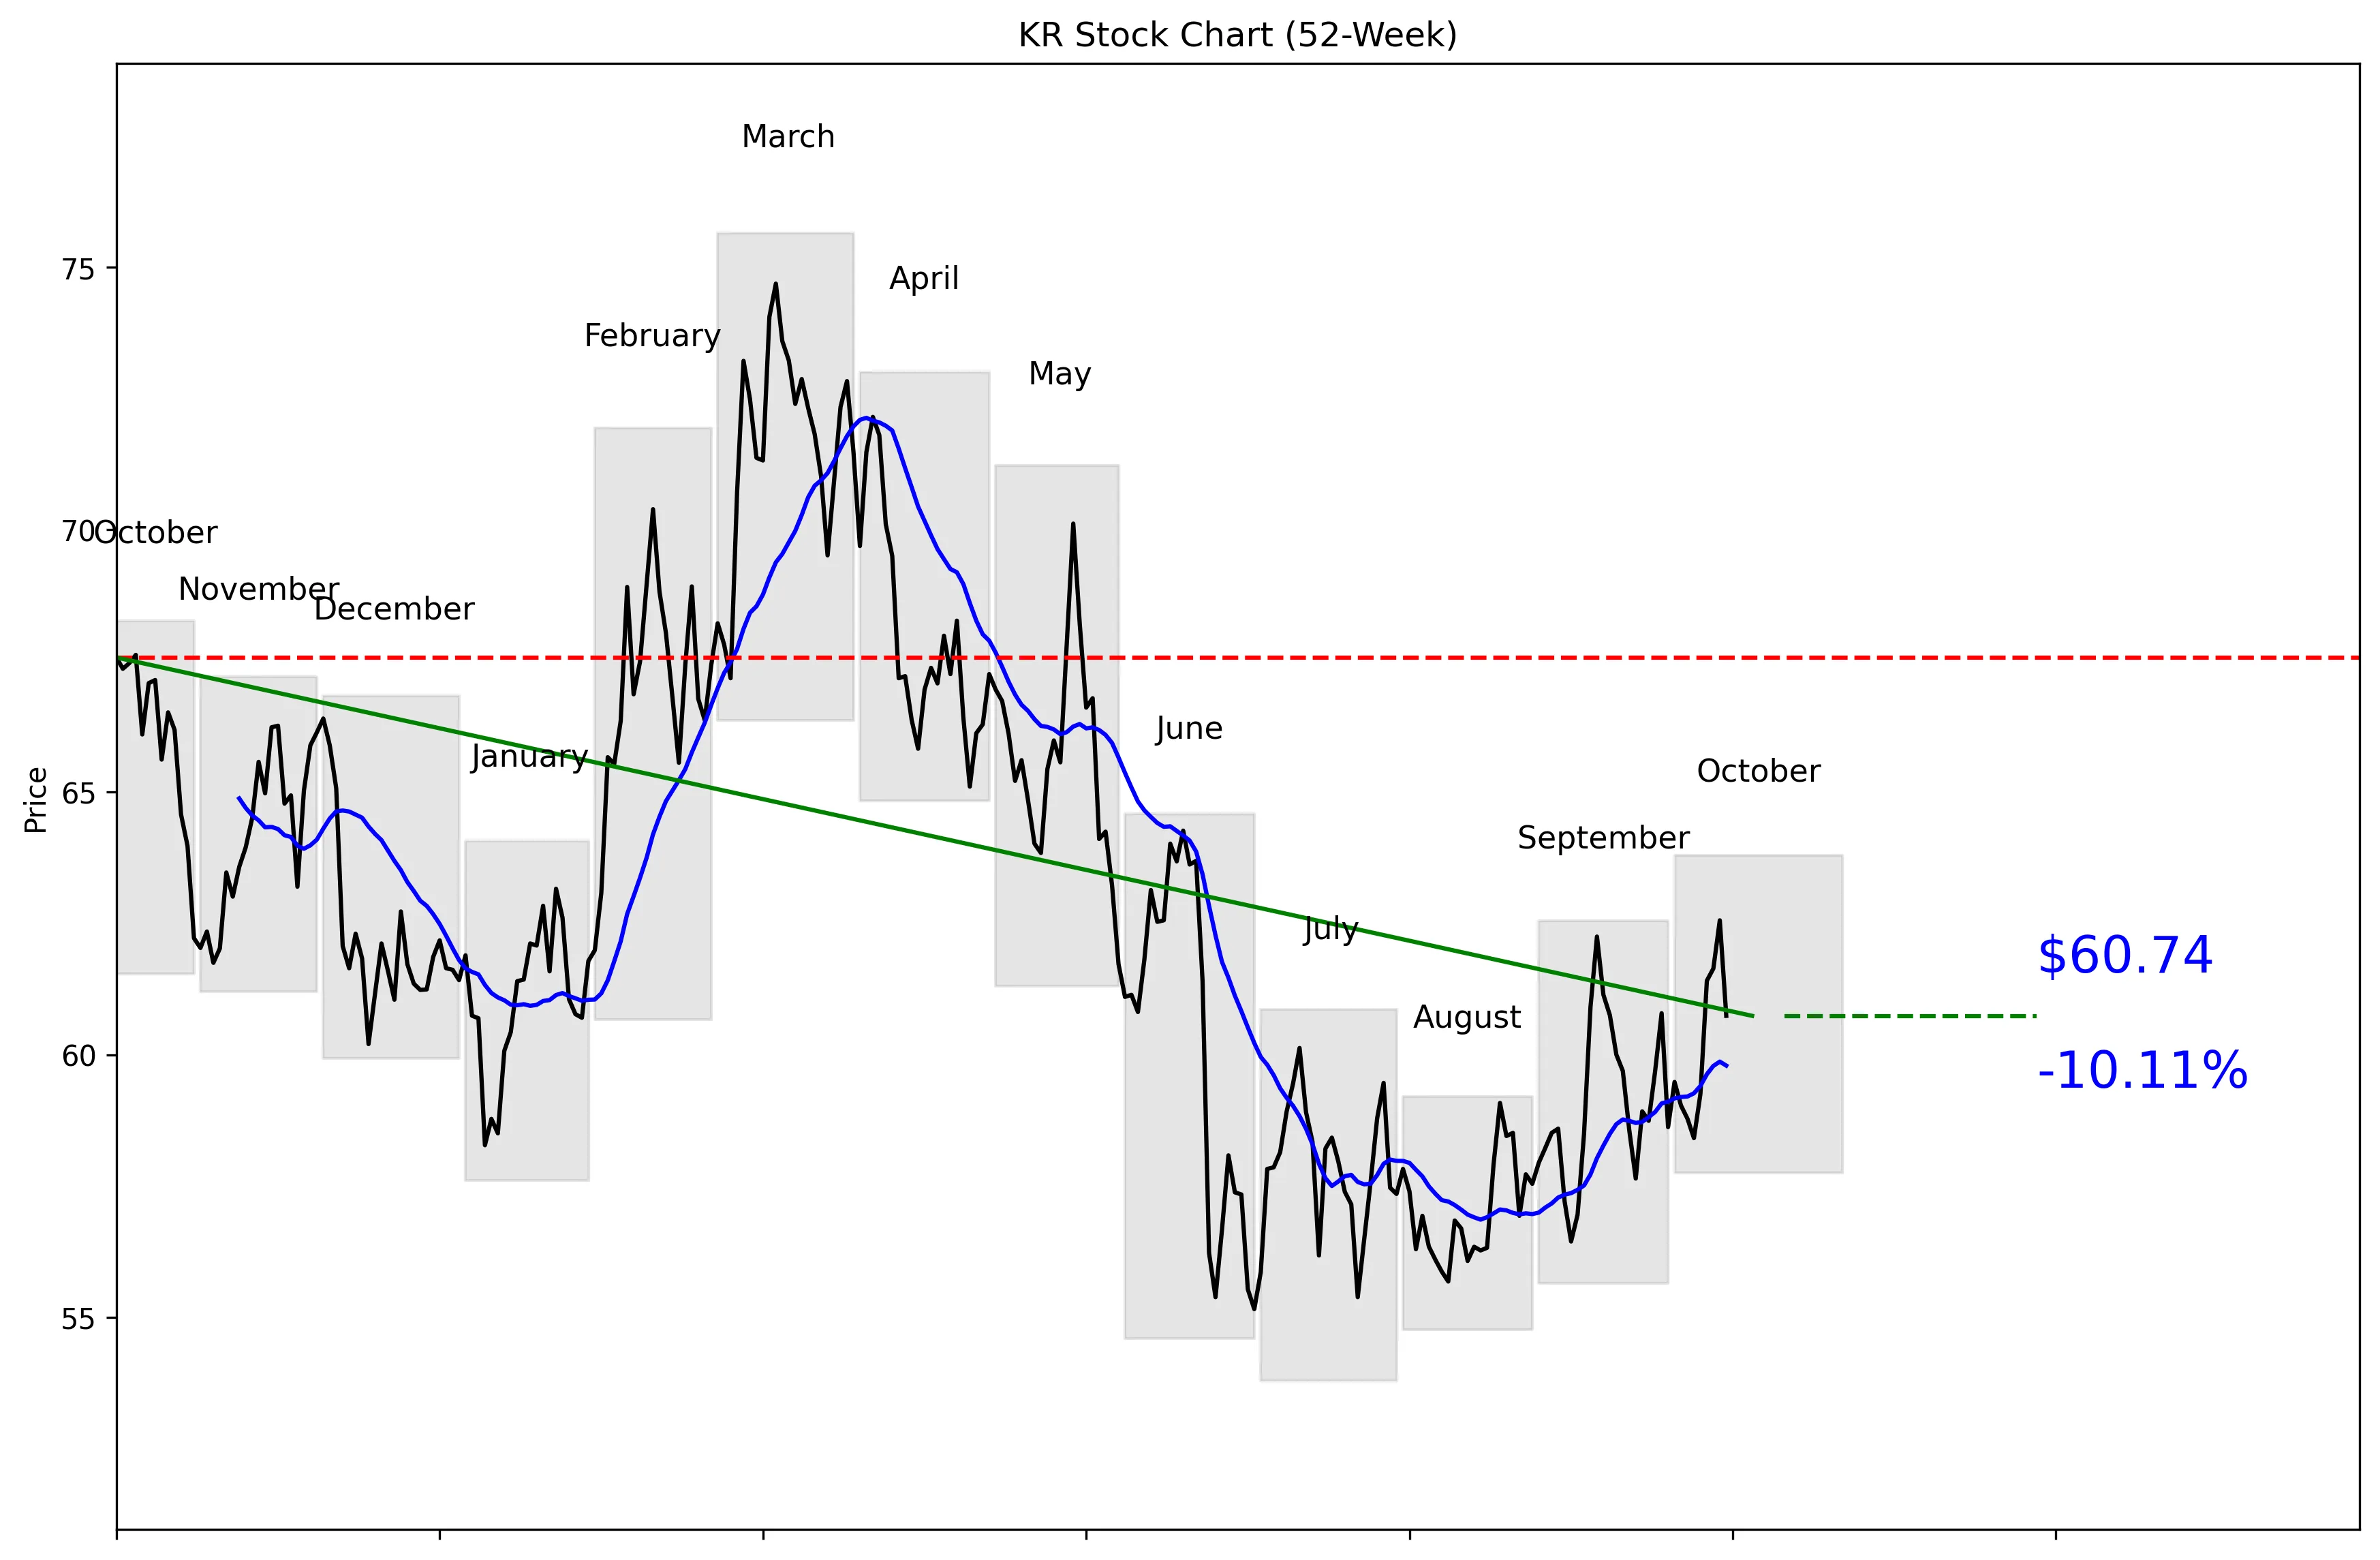
KR 52-Week Stock Chart
Technical Analysis
KR trades at $61.16, 32% of the way from its $53.78 52-week low to its $75.66 high. The stock is 19.72% below that high and 12.94% above the low. Price is above the $59.79 20-day moving average, with the supplied data showing a 1.59% gap. Momentum improved 3.99% over the last five trading days, but remains negative 2.43% over 20 days. Near-term support is $56.44, while $62.56 is the resistance level KR needs to clear.


Recent News and Developments

Kroger plans 3,000 corporate job cuts

Kroger will eliminate 3,000 corporate positions over three years while expanding its use of artificial intelligence. KR fell 2.2% to $61.21 in Tuesday afternoon trading following the announcement. Source: AP News

Albertsons seeks more than $9 billion from Kroger

Albertsons demanded more than $9 billion over the failed $24.6 billion merger in Delaware Chancery Court. A two-week trial over responsibility for the collapsed deal is scheduled for later this month. Source: Bloomberg Law

UBS holds Kroger at Neutral after layoff plan

UBS reiterated its Neutral rating and $63 price target after Kroger disclosed the 3,000-position reduction. The target offered little upside from the reported $61.83 share price. Source: Investing.com


Market Sentiment and Analyst Recommendations

Bull Case
KR has $149.33 billion in revenue against a $36.12 billion market cap, giving investors exposure to a large operating business at its current equity value. Revenue is still growing, although the reported rate is only 2.0%. The analyst consensus is buy across 22 analysts, with a $68.32 target versus the current $61.16 price. The bullish end of the target range reaches $85.00, and BNP Paribas Exane upgraded KR from Neutral to Outperform with a $72 target on October 7. The planned elimination of 3,000 corporate positions and expanded use of artificial intelligence could improve efficiency if management executes without hurting operations. Kroger also has more than 2,200 pharmacies across 35 states and nearly 200 The Little Clinic locations, extending its reach beyond groceries. At 32% of its technical 52-week range, KR offers a credible rebound setup if it breaks through $62.56.
Bear Case
The 33.98 P/E is difficult to defend against revenue growth of just 2.0%. Kroger carries $24.16 billion in total debt and only $1.68 billion in total cash, leaving a large balance-sheet gap. Albertsons is seeking more than $9 billion from Kroger over the failed $24.6 billion merger, creating a serious legal and financial risk. A two-week trial is scheduled for later this month, so that overhang is immediate. The market did not welcome the restructuring announcement: KR fell 2.2% to $61.21 after the 3,000 planned corporate job cuts were disclosed. UBS kept its Neutral rating and $63 target, which signals limited upside from the reported $61.83 price. KR also remains 19.72% below its 52-week high, while 20-day momentum is still negative at 2.43%.
What to Watch
The Albertsons trial scheduled for later this month is the biggest near-term event because the claim exceeds $9 billion. Investors should watch whether Kroger’s plan to eliminate 3,000 corporate positions over three years produces better efficiency without weakening execution. Management’s expanded use of artificial intelligence also needs to show measurable operating value. On the chart, $62.56 is the immediate resistance level; a sustained move above it would strengthen the rebound case. The $59.79 20-day moving average is the first momentum checkpoint, while $56.44 is the near-term support level that bulls need to defend. Revenue growth must improve from 2.0% to make the 33.98 P/E easier to justify. Analyst revisions around the $68.32 consensus target, including the competing $63 UBS and $72 BNP targets, will show whether Wall Street is gaining or losing confidence.
Analyst Consensus
BUY

Based on 22 analyst opinions
Low Target
$57.00
Mean Target
$68.32
High Target
$85.00


Earnings and Financial Data

Sector
Consumer Defensive
Industry
Grocery Stores
Employees
400,000
Earnings & Dividends
Next Earnings
Dec 03, 2026
EPS (Trailing)
$1.80
Dividend Yield
249.0%
Payout Ratio
77.8%

Frequently Asked Questions

Is KR a good stock to buy?
The recommendation is buy based on 22 analysts, and the consensus target is $68.32 versus a $61.16 share price. The 33.98 P/E, 2.0% revenue growth, and $24.16 billion debt keep the setup from being low-risk. Takeaway: KR has analyst support, but the valuation and debt require caution.
What is KR’s price target?
The analyst target is $68.32, with estimates ranging from $57.00 to $85.00. The current stock price is $61.16. Takeaway: Wall Street’s central target is above the current price, but the range shows substantial disagreement.
Is KR stock overvalued?
KR trades at a P/E of 33.98 while reported revenue growth is 2.0%. Those figures make the valuation look demanding unless growth or profitability improves. Takeaway: KR is not obviously cheap on its stated earnings multiple.
What are KR’s support and resistance levels?
Near-term support is the 30-day low of $56.44, and near-term resistance is the 30-day high of $62.56. KR currently trades at $61.16. Takeaway: the stock is close to resistance and still comfortably above support.
How much cash and debt does Kroger have?
Kroger has $1.68 billion in total cash and $24.16 billion in total debt. Its market capitalization is $36.12 billion. Takeaway: debt is a major balance-sheet consideration for KR investors.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 14, 2026.