ALTSTATION.IO

Paychex, Inc. (PAYX) Stock Analysis

By Nova Skye | AltStation.io | Updated September 08, 2026

Price
$116.90
Change
-3.95%
Market Cap
$41.61B
Avg Volume
3.1M

Company Overview

Paychex, Inc. is an application software company in the technology sector that handles payroll, human resources, employee benefits, and tax compliance. Headquartered in Rochester, New York and founded in 1971, the company sells directly to small and medium-sized businesses across the United States, Europe, Canada, India, and Israel. Their product suite covers the entire employee lifecycle, including talent acquisition, digital earned-wage access, 401(k) retirement administration, and property and casualty insurance. They eliminate operational friction for approximately 800,000 business clients who lack dedicated internal HR and compliance departments.

Paychex is an established market leader in the small-to-medium business payroll segment, competing directly with legacy heavyweight Automatic Data Processing (ADP). Its main competitive advantage comes from steep switching costs and entrenched tax remittance workflows that make migrating to another vendor risky for busy business owners. Modern cloud-first platforms like Gusto and Rippling continue to pressure the lower end of the market, while mid-market players like Paycom and Paylocity fight for larger accounts. Paychex defends its ground by utilizing its direct sales force to cross-sell comprehensive HR outsourcing and insurance bundles that pure-play software vendors struggle to match.

The company generated $6.51 billion in annual revenue for fiscal 2026, demonstrating stable growth and resilient recurring cash flows. Instead of attempting radical pivots, Paychex is steadily increasing average revenue per user by driving its client base toward higher-margin professional employer and advisory services. While macroeconomic slowdowns in small-business hiring create near-term friction, the company’s defensive subscription model and essential compliance functions protect its core cash engine. It is a disciplined cash generator built on client retention rather than speculative hyper-growth.

Key Financials
Market Cap
$41.61B
Revenue
$3.97B
EBITDA
$1.61B
Gross Margin
67.2%
Profit Margin
26.6%
Revenue Growth
12.5%
Total Cash
$1.14B
Total Debt
$4.63B
Free Cash Flow
N/A


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
23.91
Forward P/E
18.29
Beta
N/A
52-Week High
$135.97
52-Week Low
$85.45
EPS
$4.89
50-Day Avg
$116.37
200-Day Avg
$104.03
Price/Book
11.13
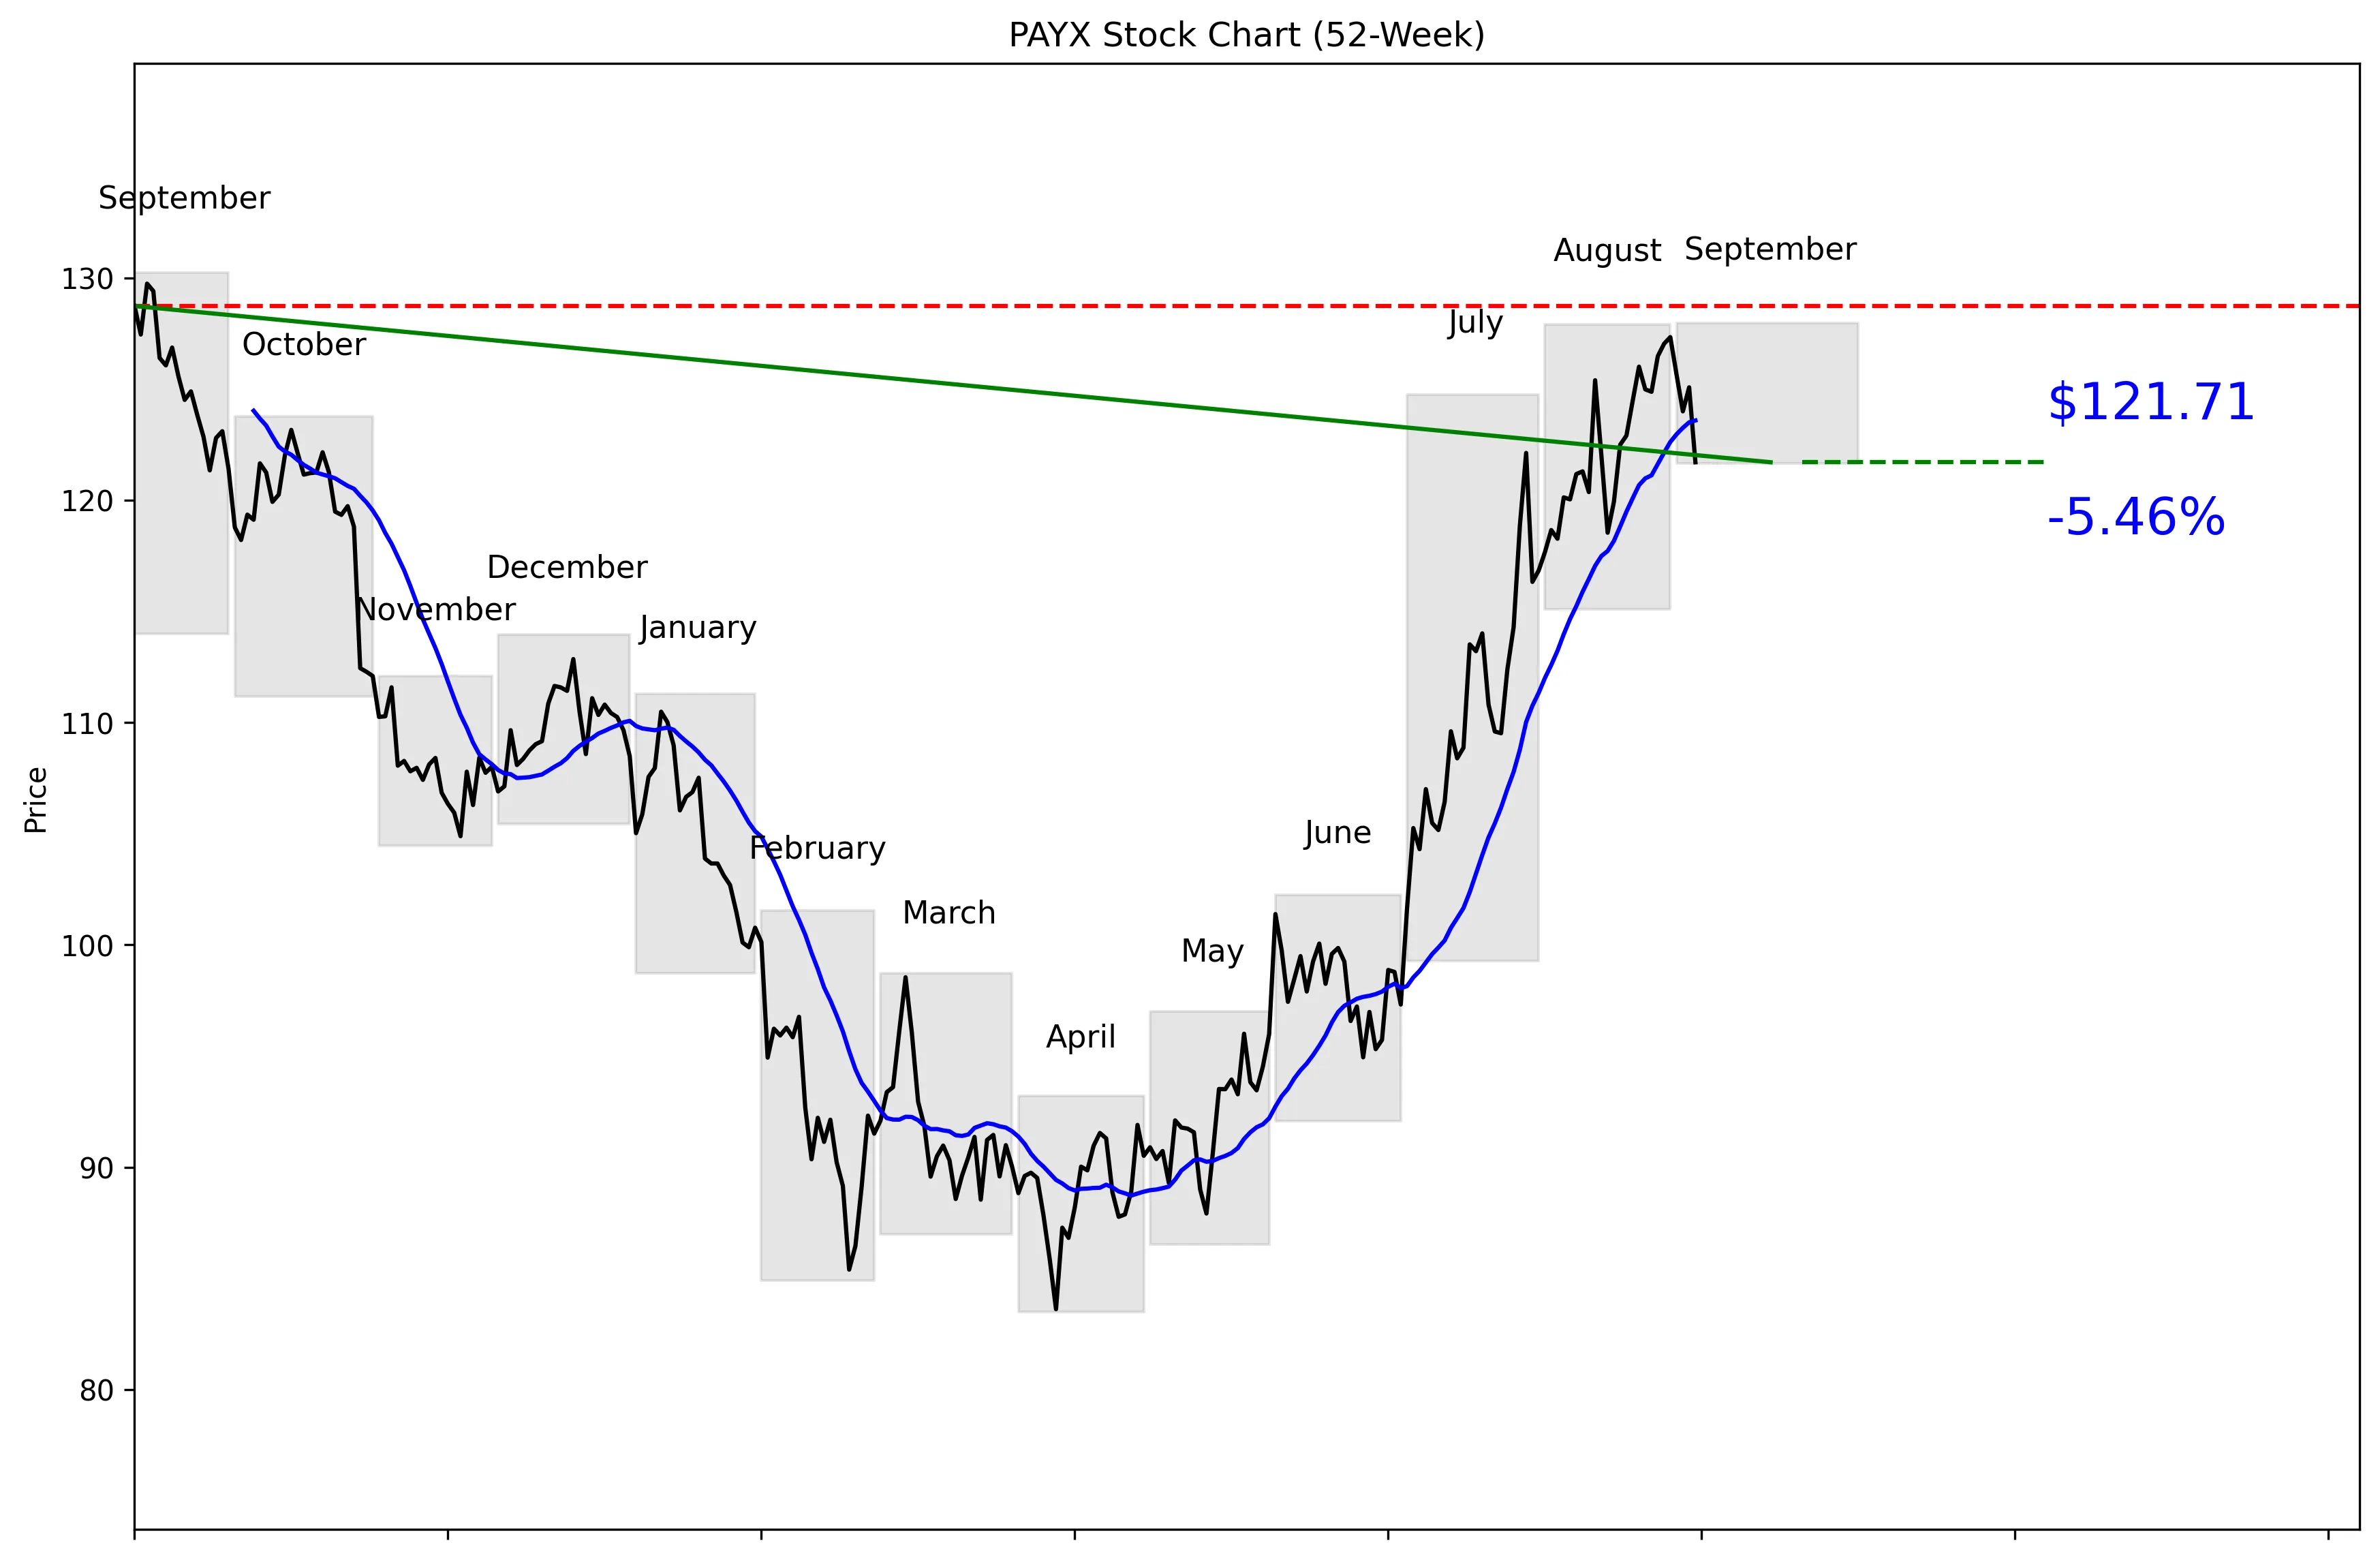
PAYX 52-Week Stock Chart
Technical Analysis
PAYX trades at $116.90, placing it 82% of the way from its technical 52-week low of $83.50 to its high of $130.23. The stock is 6.55% below that high and 45.77% above the low. Price is listed as 1.52% below the 20-day moving average of $123.59. Five-day momentum is negative 4.20%, while 20-day momentum remains positive at 1.39%. Near-term support is $114.29, with resistance at $127.34.


Recent News and Developments

Stephens resumes Paychex at Equal Weight with $132 target

Stephens analyst Brett Huff resumed coverage of PAYX with an Equal Weight rating and a $132 price target. He said stronger revenue growth is needed to push the stock higher and Paychex’s premium valuation leaves little room for error. Source: TipRanks

PAYX gains 30.1% in six months

Paychex shares gained 30.1% over six months, beating the industry’s 8.1% return and the S&P 500’s 12.7% rise. Paycor delivered more than $100 million in cost synergies and contributed 50 basis points to revenue growth, giving the rally real operating support. Source: Zacks Investment Research

Paychex data shows small-business employment holding steady

The Paychex Small Business Jobs Index registered 99.13 in August, while weekly hours worked grew 0.07% for a sixth consecutive month. Hourly earnings growth remained below 3% for the 24th straight month, landing at 2.89%. Source: Paychex


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is growing 12.5% on a $3.97 billion base, giving PAYX a credible fundamental growth story. Paycor contributed 50 basis points to revenue growth and delivered more than $100 million in cost synergies. The stock gained 30.1% over six months, beating both the industry’s 8.1% return and the S&P 500’s 12.7% rise. Paychex also holds $1.14 billion in cash. Stephens set a $132 target, while the broader analyst range reaches $150. Small-business employment remained steady in August, with the Paychex Small Business Jobs Index at 99.13 and weekly hours rising 0.07% for a sixth consecutive month. The reason to buy is straightforward: double-digit revenue growth and demonstrated acquisition synergies could support another move toward $127.34 and beyond.
Bear Case
PAYX trades at 23.91 times earnings, and Stephens explicitly says the premium valuation leaves little room for error. The consensus analyst target is $114.93, below the current $116.90 price. Fifteen analysts rate the stock a hold, which is not a strong endorsement at this valuation. Total debt of $4.63 billion is more than four times the company’s $1.14 billion cash balance. Five-day momentum is negative 4.20%, and the stock is below its $123.59 moving average. A break below $114.29 support would weaken the near-term setup, while $127.34 resistance could limit a rebound. Stephens says stronger revenue growth is needed, so the current 12.5% rate must hold up if the premium multiple is going to work.
What to Watch
The October 15 annual meeting is the next dated corporate event, with votes covering 10 directors, executive compensation and the appointment of PricewaterhouseCoopers. Revenue growth is the central operating metric; the current benchmark is 12.5%. Investors should track whether Paycor continues contributing beyond its reported 50 basis points of revenue growth and more than $100 million in cost synergies. On the chart, $114.29 is the immediate downside threshold and $127.34 is the upside barrier. A recovery above the $123.59 moving average would improve the momentum picture after the negative 4.20% five-day move. The thesis strengthens if growth remains firm and PAYX clears $127.34; it weakens if growth slows while the stock breaks $114.29.
Analyst Consensus
HOLD

Based on 15 analyst opinions
Low Target
$95.00
Mean Target
$114.93
High Target
$150.00


Earnings and Financial Data

Sector
Technology
Industry
Software – Application
Employees
17,600
Earnings & Dividends
Next Earnings
Sep 29, 2026
EPS (Trailing)
$4.89
Dividend Yield
391.0%
Payout Ratio
90.6%

Frequently Asked Questions

Is PAYX a good stock to buy?
PAYX has 12.5% revenue growth, but 15 analysts currently rate it a hold. The takeaway is that the business is growing, but the available data does not show a clear consensus buy signal.
What is PAYX’s analyst price target?
The analyst target is $114.93, with estimates ranging from $95.00 to $150.00. The takeaway is that the target range is wide and the consensus target sits below the current $116.90 price.
What is PAYX’s 52-week range?
The technical price series shows a 52-week range of $83.50 to $130.23, with PAYX positioned 82% of the way from the low to the high. The takeaway is that the stock remains near the upper end of its annual range.
What are PAYX’s support and resistance levels?
Near-term support is $114.29, based on the 30-day low, while resistance is $127.34, based on the 30-day high. The takeaway is that these are the key technical levels to monitor.
Is PAYX overvalued?
PAYX trades at a P/E ratio of 23.91, while its $114.93 analyst target is below the current $116.90 price. The takeaway is that the supplied valuation and target data point to limited consensus upside.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated September 08, 2026.