Arm Holdings plc (ARM) Stock Analysis
By Nova Skye | AltStation.io | Updated September 13, 2026
Company Overview
Headquartered in Cambridge, United Kingdom, Arm Holdings plc operates in the semiconductor industry within the technology sector, designing foundational chip architecture since its founding in 1990. Arm does not manufacture physical chips; instead, it licenses central processing unit (CPU) and graphics processing unit (GPU) intellectual property, system interconnects, pre-integrated compute subsystems (CSS), and software development tools. Its customer base spans semiconductor companies, original equipment manufacturers, and cloud service providers across the United States, China, Japan, Taiwan, and Korea. These buyers deploy Arm designs across eight major end markets: smartphones, consumer electronics, industrial IoT, embedded systems, cloud data centers, networking, automotive, and robotics.
Arm functions as an entrenched market leader in mobile and edge compute architecture, backed by parent company SoftBank Group Corp. Its structural edge lies in an asset-light licensing model that supplies CPU, GPU, and neural processing unit (NPU) accelerators without the capital burden of operating silicon fabrication facilities. The main strategic vulnerability lies in its reliance on global hardware manufacturing cycles and heavy exposure to key Asian markets like China, Taiwan, and Korea. Because Arm monetizes through IP licensing and developer tools, maintaining architectural lock-in against alternative processing designs remains critical to sustaining long-term royalty streams.
Arm is currently executing a strategic push beyond standalone core IP by rolling out pre-integrated compute subsystems and dedicated NPU accelerators. This shift expands the business past its legacy consumer electronics base directly into higher-complexity targets, specifically cloud data centers, automotive systems, and robotics. Delivering pre-configured subsystems shortens development timelines for cloud providers and OEMs designing custom silicon in-house. Moving up the stack into integrated compute platforms positions Arm to capture greater contract value across next-generation enterprise and automotive hardware.
52-Week Price Performance Analysis
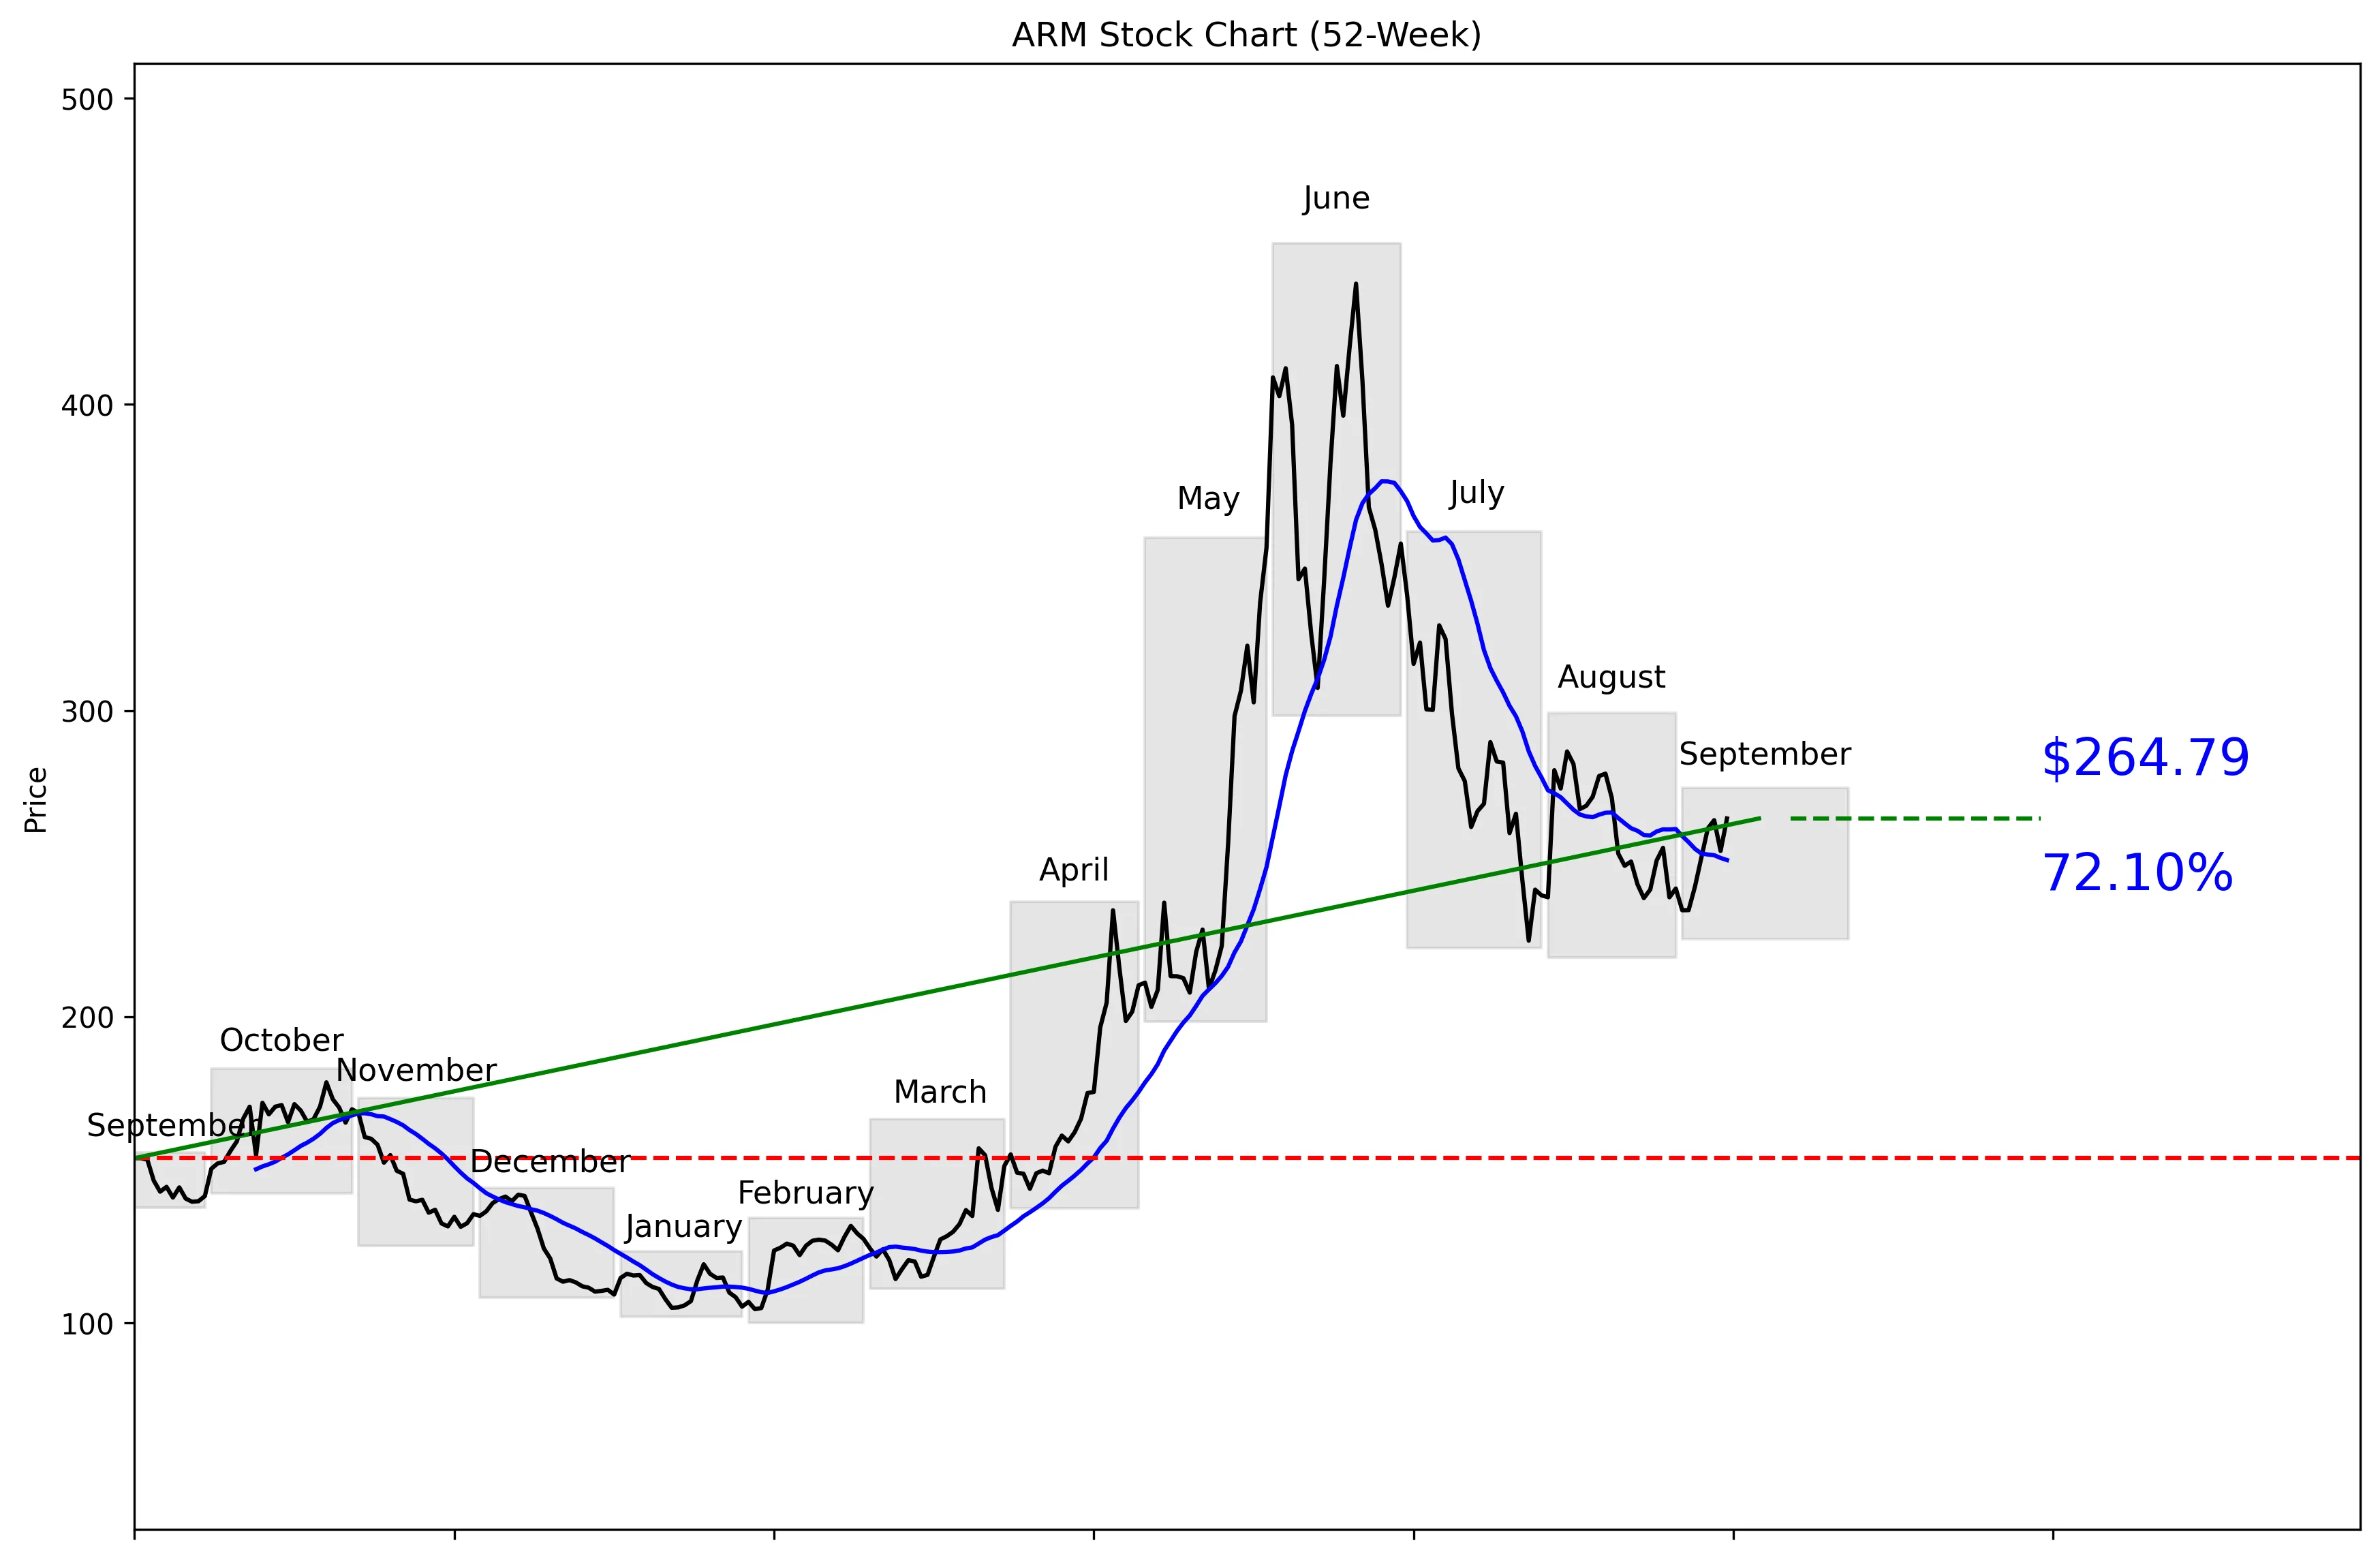
The stock remains 41.51% below the 52-week high but sits 164.74% above the low.
Price is 5.41% above the 20-day moving average of $251.21.
Momentum improved 9.15% over the last five trading days, although the 20-day reading remains negative at 4.97%.
Near-term support is $234.82, while $286.68 is the resistance level buyers need to clear.
Recent News and Developments
Arm launched CSS for Mobile 2 on September 8 with its new C2 CPU cluster and Mali G2-Ultra NX GPU. The platform adds dedicated neural accelerators and targets on-device agentic AI and higher-end mobile graphics. Source: Arm Newsroom
Arm introduced Neoverse CSS N4 with up to 128 cores per die, LPDDR6 support and PCIe Gen 7 connectivity. Arm claims up to 2x the performance, 1.25x the performance per watt and 1.75x the memory bandwidth of Neoverse CSS N3. Source: Arm Newsroom
Piper Sandler analyst David O’Connor initiated coverage of ARM with an Overweight rating on September 9. This was new coverage, not an upgrade, and the rating record did not list a price target. Source: StreetInsider
Market Sentiment and Analyst Recommendations
The company generated $5.16 billion in revenue and holds $3.89 billion in cash against $485 million in debt.
Arm’s CSS for Mobile 2 adds dedicated neural accelerators through its C2 CPU cluster and Mali G2-Ultra NX GPU, positioning the company for on-device agentic AI.
Neoverse CSS N4 extends that opportunity into AI data centers with up to 128 cores per die, LPDDR6 support and PCIe Gen 7 connectivity.
Arm claims N4 delivers up to 2x the performance, 1.25x the performance per watt and 1.75x the memory bandwidth of N3.
The analyst consensus is buy across 40 analysts, and the $289.20 target sits above the current $266.83 price.
The bull case is straightforward: strong revenue growth, exposure to mobile and data-center AI, and a balance sheet with substantially more cash than debt.
A valuation that high leaves little room for slower growth or weak execution, even with revenue currently rising 22.4%.
The analyst target range runs from $125.00 to $500.00, showing extreme disagreement about what ARM is worth.
The current price is already 164.74% above the 52-week low, so buyers are not entering after a minor recovery.
ARM also remains 41.51% below its $452.70 high, proof that premium expectations can unwind sharply.
The 20-day momentum reading is still negative at 4.97%, despite the stronger five-day move.
ARM has a compelling AI story, but at 269.53 times earnings, the stock is priced for exceptional results rather than merely good ones.
Investors should track adoption of CSS for Mobile 2, launched September 8, particularly its dedicated neural accelerators and higher-end graphics capabilities.
Neoverse CSS N4 is the other major catalyst, with its claimed 2x performance and 1.25x performance-per-watt gains setting a high execution bar.
Piper Sandler initiated coverage at Overweight on September 9 without a listed price target, so any future target would add useful context to that rating.
Technically, a sustained move above $286.68 would break the current 30-day resistance, while a drop below the $251.21 moving average would weaken the recent rebound.
The thesis takes a harder hit if ARM breaks $234.82 support or revenue growth falls materially below 22.4%.
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports