ALTSTATION.IO

Micron Technology, Inc. (MU) Stock Analysis

By Nova Skye | AltStation.io | Updated October 06, 2026

Price
$1063.38
Change
-0.05%
Market Cap
$1.20T
Avg Volume
33.5M

Company Overview

Micron Technology, headquartered in Boise, Idaho, is a major semiconductor manufacturer that builds the memory and storage hardware powering modern computing. Founded in 1978, the company produces dynamic random-access memory (DRAM) for active system processing and NAND flash storage for long-term retention under the Micron and Crucial brand names. They sell components directly and through global distributors to data center operators, smartphone manufacturers, PC makers, and automotive suppliers. Their business is organized across four core segments: Cloud Memory, Core Data Center, Mobile and Client, and Automotive and Embedded.

Micron stands as a tier-one market leader, holding a rare position as one of the few global players capable of producing both cutting-edge DRAM and NAND flash at massive scale. Their operational edge comes from proprietary technology platforms like high-bandwidth memory, CXL-based architectures, and G9 NAND built for data-heavy workloads. The primary risk remains the structural cyclicality of the semiconductor memory market, where shifts in global supply and aggressive competition across regions like Taiwan, Japan, and Mainland China can rapidly squeeze pricing.

Right now, Micron is aggressively steering its business toward data-centric hardware, prioritizing high-bandwidth memory and data center SSDs to serve enterprise and cloud infrastructure. This strategic emphasis on the Cloud Memory and Core Data Center business units helps diversify the company away from mature, lower-margin client PC and smartphone lines. If Micron continues to scale its high-bandwidth memory portfolio smoothly, it solidifies its place as an indispensable supplier for next-generation computing infrastructure.

Key Financials
Market Cap
$1.20T
Revenue
$133.19B
EBITDA
$108.84B
Gross Margin
80.7%
Profit Margin
63.8%
Revenue Growth
379.3%
Total Cash
$43.43B
Total Debt
$5.18B
Free Cash Flow
$29.21B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
14.31
Forward P/E
5.15
Beta
2.23
52-Week High
$1255.00
52-Week Low
$179.61
EPS
$74.33
50-Day Avg
$958.91
200-Day Avg
$685.77
Price/Book
11.92
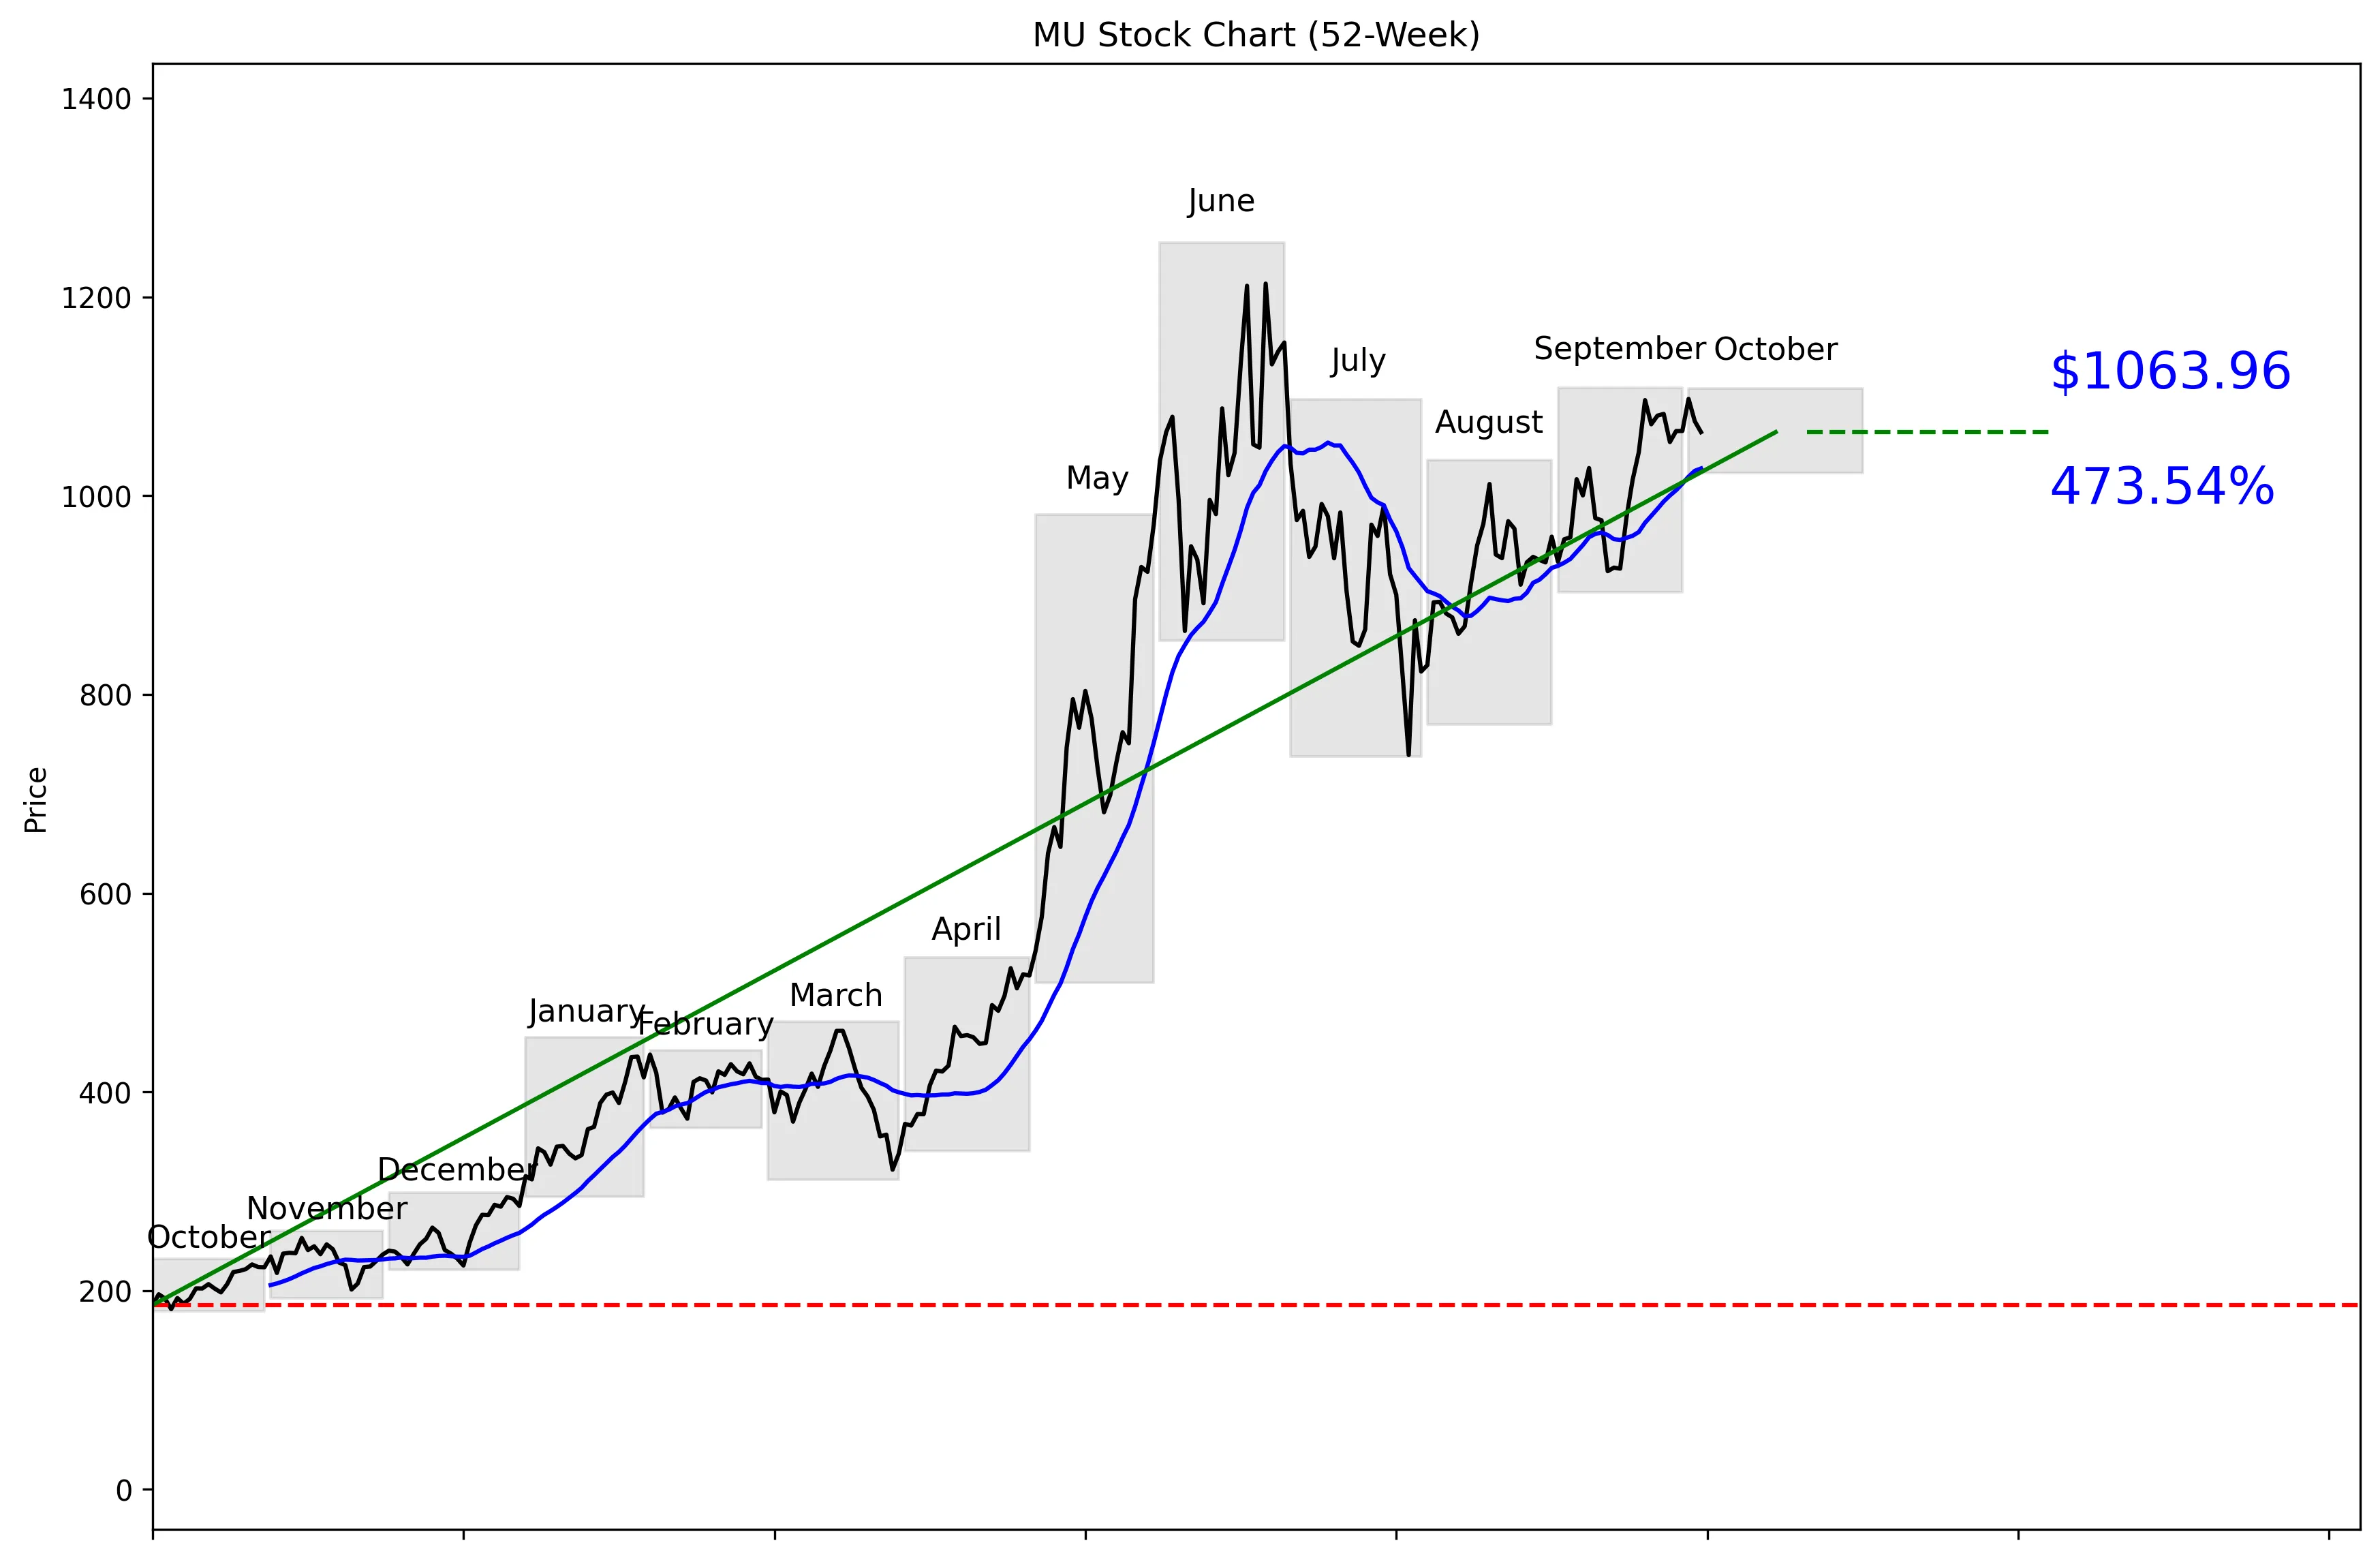
MU 52-Week Stock Chart
Technical Analysis
MU trades at $1063.38, 82% of the way from its $179.43 52-week low to its $1254.81 high. The stock is 15.21% below that high but 492.95% above the low. Price sits 3.56% above the 20-day moving average of $1027.37. Momentum remains positive at 0.95% over five trading days and 4.66% over 20 trading days. Near-term support is $910.43, while resistance sits at $1097.39.


Recent News and Developments

Micron posts record fiscal Q4 as revenue jumps 379%

Micron reported fiscal fourth-quarter revenue of $54.23 billion, up 379% year over year, with GAAP net income of $37.70 billion and adjusted earnings of $33.42 per share. It guided fiscal Q1 revenue to $61.5 billion, plus or minus $1.5 billion, with an adjusted gross margin near 86.25%. Source: Micron Technology

Micron expects memory shortages to worsen through 2028

Micron said memory and storage demand will exceed supply during 2027 and 2028, with tighter conditions than in 2026. The company has already sold most of its capacity for next year and expects NAND and DRAM shipments to grow in the low-to-mid-20% range during each of the next two years. Source: Tom’s Hardware

Analysts lift Micron targets as shares reverse early loss

Rosenblatt raised its Micron target to $1,900 from $1,500, DA Davidson moved to $2,100 from $2,000, and Mizuho increased its target to $1,400 from $1,300 while maintaining their existing ratings. MU recovered from an early decline of almost 4% and traded nearly 2% higher during the October 1 afternoon session. Source: Benzinga


Market Sentiment and Analyst Recommendations

Bull Case
Revenue growth of 379.3% is the core reason to own MU. Fiscal fourth-quarter revenue reached $54.23 billion, with GAAP net income of $37.70 billion and adjusted earnings of $33.42 per share. Management guided fiscal first-quarter revenue to $61.5 billion, plus or minus $1.5 billion, and an adjusted gross margin near 86.25%. Micron expects memory and storage demand to exceed supply during 2027 and 2028, and it has already sold most of next year’s capacity. New SSD, LPDDR5X, and LPDDR6 products give the company exposure to major customers across data-center and mobile applications. At 14.31 times earnings, with an analyst target of $1535.57 and a strong-buy recommendation from 46 analysts, the growth and valuation combination remains attractive.
Bear Case
MU has already climbed 492.95% from its 52-week low, so a large part of the good news is reflected in the price. The stock is only 3.11% below near-term resistance at $1097.39, while a drop to $910.43 support would represent a meaningful reversal. Analyst targets range from $361.00 to $2200.00, showing extreme disagreement about fair value. The gap between those targets is a warning that earnings expectations and valuation can move sharply. Micron also faces a patent fight with YMTC across the United States, China, Germany, the Unified Patent Court, and the United Kingdom. The company must execute against $61.5 billion in guided fiscal first-quarter revenue and an adjusted gross margin near 86.25%; falling short would directly challenge the current bull case.
What to Watch
The next major test is fiscal first-quarter revenue against guidance of $61.5 billion, plus or minus $1.5 billion. Adjusted gross margin should be measured against the company’s guidance of approximately 86.25%. Investors should track whether memory and storage demand continues to exceed supply and whether Micron still expects tight conditions through 2028. Shipment growth matters: the company expects NAND and DRAM shipments to rise in the low-to-mid-20% range during each of the next two years. Product execution is another catalyst, especially customer adoption of the 7600 PCIe Gen 5 SSD, 9650 PCIe Gen 6 SSD, six-channel 1-gamma LPDDR5X, and sampled 1-gamma LPDDR6 products. On the chart, a move above $1097.39 would clear near-term resistance, while a break below $910.43 would weaken the technical case.
Analyst Consensus
STRONG BUY

Based on 46 analyst opinions
Low Target
$361.00
Mean Target
$1535.57
High Target
$2200.00


Earnings and Financial Data

Sector
Technology
Industry
Semiconductors
Employees
N/A
Earnings & Dividends
Next Earnings
Dec 23, 2026
EPS (Trailing)
$74.33
Dividend Yield
6.0%
Payout Ratio
1.1%

Frequently Asked Questions

Is MU a good stock to buy?
MU carries a strong-buy recommendation from 46 analysts and trades at a P/E ratio of 14.31. Revenue growth is 379.3%, but the stock is already 492.95% above its 52-week low, so the takeaway is that MU has strong backing and growth with elevated price risk.
What is MU’s price target?
The analyst target is $1535.57, compared with a current price of $1063.38. The target range is exceptionally wide at $361.00 to $2200.00, so the takeaway is that analysts see upside on average but disagree sharply about valuation.
Is MU near its 52-week high?
MU trades at $1063.38, which is 15.21% below its $1254.81 52-week high. It sits 82% of the way from its $179.43 low to that high, so the takeaway is that MU remains near the upper end of its annual range.
What are MU’s support and resistance levels?
Near-term support is the 30-day low of $910.43, while resistance is the 30-day high of $1097.39. The takeaway is that these are the key levels for judging the stock’s next short-term move.
Does MU pay a dividend?
The provided data does not include dividend information. The takeaway is that investors should verify the current dividend directly before making an income-focused decision.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 06, 2026.