ALTSTATION.IO

D.R. Horton, Inc. (DHI) Stock Analysis

By Nova Skye | AltStation.io | Updated November 08, 2026

Price
$152.28
Change
-3.39%
Market Cap
$41.33B
Avg Volume
2.8M

Company Overview

D.R. Horton is the largest residential homebuilder in the United States, operating in the consumer cyclical sector across 126 markets in 36 states. Founded in 1978 and headquartered in Arlington, Texas, the company constructs and sells single-family detached homes, townhomes, and duplexes directly to everyday homebuyers. Beyond standard construction, they run an in-house financial engine providing mortgage origination and title agency services, alongside a dedicated residential lot development operation. They also build, lease, and sell single-family and multi-family rental properties, while holding ancillary assets including water rights and ranch land.

Horton is the undisputed volume leader in American residential construction, holding the number one spot by deliveries every year since 2002. The company accounts for upwards of 13% of all new home sales nationwide, giving it massive cost advantages in materials and subcontractor labor over rivals like Lennar and PulteGroup. Their core moat is an entry-level, fast-turnaround spec building model designed to maximize turnover rather than premium pricing. The primary headwind threatening this volume strategy is mortgage rate pressure, which forces them to subsidize buyer financing to keep inventory moving off the books.

The company is currently navigating a cyclical contraction by choosing volume preservation over peak pricing power. Total revenue dropped roughly 7% from $36.8 billion in fiscal 2024 to approximately $34.3 billion in fiscal 2025 as higher financing costs cooled buyer demand. Despite that revenue dip, Horton delivered 84,863 homes in its core operations in fiscal 2025, alongside 3,460 single-family rental homes and 2,947 multi-family rental units. Their current strategy is straightforward: sacrifice some margin through rate buydowns to sustain cash generation and squeeze smaller, capital-constrained builders out of regional markets.

Key Financials
Market Cap
$41.33B
Revenue
$33.04B
EBITDA
$3.81B
Gross Margin
20.6%
Profit Margin
8.7%
Revenue Growth
-3.2%
Total Cash
$2.06B
Total Debt
$6.05B
Free Cash Flow
$7.82B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
15.06
Forward P/E
14.10
Beta
1.37
52-Week High
$170.79
52-Week Low
$130.40
EPS
$10.11
50-Day Avg
$141.26
200-Day Avg
$147.49
Price/Book
1.79
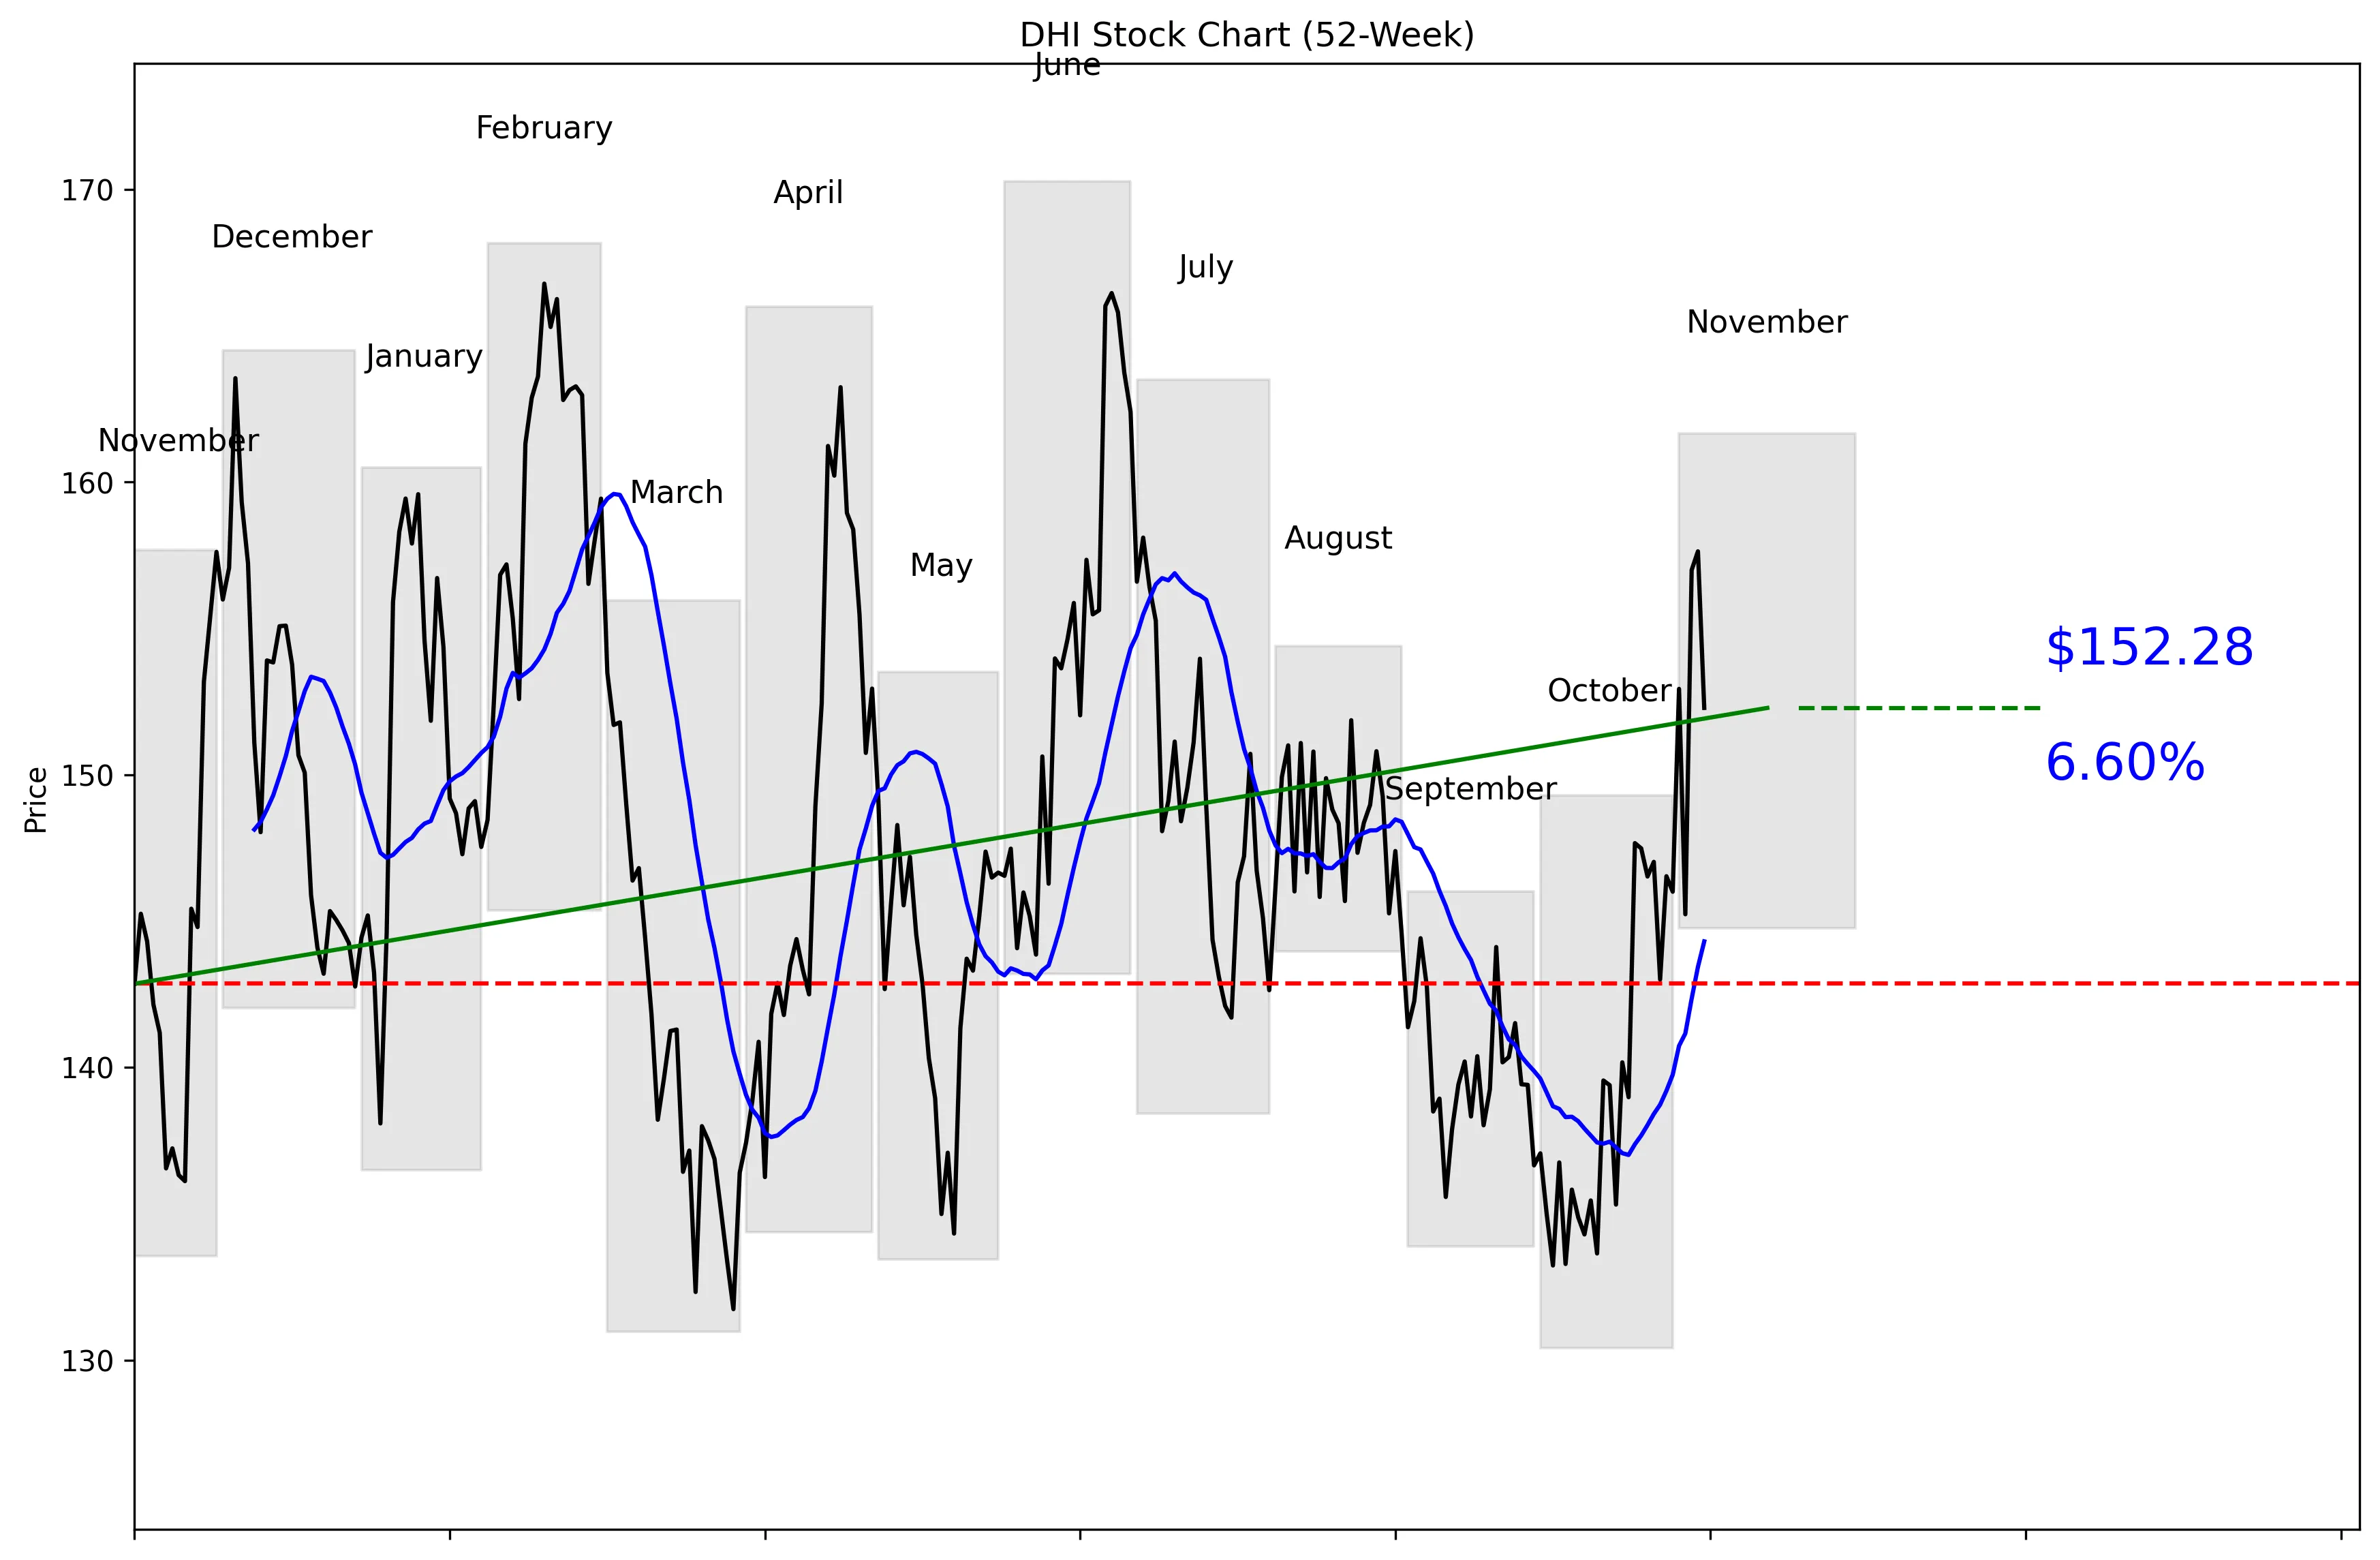
DHI 52-Week Stock Chart
Technical Analysis
DHI trades at $152.28, 55% of the way from its $130.40 52-week low to its $170.28 high. The stock is 10.57% below that high and 16.78% above the low. Price sits 5.53% above the 20-day moving average of $144.30. Momentum is positive at 4.30% over five trading days and 12.90% over 20 trading days. Near-term support is $133.23, while resistance is $157.63.


Recent News and Developments

Raymond James cuts D.R. Horton to Underperform

Raymond James downgraded DHI from Market Perform to Underperform on November 3 without setting a price target. The firm cited the fiscal fourth-quarter earnings miss, weak fiscal 2027 guidance, aggressive valuation and rising competition from resale inventory in Sun Belt markets. Source: TipRanks

Morgan Stanley slashes DHI target to $130

Morgan Stanley maintained its Equal-Weight rating on November 3 but cut its price target from $151 to $130. The new target was 14.84% below the reported $152.65 share price. Source: Benzinga

Citigroup raises DHI target to $152

Citigroup maintained its Neutral rating on November 2 and raised its price target from $150 to $152. The revised target still offered no meaningful upside from DHI’s reported market price. Source: MarketBeat


Market Sentiment and Analyst Recommendations

Bull Case
D.R. Horton generates $33.04 billion in revenue against a $41.33 billion market cap. The stock trades at 15.06 times earnings, which is not an aggressive multiple by itself. DHI also holds $2.06 billion in cash, giving it meaningful financial flexibility despite its debt load. The technical picture has improved, with the stock 5.53% above its 20-day moving average and up 12.90% over 20 trading days. A break above the $157.63 near-term resistance level would strengthen the momentum case. The most optimistic analyst target is $186.00, providing a clear upside scenario for investors who believe the earnings pressure is temporary.
Bear Case
Revenue growth is negative at 3.2%, so the company is not currently backing its valuation with top-line expansion. Total debt of $6.05 billion is nearly three times the $2.06 billion cash position. The $146.50 consensus analyst target sits below the current $152.28 share price. Morgan Stanley cut its target from $151 to $130 on November 3 while keeping an Equal-Weight rating. Raymond James downgraded DHI to Underperform, citing an earnings miss, weak fiscal 2027 guidance, aggressive valuation and rising resale competition in Sun Belt markets. Lower expected selling prices, higher buyer incentives and pressure on home-sales gross margins contributed to a 5.0% decline on November 3 even as the S&P 500 gained 0.4%. The downside analyst target of $114.00 shows how severe the repricing could become if those pressures persist.
What to Watch
The first test is $157.63, the 30-day high and the stock’s near-term resistance level. A sustained move above it would support the recent 4.30% five-day and 12.90% 20-day momentum readings. A drop below the $144.30 moving average would weaken that setup, while $133.23 is the next listed support level. Investors should watch whether revenue growth improves from negative 3.2% and whether selling prices, buyer incentives and gross margins stabilize. The gap between $6.05 billion in debt and $2.06 billion in cash also deserves attention. No next-quarter earnings date was provided, but the next company update needs to address weak fiscal 2027 guidance and the growing competition from resale inventory.
Analyst Consensus
HOLD

Based on 14 analyst opinions
Low Target
$114.00
Mean Target
$146.50
High Target
$186.00


Earnings and Financial Data

Sector
Consumer Cyclical
Industry
Residential Construction
Employees
N/A
Earnings & Dividends
Next Earnings
Jan 19, 2027
EPS (Trailing)
$10.11
Dividend Yield
131.0%
Payout Ratio
16.7%

Frequently Asked Questions

Is DHI a good stock to buy?
Fourteen analysts rate DHI a hold, and the $146.50 consensus target is below the current $152.28 price. The clear takeaway is that the available analyst data does not support an outright buy call.
What is DHI’s price target?
The consensus analyst target is $146.50, with estimates ranging from $114.00 to $186.00. The takeaway is that analyst expectations are unusually wide and the consensus implies no upside from $152.28.
Is DHI stock overvalued?
DHI trades at a P/E ratio of 15.06 while revenue growth is negative 3.2%. The takeaway is that the multiple is moderate, but shrinking revenue makes the valuation less compelling.
What are DHI’s support and resistance levels?
Near-term support is $133.23, and near-term resistance is $157.63. The takeaway is that $157.63 is the key upside level and $133.23 is the listed downside level to watch.
How far is DHI from its 52-week high?
DHI is 10.57% below its $170.28 52-week high and 16.78% above its $130.40 low. The takeaway is that the stock sits near the middle of its annual range, at 55% of the distance from low to high.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated November 08, 2026.