ALTSTATION.IO

EQT Corporation (EQT) Stock Analysis

By Nova Skye | AltStation.io | Updated November 04, 2026

Price
$54.95
Change
+0.20%
Market Cap
$34.37B
Avg Volume
7.7M

Company Overview

EQT Corporation is an oil and gas exploration and production company headquartered in Canonsburg, Pennsylvania. Operating in the energy sector, the company focuses on extracting, gathering, and transmitting natural gas, natural gas liquids, and oil. They sell these commodities directly to utilities, industrial buyers, and commercial marketers across the Appalachian Basin. Beyond extraction, they generate revenue through commercial marketing services, pipeline capacity management, and propane storage and distribution terminals.

Founded in 1888, EQT operates as an established Appalachian Basin specialist with over 135 years of operating history. Their primary competitive edge comes from operational integration: linking wellhead extraction directly to gathering, transmission, and terminal storage gives them tighter logistics control than fragmented peers. The main threat is geographic concentration, which leaves their realized prices vulnerable to regional pipeline bottlenecks and local basis discounts. They lean heavily on active hedging and capacity management contracts to protect cash flows, but commodity swings remain their biggest operational headwind.

After rebranding from Equitable Resources Inc. in February 2009, the business solidified its strategic identity around Appalachian hydrocarbons and midstream coordination. Today, EQT is focused on commercial optimization and disciplined asset execution rather than speculative exploration. They rely on their marketing and pipeline capacity rights to ensure their volume reaches end-users reliably. It is a mature, infrastructure-supported operation built for steady execution, though its financial upside remains tied directly to regional natural gas pricing.

Key Financials
Market Cap
$34.37B
Revenue
$9.15B
EBITDA
$6.78B
Gross Margin
80.4%
Profit Margin
29.0%
Revenue Growth
-8.1%
Total Cash
$78.72M
Total Debt
$5.55B
Free Cash Flow
$2.48B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
13.02
Forward P/E
15.66
Beta
0.67
52-Week High
$68.24
52-Week Low
$47.94
EPS
$4.22
50-Day Avg
$53.22
200-Day Avg
$55.60
Price/Book
1.35
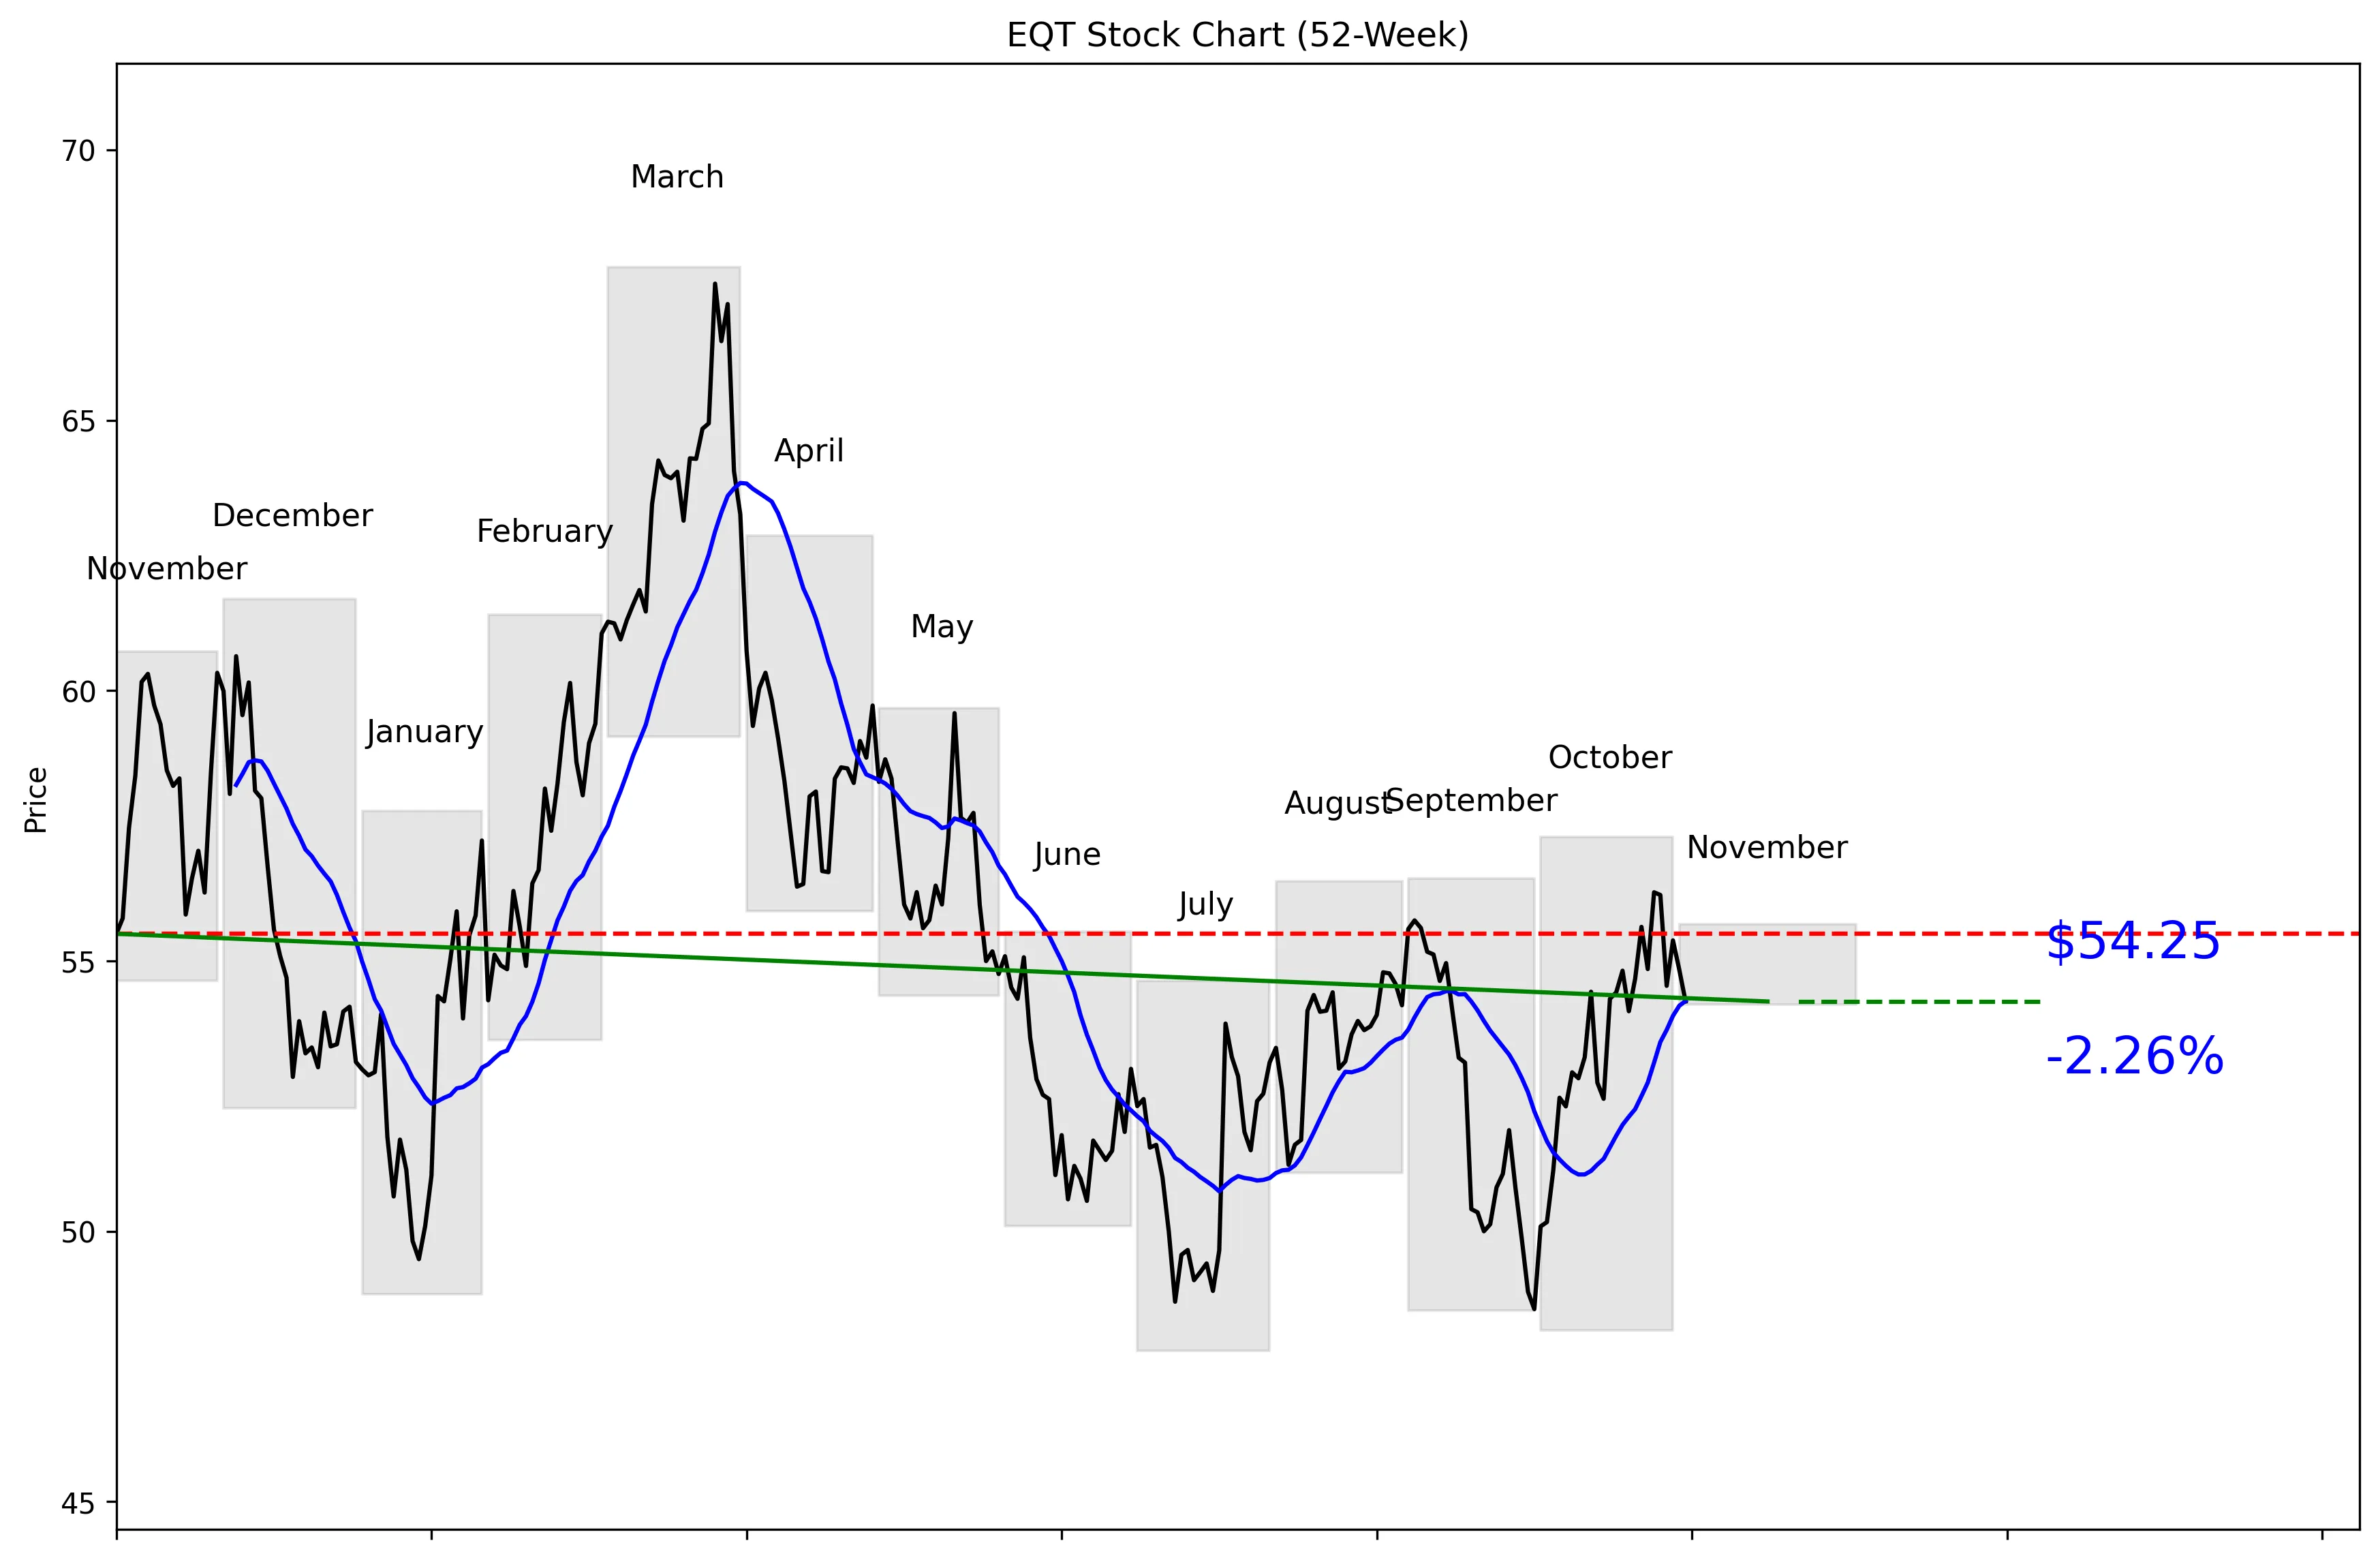
EQT 52-Week Stock Chart
Technical Analysis
EQT trades at $54.95, 32% of the way from its exact 52-week low of $47.79 to its exact 52-week high of $67.84. The stock is 20.03% below that high and 13.52% above the low. Price is listed at 0.02% below its 20-day moving average of $54.26, while 20-day momentum remains positive at 3.39%. The last five trading days were weaker, with momentum at -3.59%. Near-term support is $48.56, while $56.27 is the immediate resistance level.


Recent News and Developments

EQT presses its case for the Range Resources deal

EQT filed an October 29 CNBC interview transcript discussing its proposed all-stock acquisition of Range Resources. The transaction is valued at $13 billion, or roughly $50 billion including debt and enterprise value. Source: Range Resources Investor Relations

Truist raises EQT target to $70

Truist Securities analyst Gabe Daoud maintained a Buy rating on November 2. He raised the price target from $65 to $70. Source: Benzinga

UBS trims EQT target but keeps Buy rating

UBS analyst Josh Silverstein cut the EQT price target from $75 to $74 on October 29. The firm maintained its Buy rating. Source: Yahoo Finance


Market Sentiment and Analyst Recommendations

Bull Case
EQT offers a clear value setup at $54.95 and 13.02 times earnings. The consensus analyst target of $66.50 represents meaningful upside from the current price, while the most bullish target reaches $77.00. Wall Street sentiment is strong, with 22 analysts assigning a strong_buy recommendation. Truist reinforced that view on November 2 by raising its target from $65 to $70 and maintaining a Buy rating. UBS also kept its Buy rating on October 29, even after trimming its target from $75 to $74. The stock sits just 32% of the way through its 52-week range, so investors are not being asked to buy near the top.
Bear Case
Revenue growth is negative at -8.1%, which is the clearest fundamental problem in the data. EQT also carries $5.55 billion in total debt against only $78.72 million in cash. That balance-sheet gap raises the stakes for the proposed all-stock Range Resources acquisition, a transaction valued at $13 billion and roughly $50 billion including debt and enterprise value. The stock has already fallen 20.03% from its exact 52-week high, showing that analyst optimism has not translated into sustained price strength. Five-day momentum is -3.59%, and the shares recently failed to hold their October 30 rebound. The bear case wins if revenue keeps shrinking, deal risk grows, or the stock breaks its $48.56 near-term support.
What to Watch
The proposed Range Resources acquisition is the main catalyst and the main execution risk. Investors should track developments following EQT’s October 29 interview discussing the $13 billion all-stock transaction and its roughly $50 billion value including debt and enterprise value. Price action around $56.27 matters because that is the 30-day high and immediate resistance. A break below the $48.56 30-day low would weaken the technical setup and move the stock closer to its exact 52-week low of $47.79. Revenue growth must improve from -8.1%, while the $5.55 billion debt load deserves close attention. Analyst support remains strong, but investors should watch whether future targets continue to cluster around the current $66.50 consensus or move toward the low end of the $52.00 to $77.00 range.
Analyst Consensus
STRONG BUY

Based on 22 analyst opinions
Low Target
$52.00
Mean Target
$66.50
High Target
$77.00


Earnings and Financial Data

Sector
Energy
Industry
Oil & Gas E&P
Employees
1,523
Earnings & Dividends
Next Earnings
Oct 27, 2026
EPS (Trailing)
$4.22
Dividend Yield
124.0%
Payout Ratio
15.6%

Frequently Asked Questions

Is EQT a good stock to buy?
EQT has a strong_buy recommendation from 22 analysts and trades at a P/E ratio of 13.02. Revenue growth is -8.1%, so the clear takeaway is that EQT offers analyst-backed upside with a real growth risk.
What is EQT’s price target?
The consensus analyst target is $66.50, with estimates ranging from $52.00 to $77.00. The takeaway is that analysts see upside from the current $54.95 price, although the lowest target is below it.
Is EQT stock undervalued?
EQT trades at 13.02 times earnings and sits 32% of the way from its exact 52-week low of $47.79 to its exact high of $67.84. The takeaway is that the valuation and range position look attractive, but negative revenue growth prevents a clean undervaluation call.
What are EQT’s support and resistance levels?
Near-term support is the 30-day low of $48.56, while resistance is the 30-day high of $56.27. The takeaway is that EQT is trading closer to resistance than support at its current $54.95 price.
How much debt does EQT have?
EQT has $5.55 billion in total debt and $78.72 million in total cash. The takeaway is that debt is a major financial risk investors should monitor.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated November 04, 2026.