ALTSTATION.IO

Occidental Petroleum Corporation (OXY) Stock Analysis

By Nova Skye | AltStation.io | Updated November 04, 2026

Price
$56.91
Change
-5.82%
Market Cap
$56.89B
Avg Volume
8.5M

Company Overview

Occidental Petroleum Corporation (OXY) is an upstream energy company founded in 1920 and headquartered in Houston, Texas. The company operates in the oil and gas exploration and production (E&P) industry through two primary reporting segments: Oil and Gas, and Midstream and Marketing. It extracts and sells crude oil, condensate, natural gas liquids (NGLs), and natural gas to refiners, commercial distributors, and industrial consumers across the United States and international markets. Its midstream business manages the gathering, processing, storage, and transportation of hydrocarbons, carbon dioxide, and power supplies.

Occidental holds a market-leading footprint in the United States as one of the largest crude producers and acreage holders across the Permian Basin. Its primary competitive edge is technical leadership in Enhanced Oil Recovery (EOR), backed by over 50 years of experience injecting carbon dioxide into mature reservoirs to maximize extraction. Unlike pure-play peers like EOG Resources and Devon Energy, or integrated majors like ExxonMobil and Chevron, Oxy pairs high-density Permian acreage with extensive proprietary carbon dioxide pipeline infrastructure. However, without downstream refining assets to cushion downturns, its cash flows remain directly exposed to volatile benchmark crude prices.

Right now, Occidental is executing a dual-track strategy to protect its core hydrocarbon cash generation while pivoting aggressively into carbon management. The company is expanding its Low Carbon Ventures division, highlighted by the development of Stratos in the Permian Basin as one of the world’s largest commercial Direct Air Capture facilities. This commercial carbon capture push is a bold operational differentiator that traditional upstream competitors are not matching at equal scale. Oxy is no longer just a conventional oil play, and its valuation hinges on sustaining low-cost Permian production while proving that industrial-scale carbon capture can generate durable returns.

Key Financials
Market Cap
$56.89B
Revenue
$23.93B
EBITDA
$13.72B
Gross Margin
73.3%
Profit Margin
30.3%
Revenue Growth
53.4%
Total Cash
$4.15B
Total Debt
$14.63B
Free Cash Flow
$3.79B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
16.17
Forward P/E
11.35
Beta
0.15
52-Week High
$67.45
52-Week Low
$38.80
EPS
$3.52
50-Day Avg
$60.18
200-Day Avg
$56.24
Price/Book
1.70
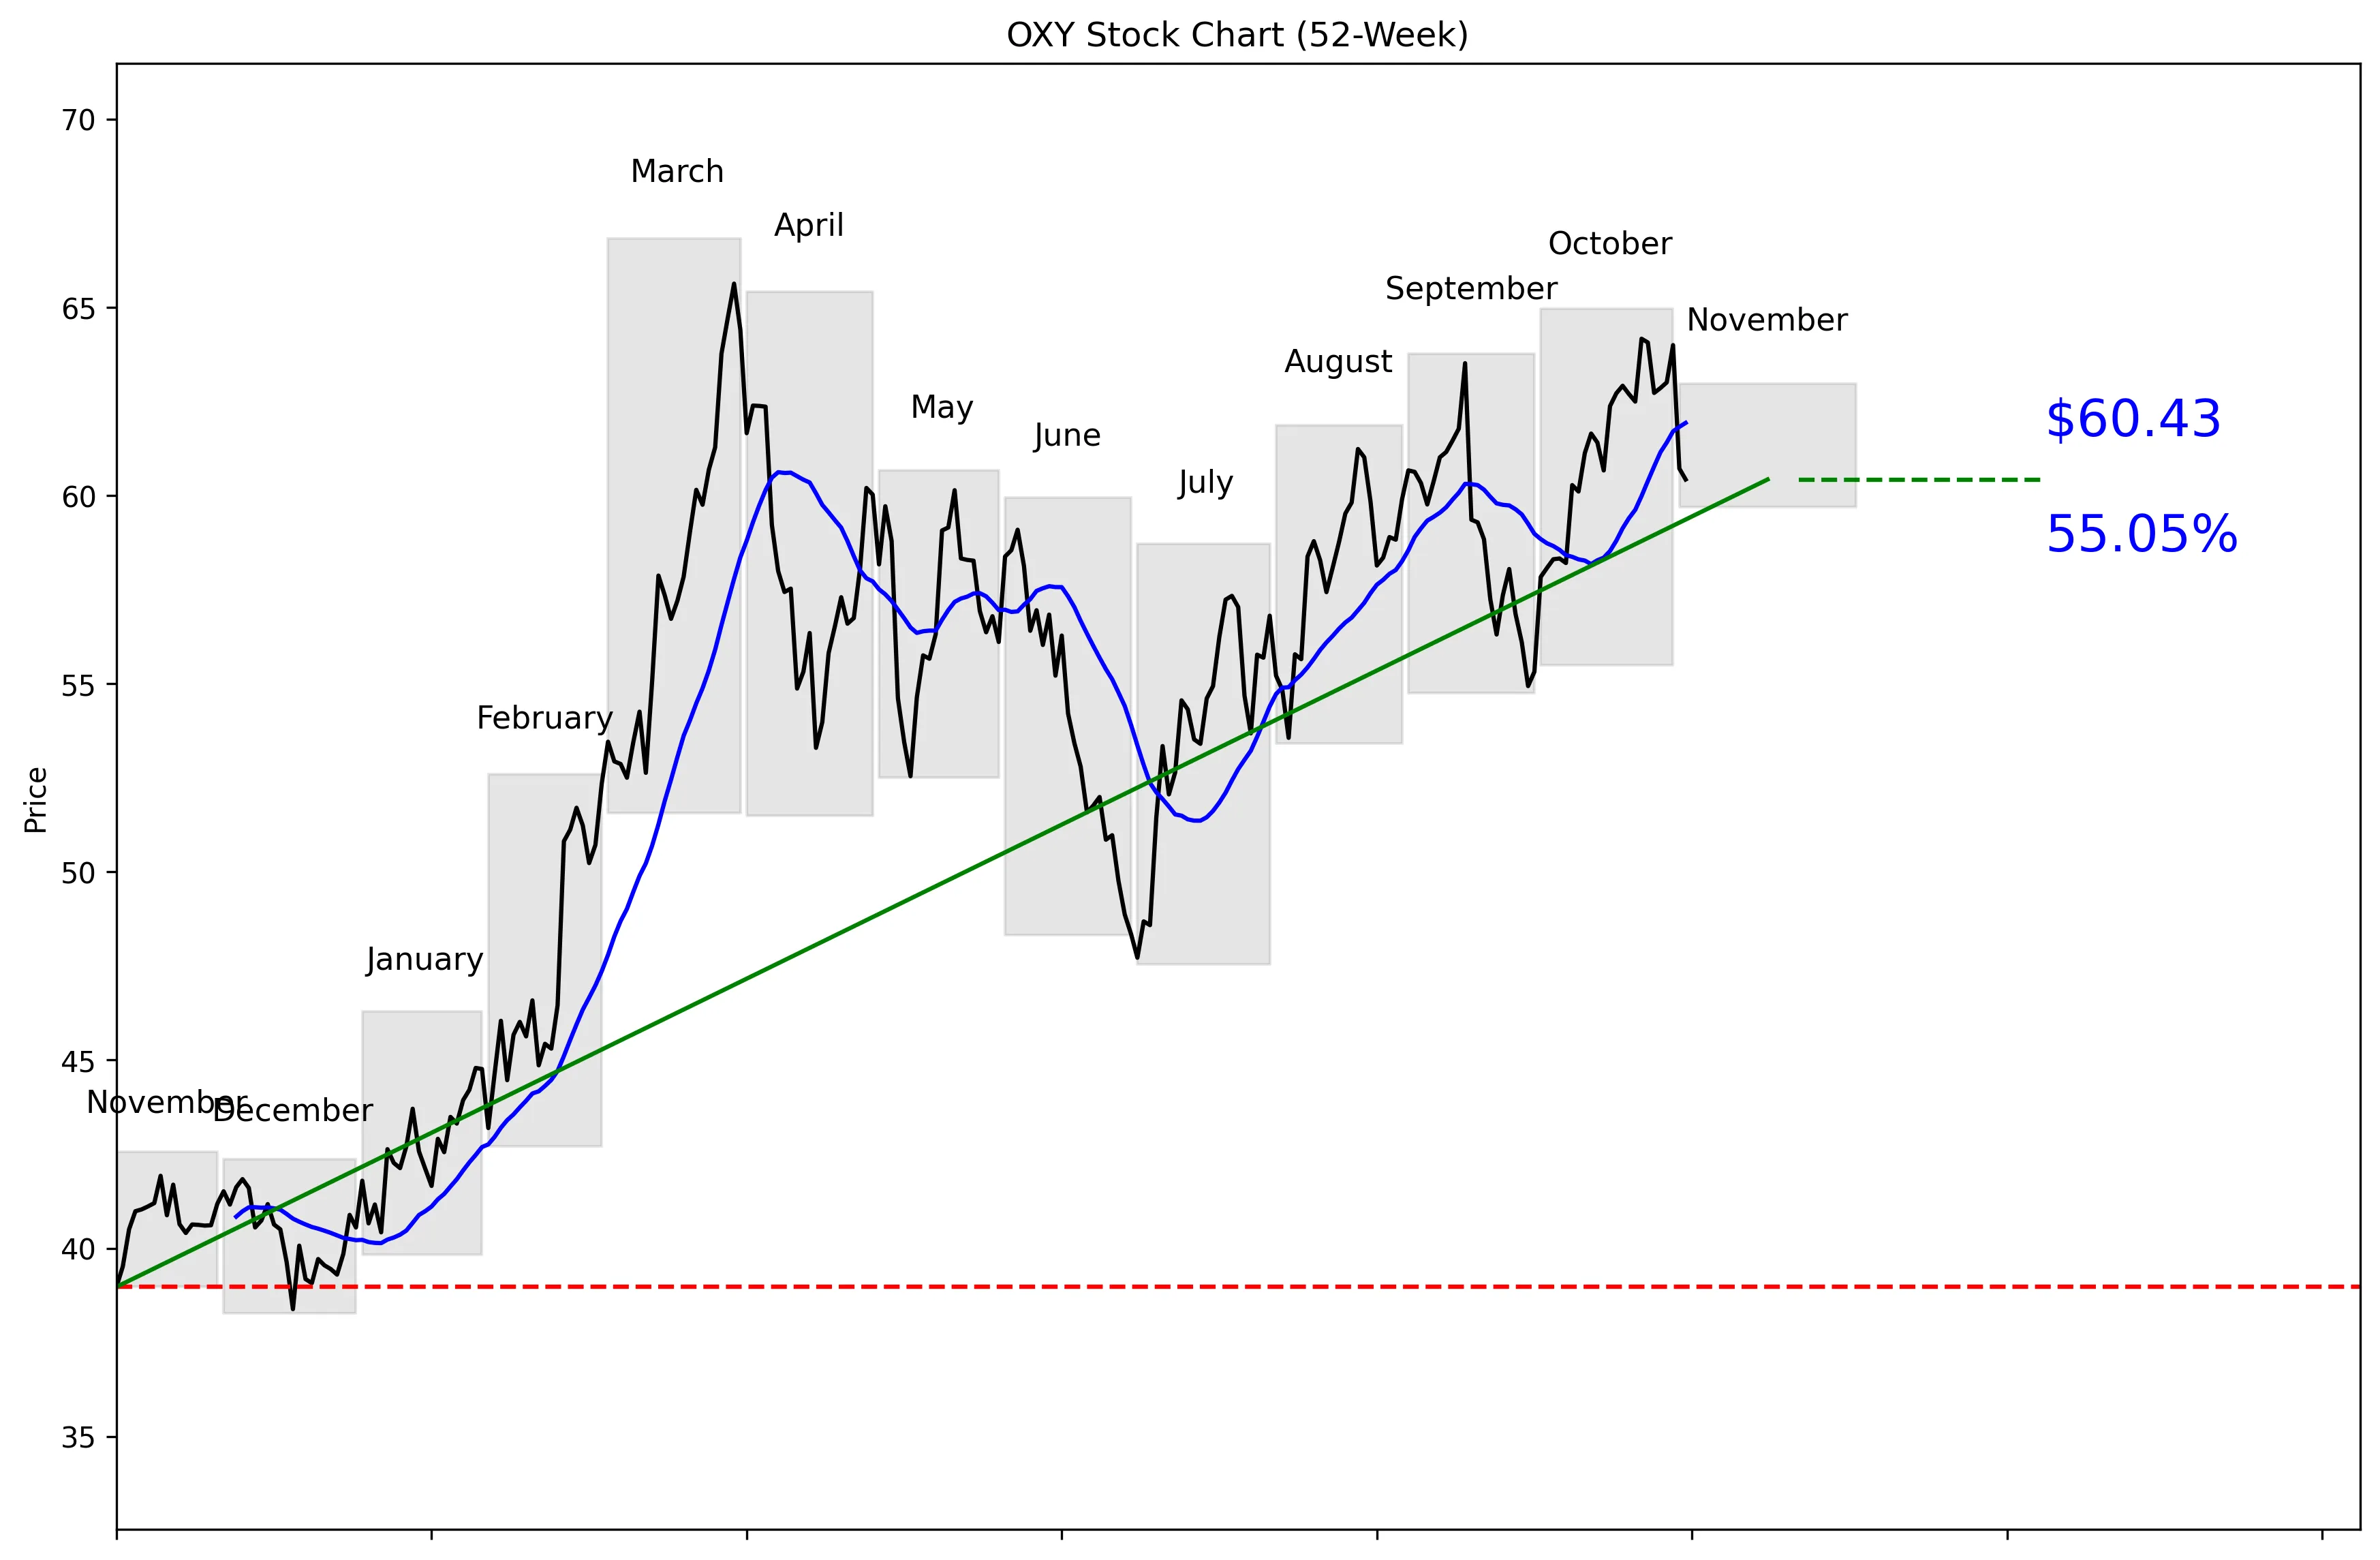
OXY 52-Week Stock Chart
Technical Analysis
OXY trades at $56.91, placing it 78% of the way from its $38.26 52-week low to its $66.83 high. The stock is 9.58% below that high and 57.93% above the low. Price is 2.43% below the 20-day moving average of $61.93, while five-day momentum is negative 3.67%. The 20-day trend remains positive at 3.60%, so the recent weakness has not erased the broader move. Near-term support is $54.94, while $64.17 is the resistance level buyers need to clear.


Recent News and Developments

OXY earnings set for November 9

Occidental will report third-quarter results after the close on November 9, followed by a November 10 conference call. Analysts expect earnings of $1.45 per share on $6.80 billion in revenue. Source: MarketBeat

OXY drops 5.13% ahead of earnings

OXY closed at $60.72 on November 2, down 5.13% on volume of 12,677,152 shares. It fell another 0.48% to $60.43 on November 3. Source: Stock Analysis

Kazakhstan exchange restricts OXY repo trading

The Kazakhstan Stock Exchange suspended OXY_KZ repo trading involving central-counterparty settlements dated December 10 or later. KASE said trading will resume December 14 and linked the restriction to the closing of the shareholder register for dividend payment. Source: Kazakhstan Stock Exchange


Market Sentiment and Analyst Recommendations

Bull Case
Revenue growth of 53.4% is the clearest reason to own OXY. The company generates $23.93 billion in revenue and carries a P/E of 16.17, which leaves room for upside if that growth continues. Analysts rate the stock a buy, based on 27 analysts. Their average target is $70.74, above the current $56.91 price, with estimates ranging from $60.00 to $82.00. The November 9 earnings report is the next major catalyst, with analysts expecting $1.45 per share on $6.80 billion in revenue. OXY is also 9.58% below its technical 52-week high, giving buyers a defined recovery opportunity without paying the peak price.
Bear Case
OXY has $14.63 billion in total debt against $4.15 billion in cash, a balance-sheet gap investors cannot ignore. The stock sits below its $61.93 20-day moving average, and five-day momentum is negative 3.67%. It closed down 5.13% at $60.72 on November 2, then fell another 0.48% to $60.43 on November 3, showing clear selling pressure ahead of earnings. At $56.91, the stock is only $1.97 above near-term support at $54.94. A break below that level would weaken the chart, while resistance at $64.17 leaves a meaningful hurdle overhead. Sumitomo Mitsui Trust Group also reduced its stake by 1.6%, selling 27,027 shares, although it retained 1,659,317 shares valued at $91.8 million.
What to Watch
The November 9 third-quarter earnings report is the immediate test. Analysts expect earnings of $1.45 per share and revenue of $6.80 billion, followed by the company’s conference call on November 10. Investors should compare those results with the reported 53.4% revenue growth rate to judge whether the growth story still holds. On the chart, $54.94 is the key downside threshold; losing it would break the stated near-term support. On the upside, OXY needs to reclaim its $61.93 20-day moving average and then clear $64.17 resistance. Debt of $14.63 billion and cash of $4.15 billion should also be tracked for evidence that the balance sheet is improving or deteriorating. The Kazakhstan Stock Exchange restriction is scheduled to end when OXY_KZ repo trading resumes December 14.
Analyst Consensus
BUY

Based on 27 analyst opinions
Low Target
$60.00
Mean Target
$70.74
High Target
$82.00


Earnings and Financial Data

Sector
Energy
Industry
Oil & Gas E&P
Employees
10,412
Earnings & Dividends
Next Earnings
Nov 09, 2026
EPS (Trailing)
$3.52
Dividend Yield
185.0%
Payout Ratio
28.4%

Frequently Asked Questions

Is OXY a good stock to buy?
The current recommendation is buy, based on 27 analysts, and revenue growth is 53.4%. The takeaway is that analysts and growth data support the bull case, but the recommendation is not unanimous detail because no rating breakdown was provided.
What is OXY’s price target?
The average analyst target is $70.74, with a range of $60.00 to $82.00. The takeaway is that every provided target sits above the current $56.91 price.
What is OXY’s 52-week high and low?
The technical price series shows a 52-week high of $66.83 and a low of $38.26. The takeaway is that OXY trades 9.58% below the high and 57.93% above the low.
What are OXY’s support and resistance levels?
Near-term support is the 30-day low of $54.94, while resistance is the 30-day high of $64.17. The takeaway is that these are the clearest supplied levels for tracking the next move.
Does OXY pay a dividend?
The provided key and technical data do not include a dividend amount or yield. The takeaway is that no dividend conclusion can be made from the supplied data.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated November 04, 2026.