
Diamondback Energy, Inc. (FANG) Stock Analysis
By Nova Skye | AltStation.io | Updated October 17, 2026
Company Overview
Diamondback Energy is an independent oil and natural gas exploration and production company headquartered in Midland, Texas. They drill for and extract crude oil, natural gas, and natural gas liquids from unconventional onshore shale in the Permian Basin. They sell these raw energy commodities wholesale to pipeline operators, midstream marketers, and petroleum refiners. Operating in the energy sector since 2007, the company focuses exclusively on upstream development across the Midland and Delaware Basins.
Diamondback is a dominant pure-play market leader in the Permian, controlling approximately 838,000 net acres across West Texas and New Mexico. Their primary competitive edge is low-cost execution, anchored by more than 6,100 drilling locations that break even below $40 per barrel of WTI crude. They compete directly against integrated energy giants like ExxonMobil and Chevron for acreage and midstream capacity. Commodity price swings are their biggest operational risk, but their low cost structure provides a wide defensive cushion.
The company is currently expanding its operational footprint after closing a $26 billion acquisition of Endeavor Energy Resources in September 2024. That deal added roughly 362,000 net acres and boosted net production capacity to approximately 816,000 barrels of oil equivalent per day. The strategic focus has now shifted to integrating these contiguous Midland Basin assets to capture an estimated $550 million in annual cost synergies. Diamondback stockholders own about 60.5% of the combined entity, which is positioned to return substantial free cash flow through buybacks and dividends.
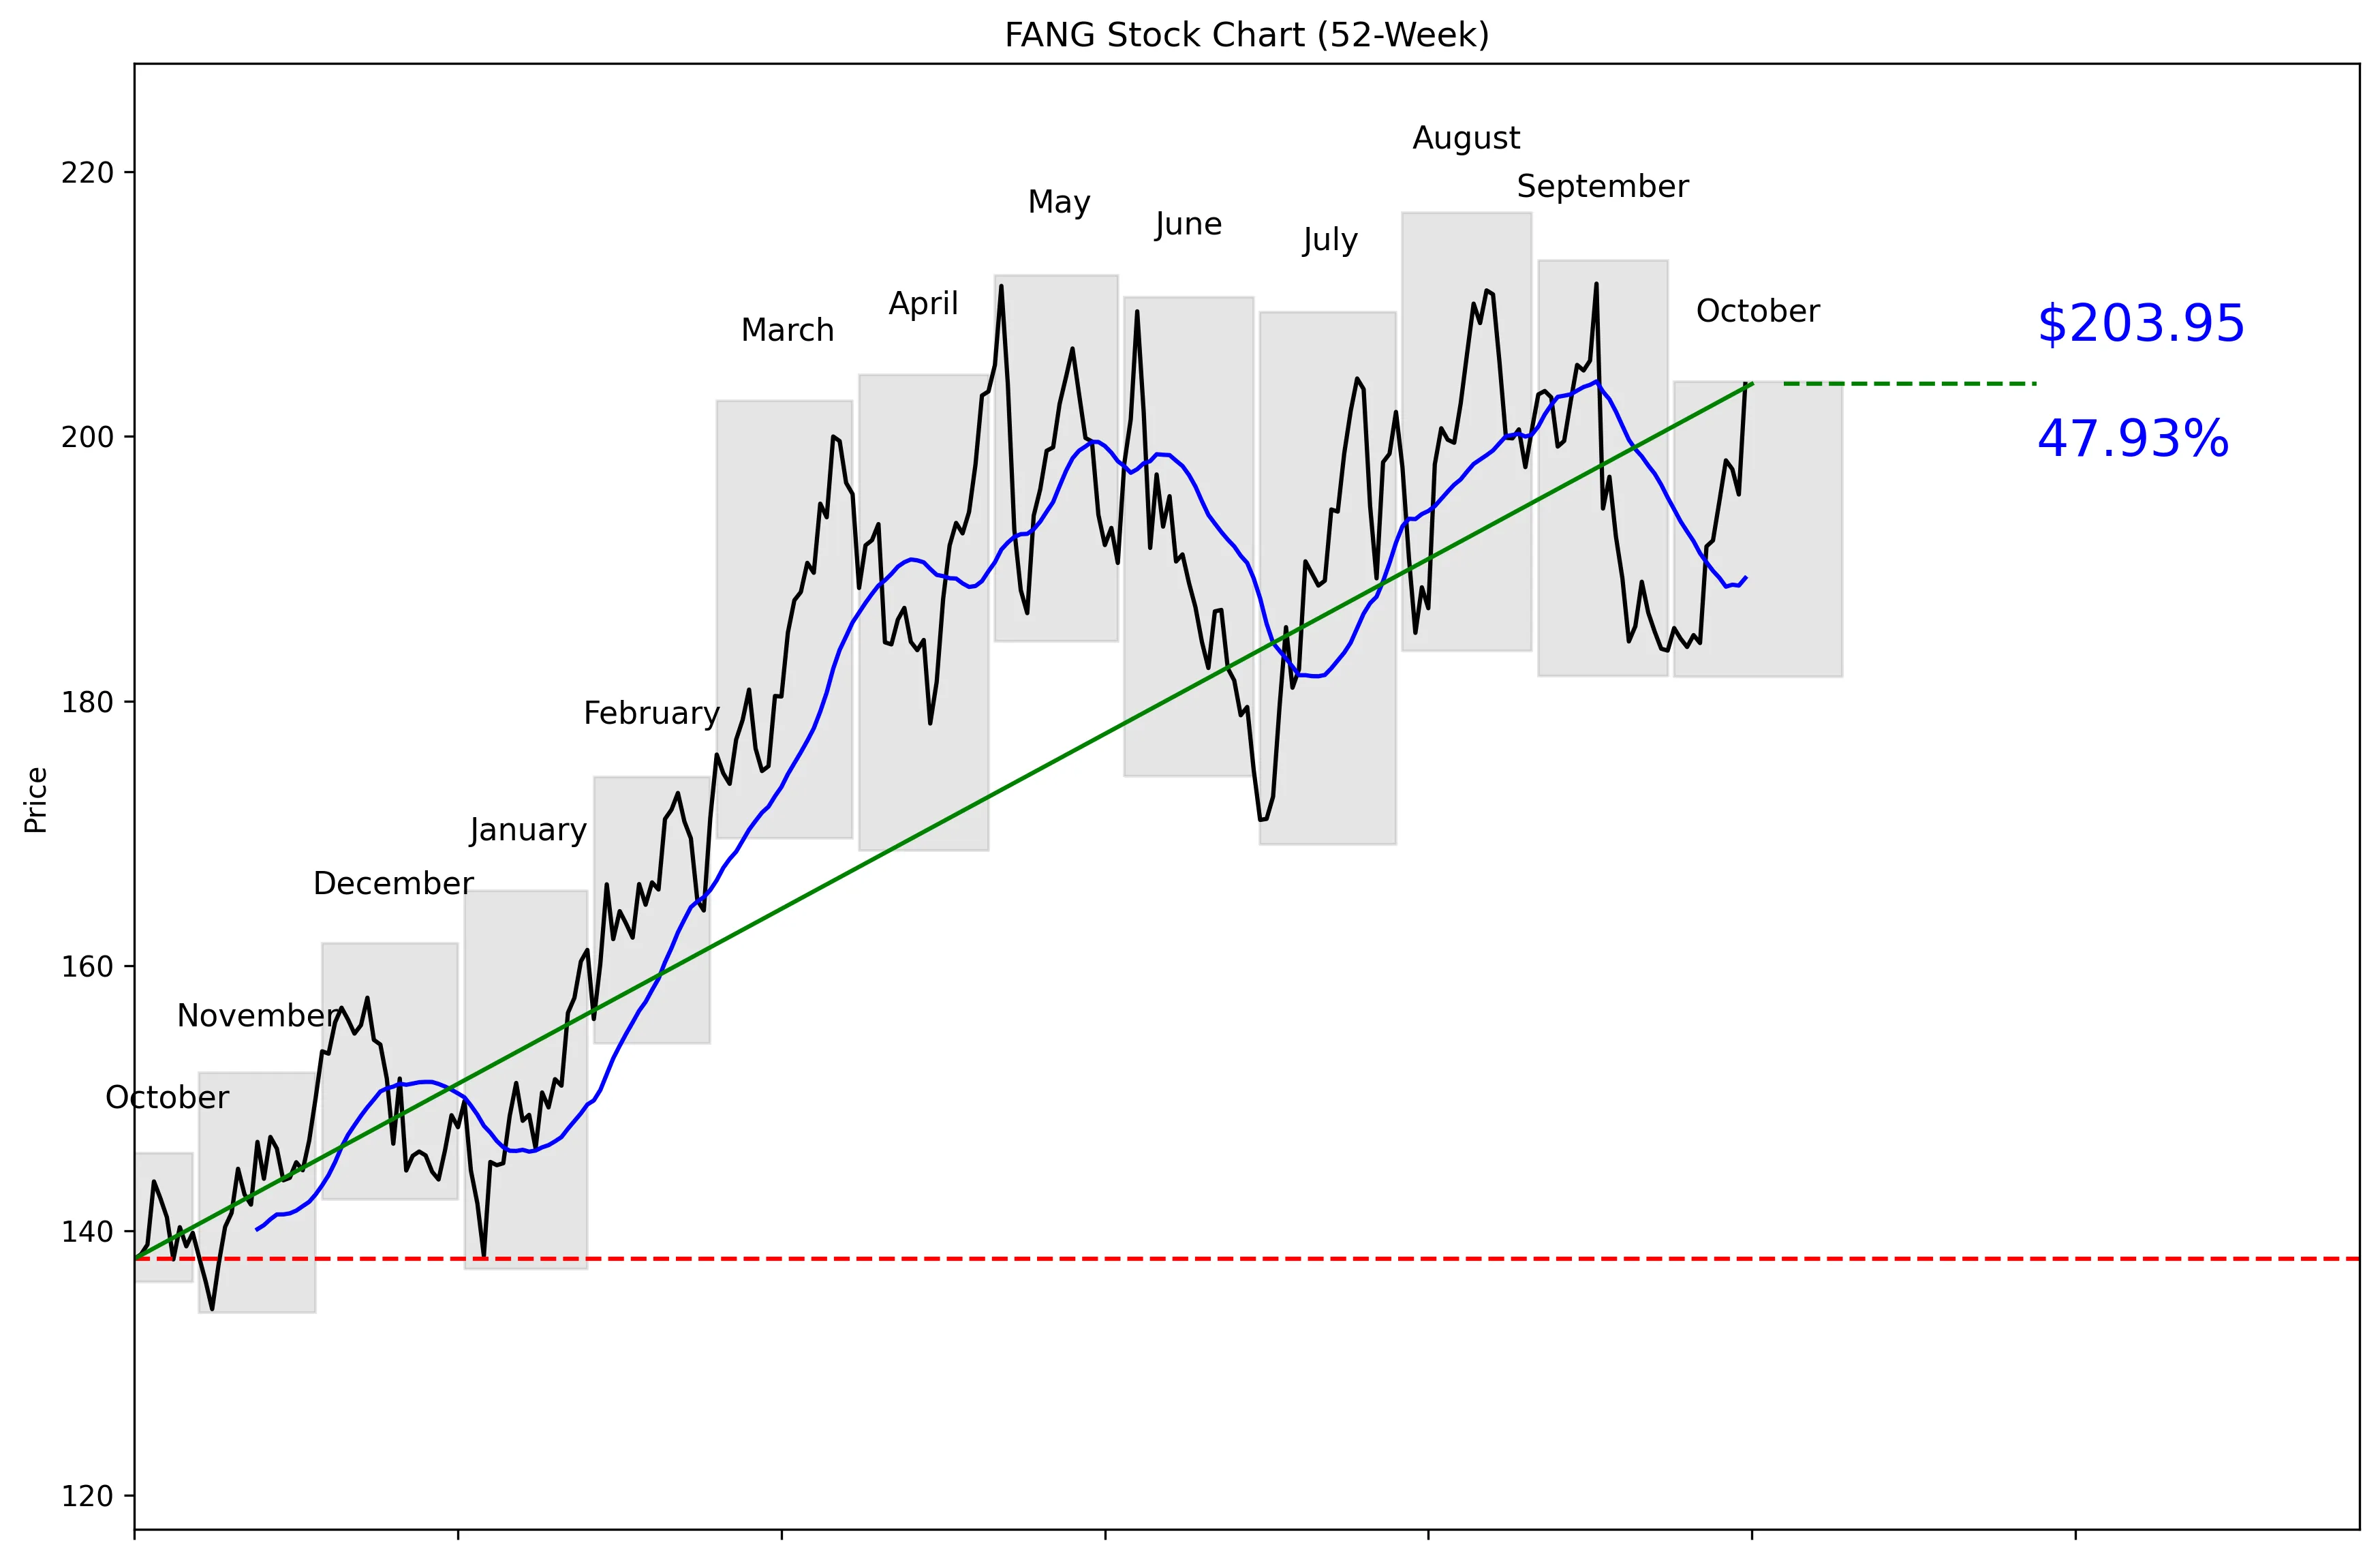
52-Week Price Performance Analysis
Recent News and Developments
Scotiabank initiated coverage of Diamondback Energy on October 15 with a Sector Outperform rating. The firm set a $250 price target. Source: Stock Target Advisor
Morgan Stanley raised its Diamondback Energy price target from $216 to $222 on October 15, a 2.78% increase. Analyst Devin McDermott kept an Equal-Weight rating. Source: GuruFocus
Mizuho reiterated its Outperform rating and $240 price target on October 13. Analyst Nitin Kumar expects Diamondback’s 2027 capital budget to run roughly 5% above the current Street consensus, partly because of a higher Barnett-well mix and cost inflation. Source: StreetInsider
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports