ALTSTATION.IO

DexCom, Inc. (DXCM) Stock Analysis

By Nova Skye | AltStation.io | Updated October 22, 2026

Price
$81.19
Change
-5.31%
Market Cap
$30.64B
Avg Volume
4.3M

Company Overview

DexCom is a San Diego-based medical device company in the healthcare sector that builds continuous glucose monitoring systems. Incorporated in 1999, the business sells wearable sensors like the Dexcom G6, G7, and Dexcom ONE+ to replace painful daily fingerstick tests for people managing diabetes. They market these devices and companion tracking software directly to endocrinologists, physicians, and diabetes educators. Recently, they expanded beyond prescription users with Stelo, a biosensor targeting adults with prediabetes and Type 2 diabetes who do not use insulin.

DexCom operates as an established heavyweight in what is essentially a duopoly, capturing roughly 33.9% of the continuous glucose monitoring revenue market. Their primary rival is Abbott Laboratories, which leads the category with a 52.8% market share through its FreeStyle Libre line, while Medtronic trails at about 10.1%. DexCom’s core edge rests on high sensor accuracy and seamless insulin pump integrations, creating strong brand loyalty among intensive insulin users. However, Abbott’s aggressive pricing and mass-market distribution remain serious ongoing threats to DexCom’s pricing power.

DexCom is shifting from hyper-growth mode into a steady, mature expansion phase. Annual revenue reached $4.03 billion in 2024, an 11% increase over 2023, following a stronger 24% surge to $3.62 billion the year prior. To keep top-line growth in double digits, management is pivoting into the broader metabolic health space by launching Stelo as an over-the-counter option. Targeting the massive non-insulin Type 2 and prediabetes demographics is a necessary strategic play before their core prescription customer base fully saturates.

Key Financials
Market Cap
$30.64B
Revenue
$4.97B
EBITDA
$1.40B
Gross Margin
62.5%
Profit Margin
20.1%
Revenue Growth
13.1%
Total Cash
$1.95B
Total Debt
$1.40B
Free Cash Flow
$1.02B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
32.22
Forward P/E
25.99
Beta
1.48
52-Week High
$92.59
52-Week Low
$54.11
EPS
$2.52
50-Day Avg
$87.53
200-Day Avg
$74.16
Price/Book
11.69
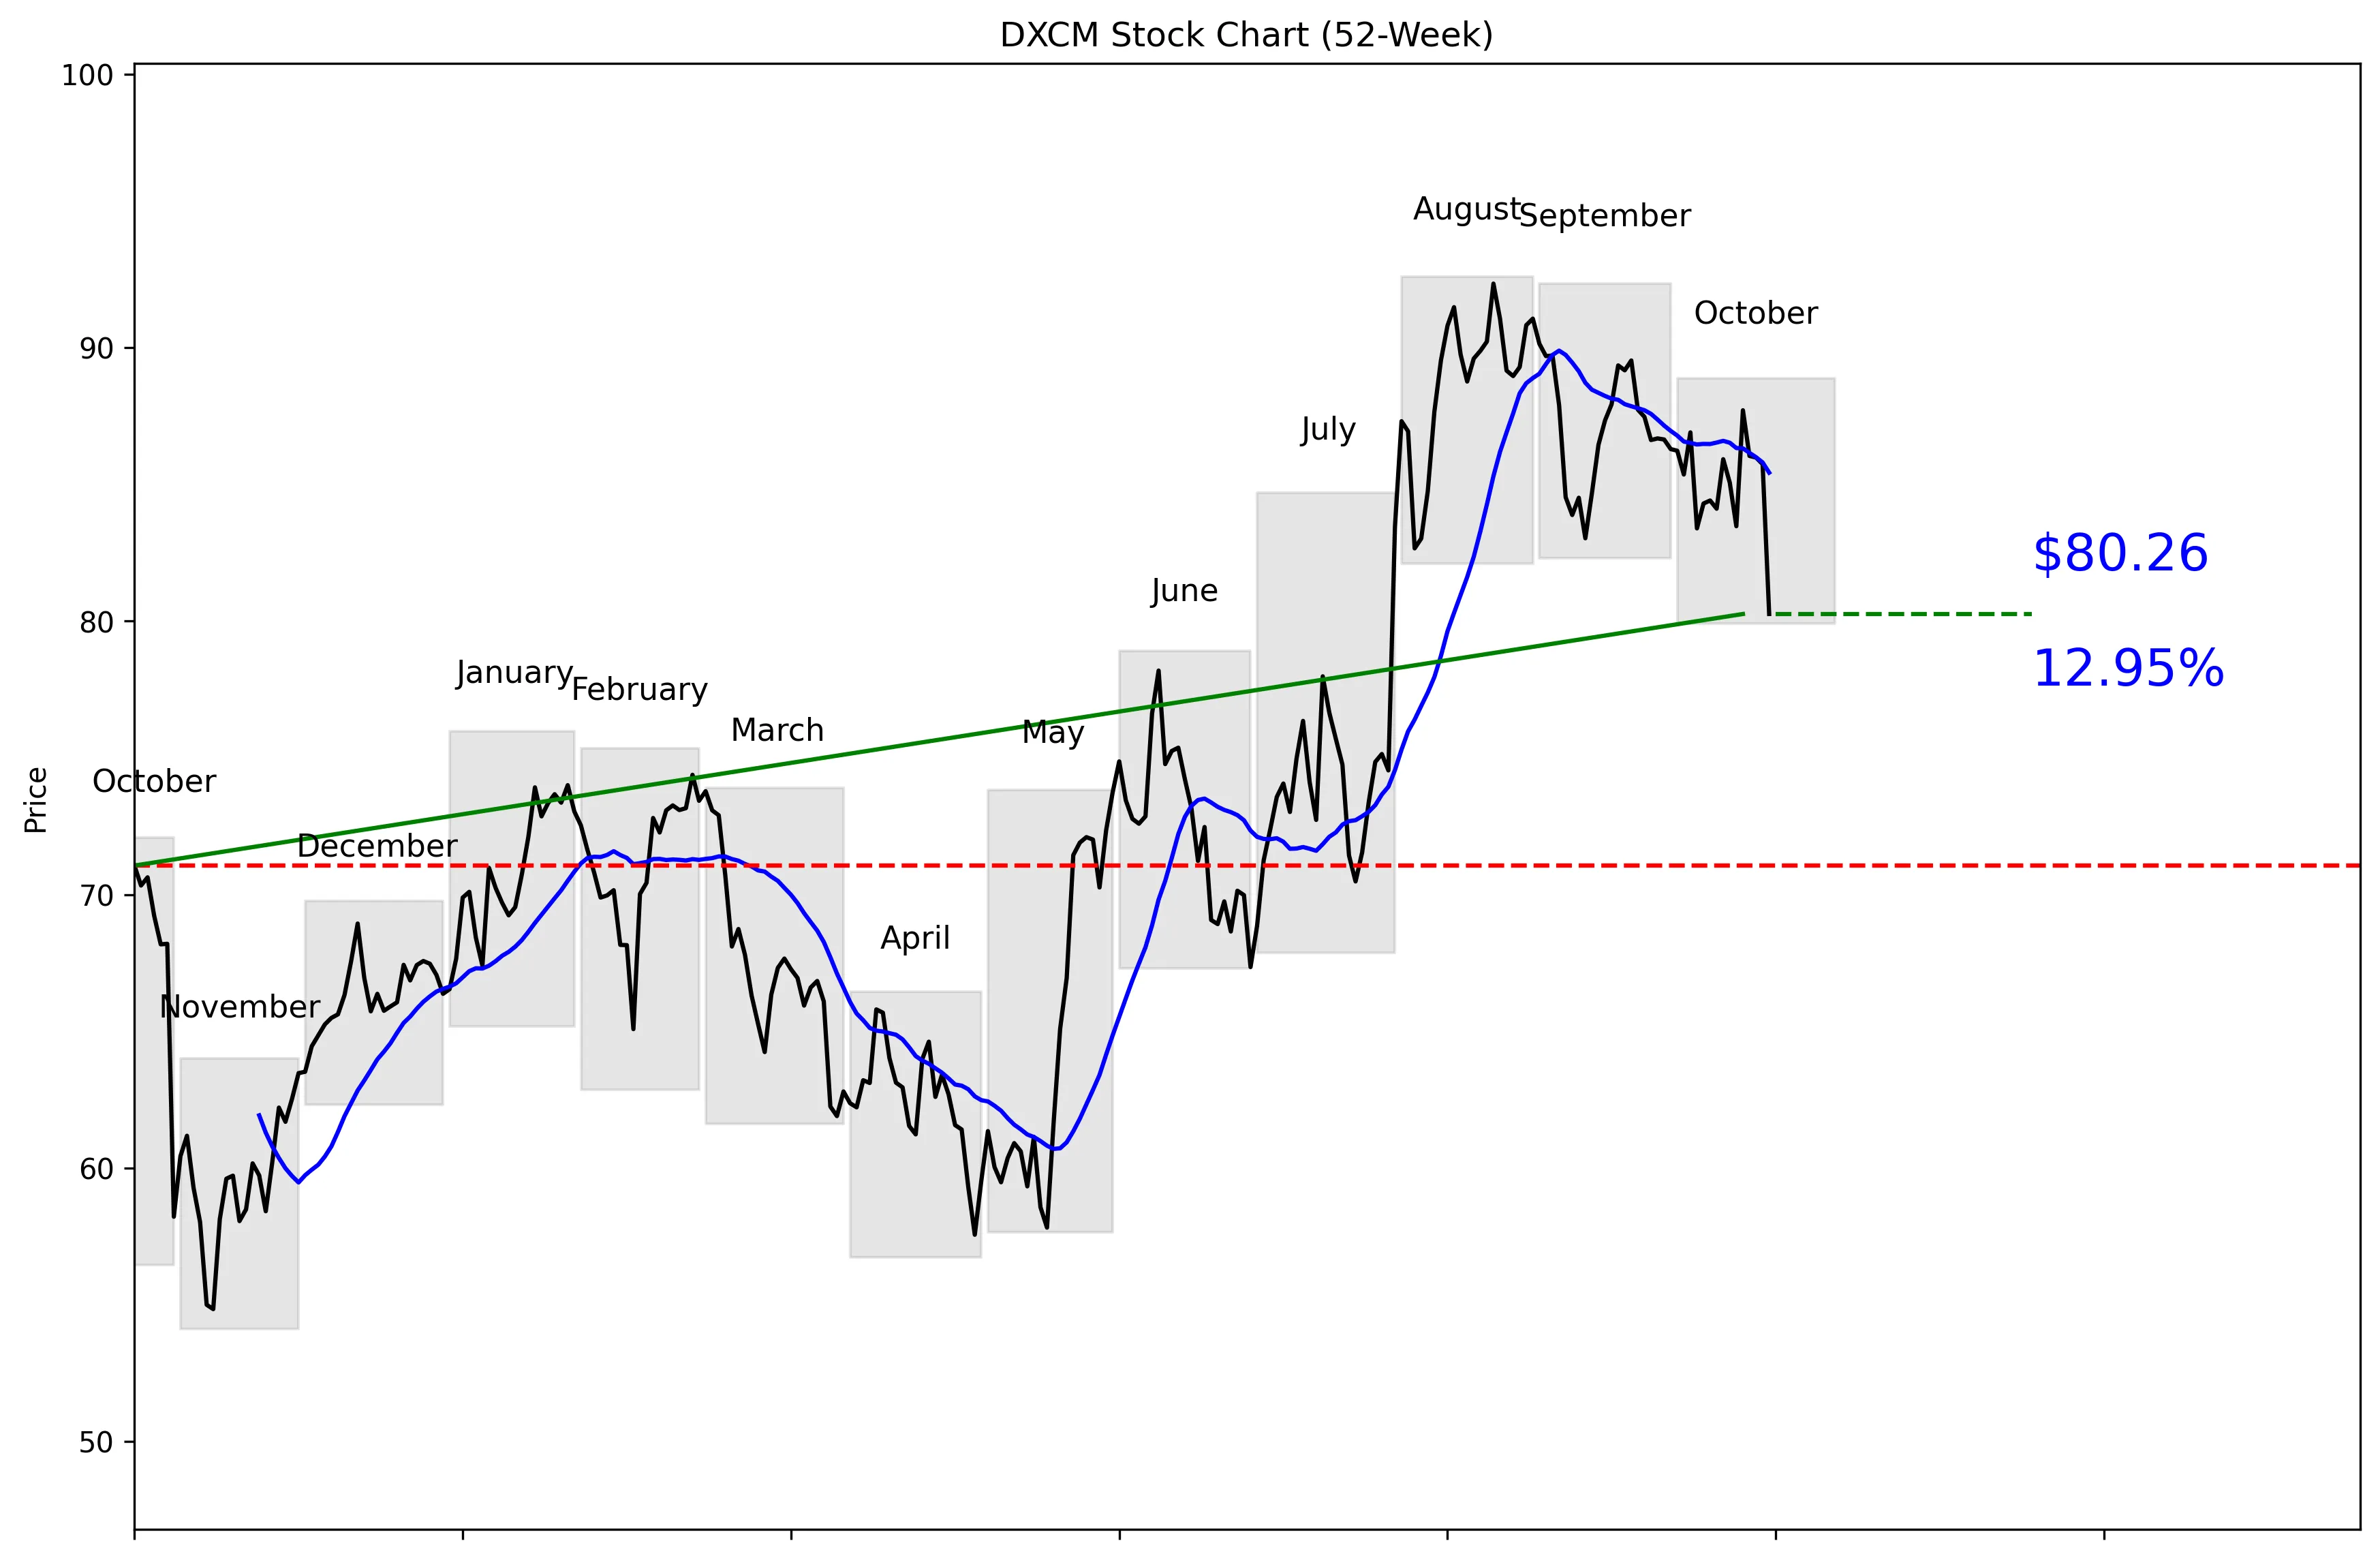
DXCM 52-Week Stock Chart
Technical Analysis
DXCM trades at $81.19, placing it 68% of the way through its $54.11 to $92.59 52-week range. The stock is 13.32% below its 52-week high but remains 48.33% above its low. Price sits 6.05% below the 20-day moving average of $85.43, confirming weak near-term momentum. Shares have declined 3.85% over five trading days and 8.51% over 20 trading days. Near-term support is $80.26, while resistance is $89.53.


Recent News and Developments

Dexcom G7 cuts A1C in non-insulin Type 2 trial

The Dexcom-sponsored CONNECT trial randomized 283 adults with Type 2 diabetes who were not using insulin across 22 U.S. primary-care sites. After 26 weeks, Dexcom G7 users reduced A1C by 0.9 percentage points more than patients receiving routine care. Source: TRESTLEWIRE

Dexcom executive sells 1,700 shares

Executive Vice President Michael Jon Brown sold 1,700 DXCM shares at $85.48 each for $145,316. The transaction came 14 days before Dexcom’s scheduled October 29 third-quarter report; it is worth noting, not overreading. Source: BestStocks

DXCM drops as Abbott raises CGM demand concerns

DXCM fell about 5.8% on October 21, trading near $80.77 versus the previous close of $85.74. The selloff followed Abbott’s third-quarter report, which showed sequential deceleration in continuous-glucose-monitor sales and triggered a negative read-through for Dexcom ahead of its October 29 earnings report. Source: Tickeron


Market Sentiment and Analyst Recommendations

Bull Case
DexCom generated $4.97 billion in revenue, with revenue growing 13.1%. The CONNECT trial gives the company a meaningful growth argument beyond insulin users: Dexcom G7 users reduced A1C by 0.9 percentage points more than routine-care patients after 26 weeks. The trial included 283 adults with Type 2 diabetes who were not using insulin across 22 U.S. primary-care sites. That result supports a broader potential market for continuous glucose monitoring. DexCom also has $1.95 billion in cash against $1.40 billion in debt. Analysts remain firmly bullish, with a strong-buy recommendation from 26 analysts and an average target of $96.46 versus the current $81.19 price.
Bear Case
DXCM is not cheap at 32.22 times earnings. The stock is already 48.33% above its 52-week low, so buyers are not entering at a distressed valuation. Momentum has turned negative, with declines of 3.85% over five trading days and 8.51% over 20 trading days. Abbott’s third-quarter report showed sequential deceleration in continuous-glucose-monitor sales, raising a direct demand concern for DexCom. That read-through helped push DXCM down about 5.8% on October 21, from a previous close of $85.74 to near $80.77. The analyst target range also falls as low as $79.00, below the current $81.19 price, showing that not every analyst sees upside.
What to Watch
DexCom’s October 29 third-quarter report is the next major test. Investors should compare the company’s reported growth with the current 13.1% revenue-growth figure and look for evidence that Abbott’s demand slowdown applies to DexCom. The CONNECT trial is another key catalyst because its 0.9-percentage-point A1C improvement could support adoption among Type 2 patients who do not use insulin. On the chart, $80.26 is the immediate level to defend; a break below it would extend the current negative momentum. A recovery above the 20-day moving average of $85.43 would be the first sign that selling pressure is easing. Clearing the $89.53 near-term resistance would strengthen the bullish case, while failure to hold support would put the $79.00 low-end analyst target into focus.
Analyst Consensus
STRONG BUY

Based on 26 analyst opinions
Low Target
$79.00
Mean Target
$96.46
High Target
$115.00


Earnings and Financial Data

Sector
Healthcare
Industry
Medical Devices
Employees
11,000
Earnings & Dividends
Next Earnings
Oct 29, 2026
EPS (Trailing)
$2.52
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is DXCM a good stock to buy?
DXCM carries a strong-buy recommendation from 26 analysts, with the stock priced at $81.19. The bullish consensus is clear, but the 32.22 P/E and negative short-term momentum make entry price important.
What is DXCM’s analyst price target?
The average analyst target is $96.46, with estimates ranging from $79.00 to $115.00. The takeaway is that the consensus target sits above the current $81.19 price, but the low-end target does not.
Is DXCM stock overvalued?
DXCM trades at a P/E of 32.22 while revenue is growing 13.1%. The takeaway is that investors are paying a premium valuation for continued growth.
What are DXCM’s support and resistance levels?
Near-term support is the 30-day low of $80.26, and near-term resistance is the 30-day high of $89.53. The takeaway is that the current $81.19 price sits close to support.
How far is DXCM from its 52-week high?
DXCM is 13.32% below its $92.59 52-week high and 48.33% above its $54.11 low. The takeaway is that the stock remains well above its yearly low but has not recovered its high.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 22, 2026.