ALTSTATION.IO

Allegion plc (ALLE) Stock Analysis

By Nova Skye | AltStation.io | Updated October 24, 2026

Price
$180.07
Change
+2.01%
Market Cap
$15.31B
Avg Volume
1.2M

Company Overview

Allegion plc is a Dublin, Ireland-based security hardware and access control manufacturer operating in the Industrials sector’s Security & Protection Services group. The company runs two reporting segments, Allegion Americas and Allegion International, selling mechanical locks, exit devices, door closers, and electronic access systems. Its core product lineup spans recognized commercial and residential brands like Schlage, Von Duprin, LCN, and CISA, serving educational facilities, healthcare centers, government buildings, commercial offices, and residential properties. Sales flow through DIY home improvement stores, specialty distributors, wholesalers, and e-commerce channels, supplemented by maintenance repair services and cloud access software.

Allegion holds a market-leading position in North American institutional security hardware, operating as a focused pure-play competitor against larger global rivals like ASSA ABLOY. The company’s primary moat lies in high switching costs and entrenched brand specifications, where architects and facility managers routinely write brands like Von Duprin and LCN directly into commercial building codes. The main operational threat is low-end mechanical lock commoditization and cyclical exposure to new commercial construction activity. However, Allegion insulates itself through recurring aftermarket replacement demand, where property managers prioritize proven reliability over unproven budget alternatives.

The business is growing steadily while executing a strategic shift from legacy mechanical locks toward digital, connected access platforms. Allegion generated $3.77 billion in net revenues for 2024, marking a 3.3% reported increase and 2.1% organic growth over 2023’s $3.65 billion top line. Electronic security products and digital solutions now account for roughly 33% of the company’s total revenue mix. That electronic migration is the central investment thesis, allowing Allegion to capture higher gross margins and attach recurring software-as-a-service workflows to its physical footprint.

Key Financials
Market Cap
$15.31B
Revenue
$4.39B
EBITDA
$1.10B
Gross Margin
45.1%
Profit Margin
15.7%
Revenue Growth
9.6%
Total Cash
$388.10M
Total Debt
$2.03B
Free Cash Flow
$630.29M


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
21.26
Forward P/E
18.30
Beta
N/A
52-Week High
$183.11
52-Week Low
$125.00
EPS
$8.47
50-Day Avg
$156.18
200-Day Avg
$149.90
Price/Book
7.50
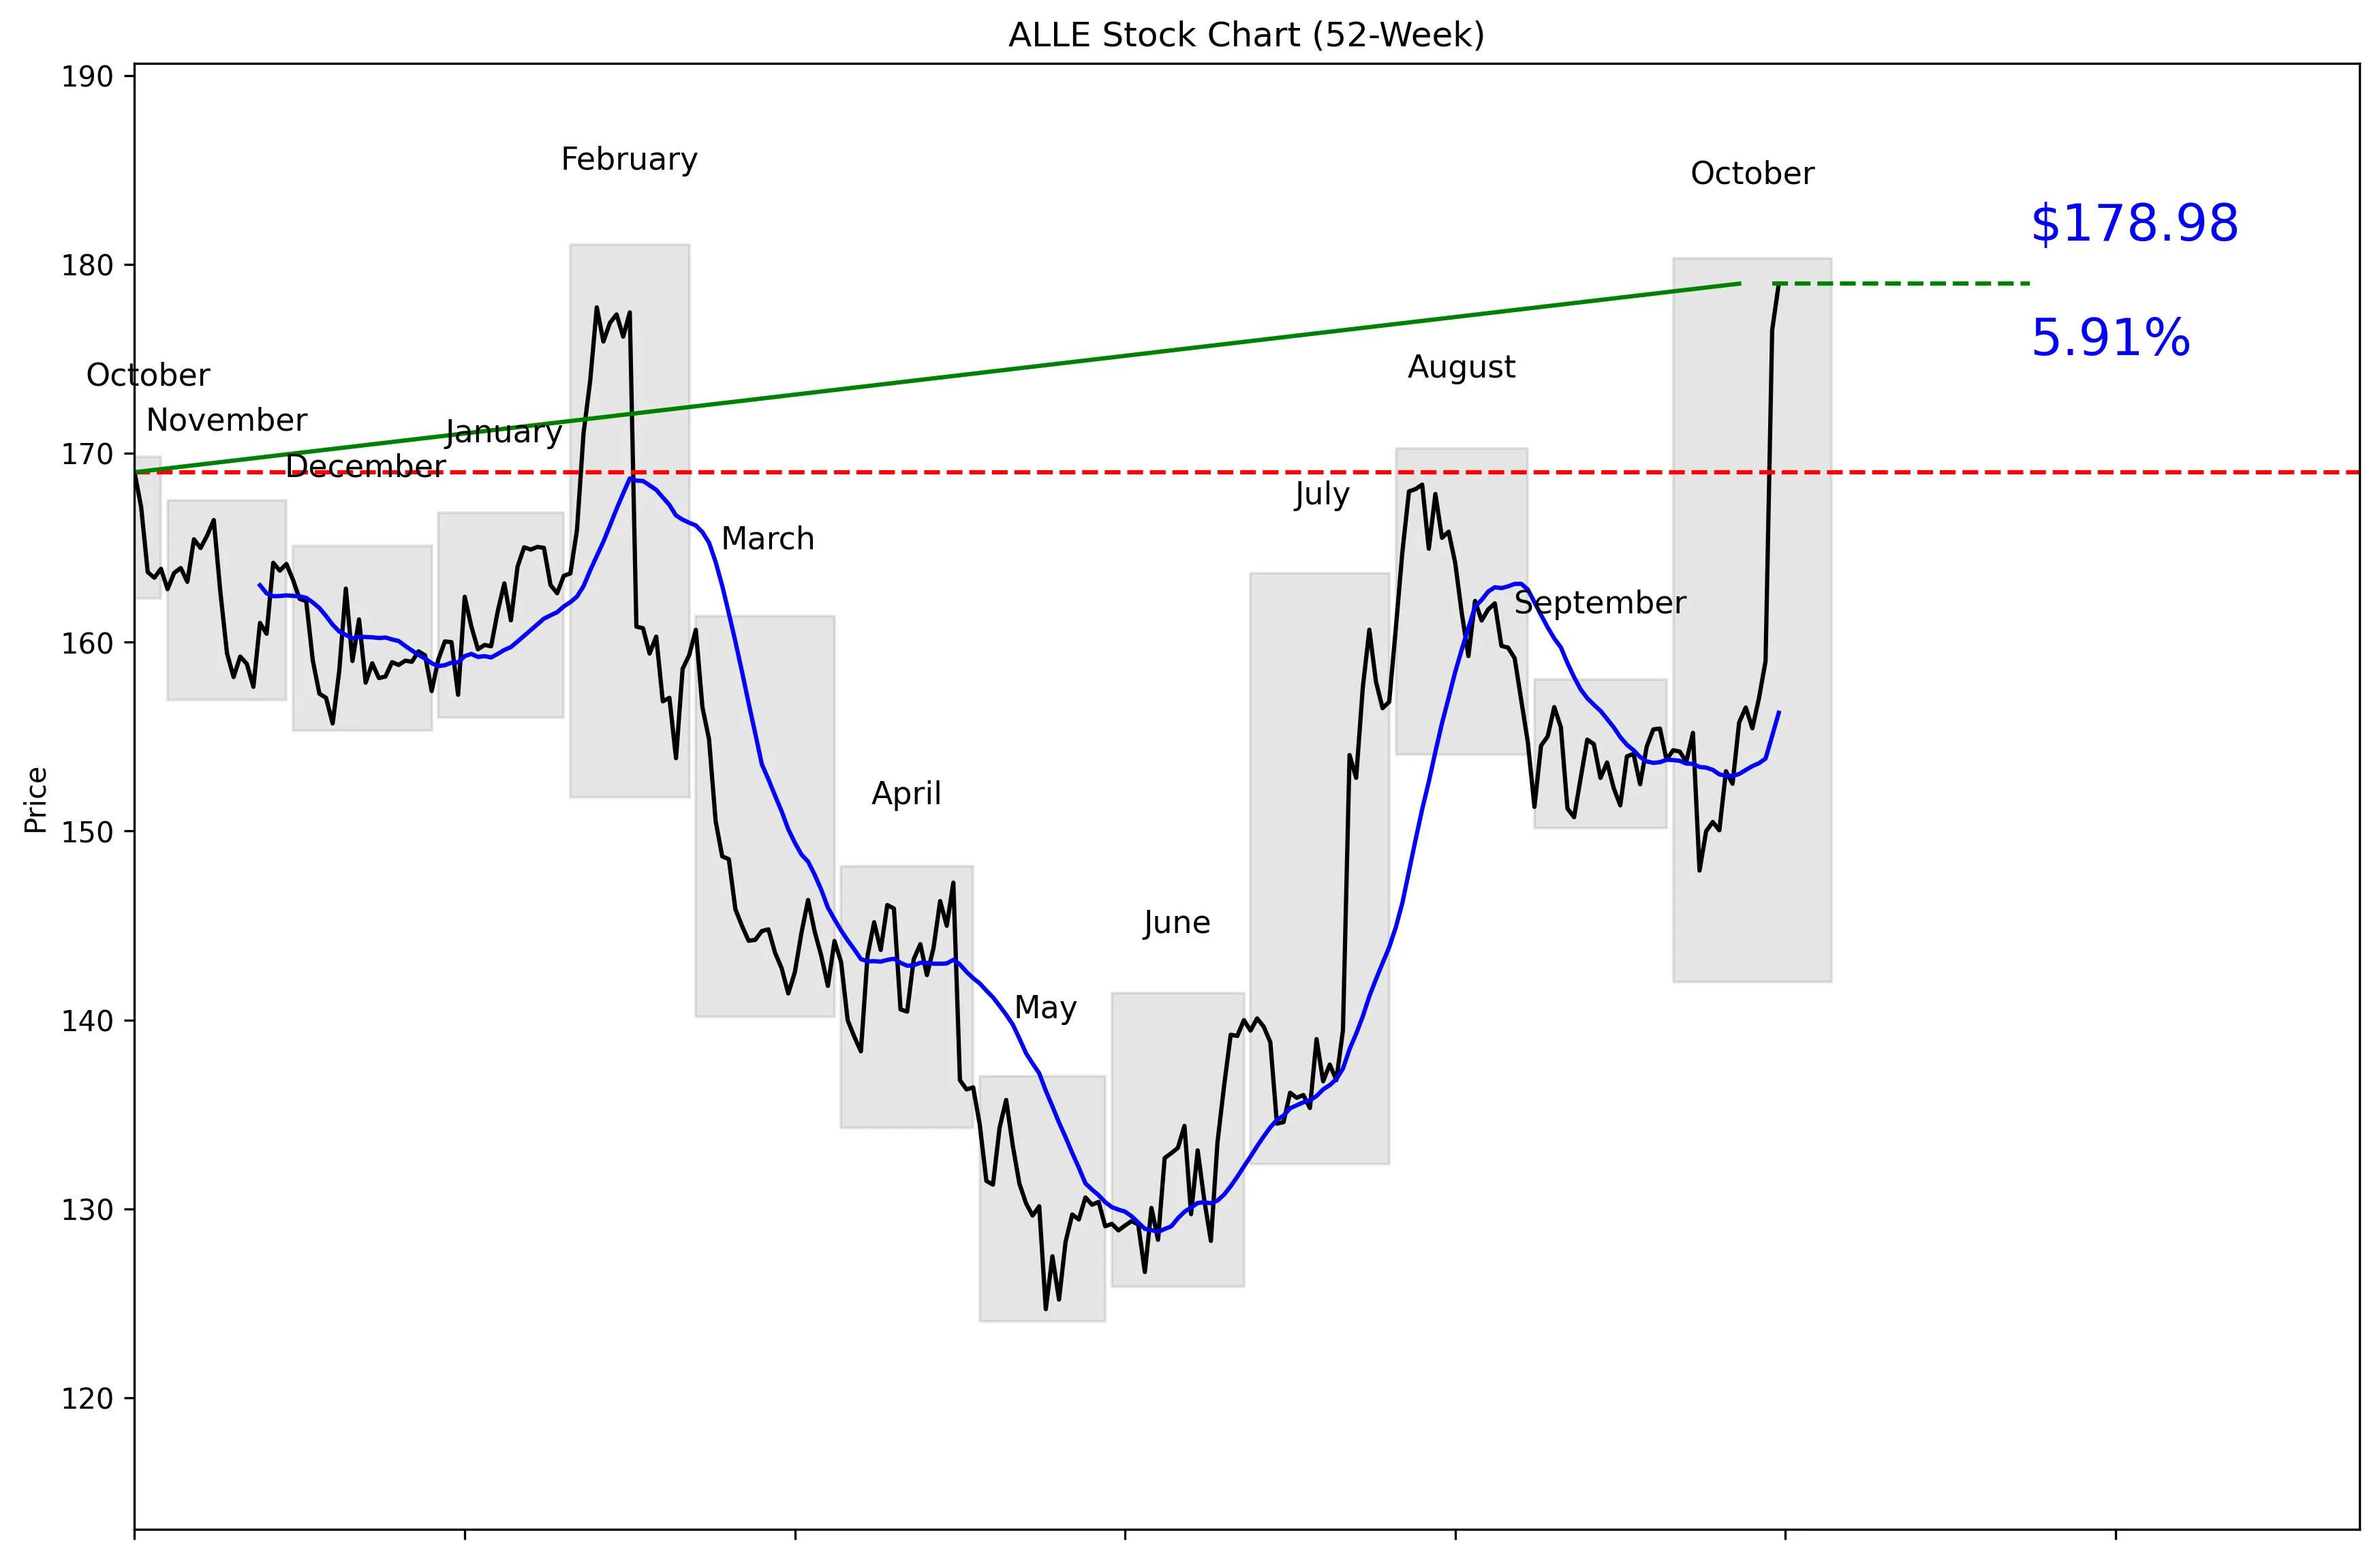
ALLE 52-Week Stock Chart
Technical Analysis
ALLE trades at $180.07, 96% of the way from its $124.05 52-week low to its $181.03 52-week high. The stock is 1.13% below that high and 44.28% above the low. Price is 14.54% above the 20-day moving average of $156.26, confirming a strong upward trend. Momentum is 14.33% over five trading days and 15.87% over 20 trading days. ALLE has moved above the listed 30-day resistance of $178.98, while near-term support sits at $147.91.


Recent News and Developments

Allegion posts strong Q3 and raises 2026 outlook

Third-quarter revenue rose 9.6% to $1.1726 billion, while adjusted EPS increased 13.0% to $2.60. Allegion raised its full-year adjusted EPS forecast to $9.05-$9.10, backed by 9.1% organic growth in the Americas. Source: Allegion

Earnings beat sends ALLE shares sharply higher

Allegion shares jumped 6.9% during the morning session on October 22 after its quarterly report. Adjusted EPS of $2.60 beat the $2.50 Wall Street estimate, while revenue of $1.173 billion topped the $1.137 billion estimate. Source: Yahoo Finance

BofA upgrades Allegion as analysts lift price targets

BofA upgraded Allegion from Neutral to Buy and raised its price target from $164 to $200, citing accelerating organic growth and improving volume trends. JPMorgan lifted its target from $170 to $183 while keeping a Neutral rating, and Evercore ISI raised its target from $180 to $190 while maintaining Outperform. Source: Benzinga


Market Sentiment and Analyst Recommendations

Bull Case
Allegion’s third-quarter revenue increased 9.6% to $1.1726 billion, supported by 9.1% organic growth in the Americas. Adjusted EPS rose 13.0% to $2.60 and beat the $2.50 estimate. Revenue also exceeded the $1.137 billion estimate, giving investors evidence that growth is translating into better earnings. Management raised its full-year adjusted EPS forecast to $9.05-$9.10. BofA upgraded ALLE to Buy and raised its target from $164 to $200, while Evercore ISI increased its target from $180 to $190. The case for buying is straightforward: earnings are beating expectations, guidance is rising, analyst sentiment is improving, and the stock has strong momentum.
Bear Case
ALLE is already trading at $180.07, close to both its $181.03 technical 52-week high and the $182 analyst target. The P/E of 21.26 leaves less room for disappointment if revenue or earnings growth slows. Total debt of $2.03 billion substantially exceeds total cash of $388.10 million. Allegion also borrowed another $40 million through its revolving credit facility to help fund the $88.7 million Overly acquisition. The stock sits 14.54% above its 20-day moving average after gaining 14.33% in five trading days, so expectations are elevated. A move below the $178.98 breakout level could put the $156.26 moving average and $147.91 support level back in focus.
What to Watch
The next quarterly report needs to show whether the 9.6% revenue growth rate and 9.1% Americas organic growth can continue. Investors should track whether adjusted EPS remains consistent with the raised full-year forecast of $9.05-$9.10. The Overly acquisition deserves attention because Allegion paid approximately $88.7 million and borrowed $40 million to help fund it. Watch whether ALLE can hold above the former 30-day resistance level of $178.98 after the October 22 earnings move. A sustained break above the $181.03 technical 52-week high would confirm continued momentum, while a drop toward the $156.26 moving average would show that the recent move is weakening. The next quarterly reporting date was not provided, so investors should monitor Allegion’s investor-relations calendar for the announcement.
Analyst Consensus
BUY

Based on 11 analyst opinions
Low Target
$160.00
Mean Target
$182.00
High Target
$202.00


Earnings and Financial Data

Sector
Industrials
Industry
Security & Protection Services
Employees
13,300
Earnings & Dividends
Next Earnings
Oct 22, 2026
EPS (Trailing)
$8.47
Dividend Yield
125.0%
Payout Ratio
26.9%

Frequently Asked Questions

Is ALLE a good stock to buy?
The analyst recommendation is Buy based on 11 analysts, and revenue growth is 9.6%. The takeaway is that analyst sentiment and business growth are positive, but the stock is already near its 52-week high.
What is ALLE’s price target?
The analyst target is $182.00, with estimates ranging from $160.00 to $202.00. The takeaway is that the central target sits close to the current $180.07 price.
Is ALLE stock overvalued?
ALLE trades at a P/E of 21.26 and sits 96% of the way from its $124.05 technical 52-week low to its $181.03 technical high. The takeaway is that the stock is priced near the top of its recent range.
What are ALLE’s support and resistance levels?
Near-term support is $147.91, and the listed 30-day resistance is $178.98. The takeaway is that the current $180.07 price is above that resistance level.
Does ALLE pay a dividend?
The provided data does not include a dividend amount or yield. The takeaway is that ALLE’s dividend status cannot be determined from this data.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 24, 2026.