ALTSTATION.IO

American Tower Corporation (AMT) Stock Analysis

By Nova Skye | AltStation.io | Updated November 01, 2026

Price
$187.78
Change
+1.02%
Market Cap
$87.09B
Avg Volume
2.8M

Company Overview

American Tower Corporation is a Boston-based specialty real estate investment trust that owns and operates essential physical infrastructure for wireless networks. Founded in Delaware in 1995, the company manages a global portfolio of over 148,000 communications sites alongside an interconnected footprint of U.S. data center facilities. The business model is simple: American Tower owns the physical towers and leases vertical antenna space to mobile carriers, broadcast networks, and municipal agencies. Multiple tenants install gear on a single tower, producing high-margin recurring rental revenue with very low incremental overhead.

American Tower is the clear market leader in global multitenant communications real estate, standing ahead of domestic rivals Crown Castle and SBA Communications. Its competitive edge is global reach and long-term contracts with built-in rent escalators that lock in dependable revenue. The primary risk is carrier consolidation and periodic slowdowns in wireless capital expenditures, which can temporarily dampen new lease activity. Still, mobile operators cannot deliver reliable cellular coverage or 5G capacity without leasing space on existing tower real estate.

The company is currently balancing its core tower leasing business with a strategic push into data center and edge infrastructure. Through its CoreSite platform, American Tower operates interconnected data centers across key U.S. markets to serve growing cloud and enterprise workloads. While traditional domestic tower construction has slowed following the initial 5G buildout wave, expanding data demand keeps utilization solid across its 148,000 sites. By pairing physical towers with data center hubs, the business is positioning itself to handle high-bandwidth, low-latency compute demands rather than relying solely on mobile antenna leases.

Key Financials
Market Cap
$87.09B
Revenue
$11.01B
EBITDA
$7.08B
Gross Margin
73.5%
Profit Margin
30.1%
Revenue Growth
2.5%
Total Cash
$1.87B
Total Debt
$45.29B
Free Cash Flow
$3.02B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
26.45
Forward P/E
26.67
Beta
0.89
52-Week High
$202.50
52-Week Low
$160.06
EPS
$7.10
50-Day Avg
$175.87
200-Day Avg
$177.41
Price/Book
24.79
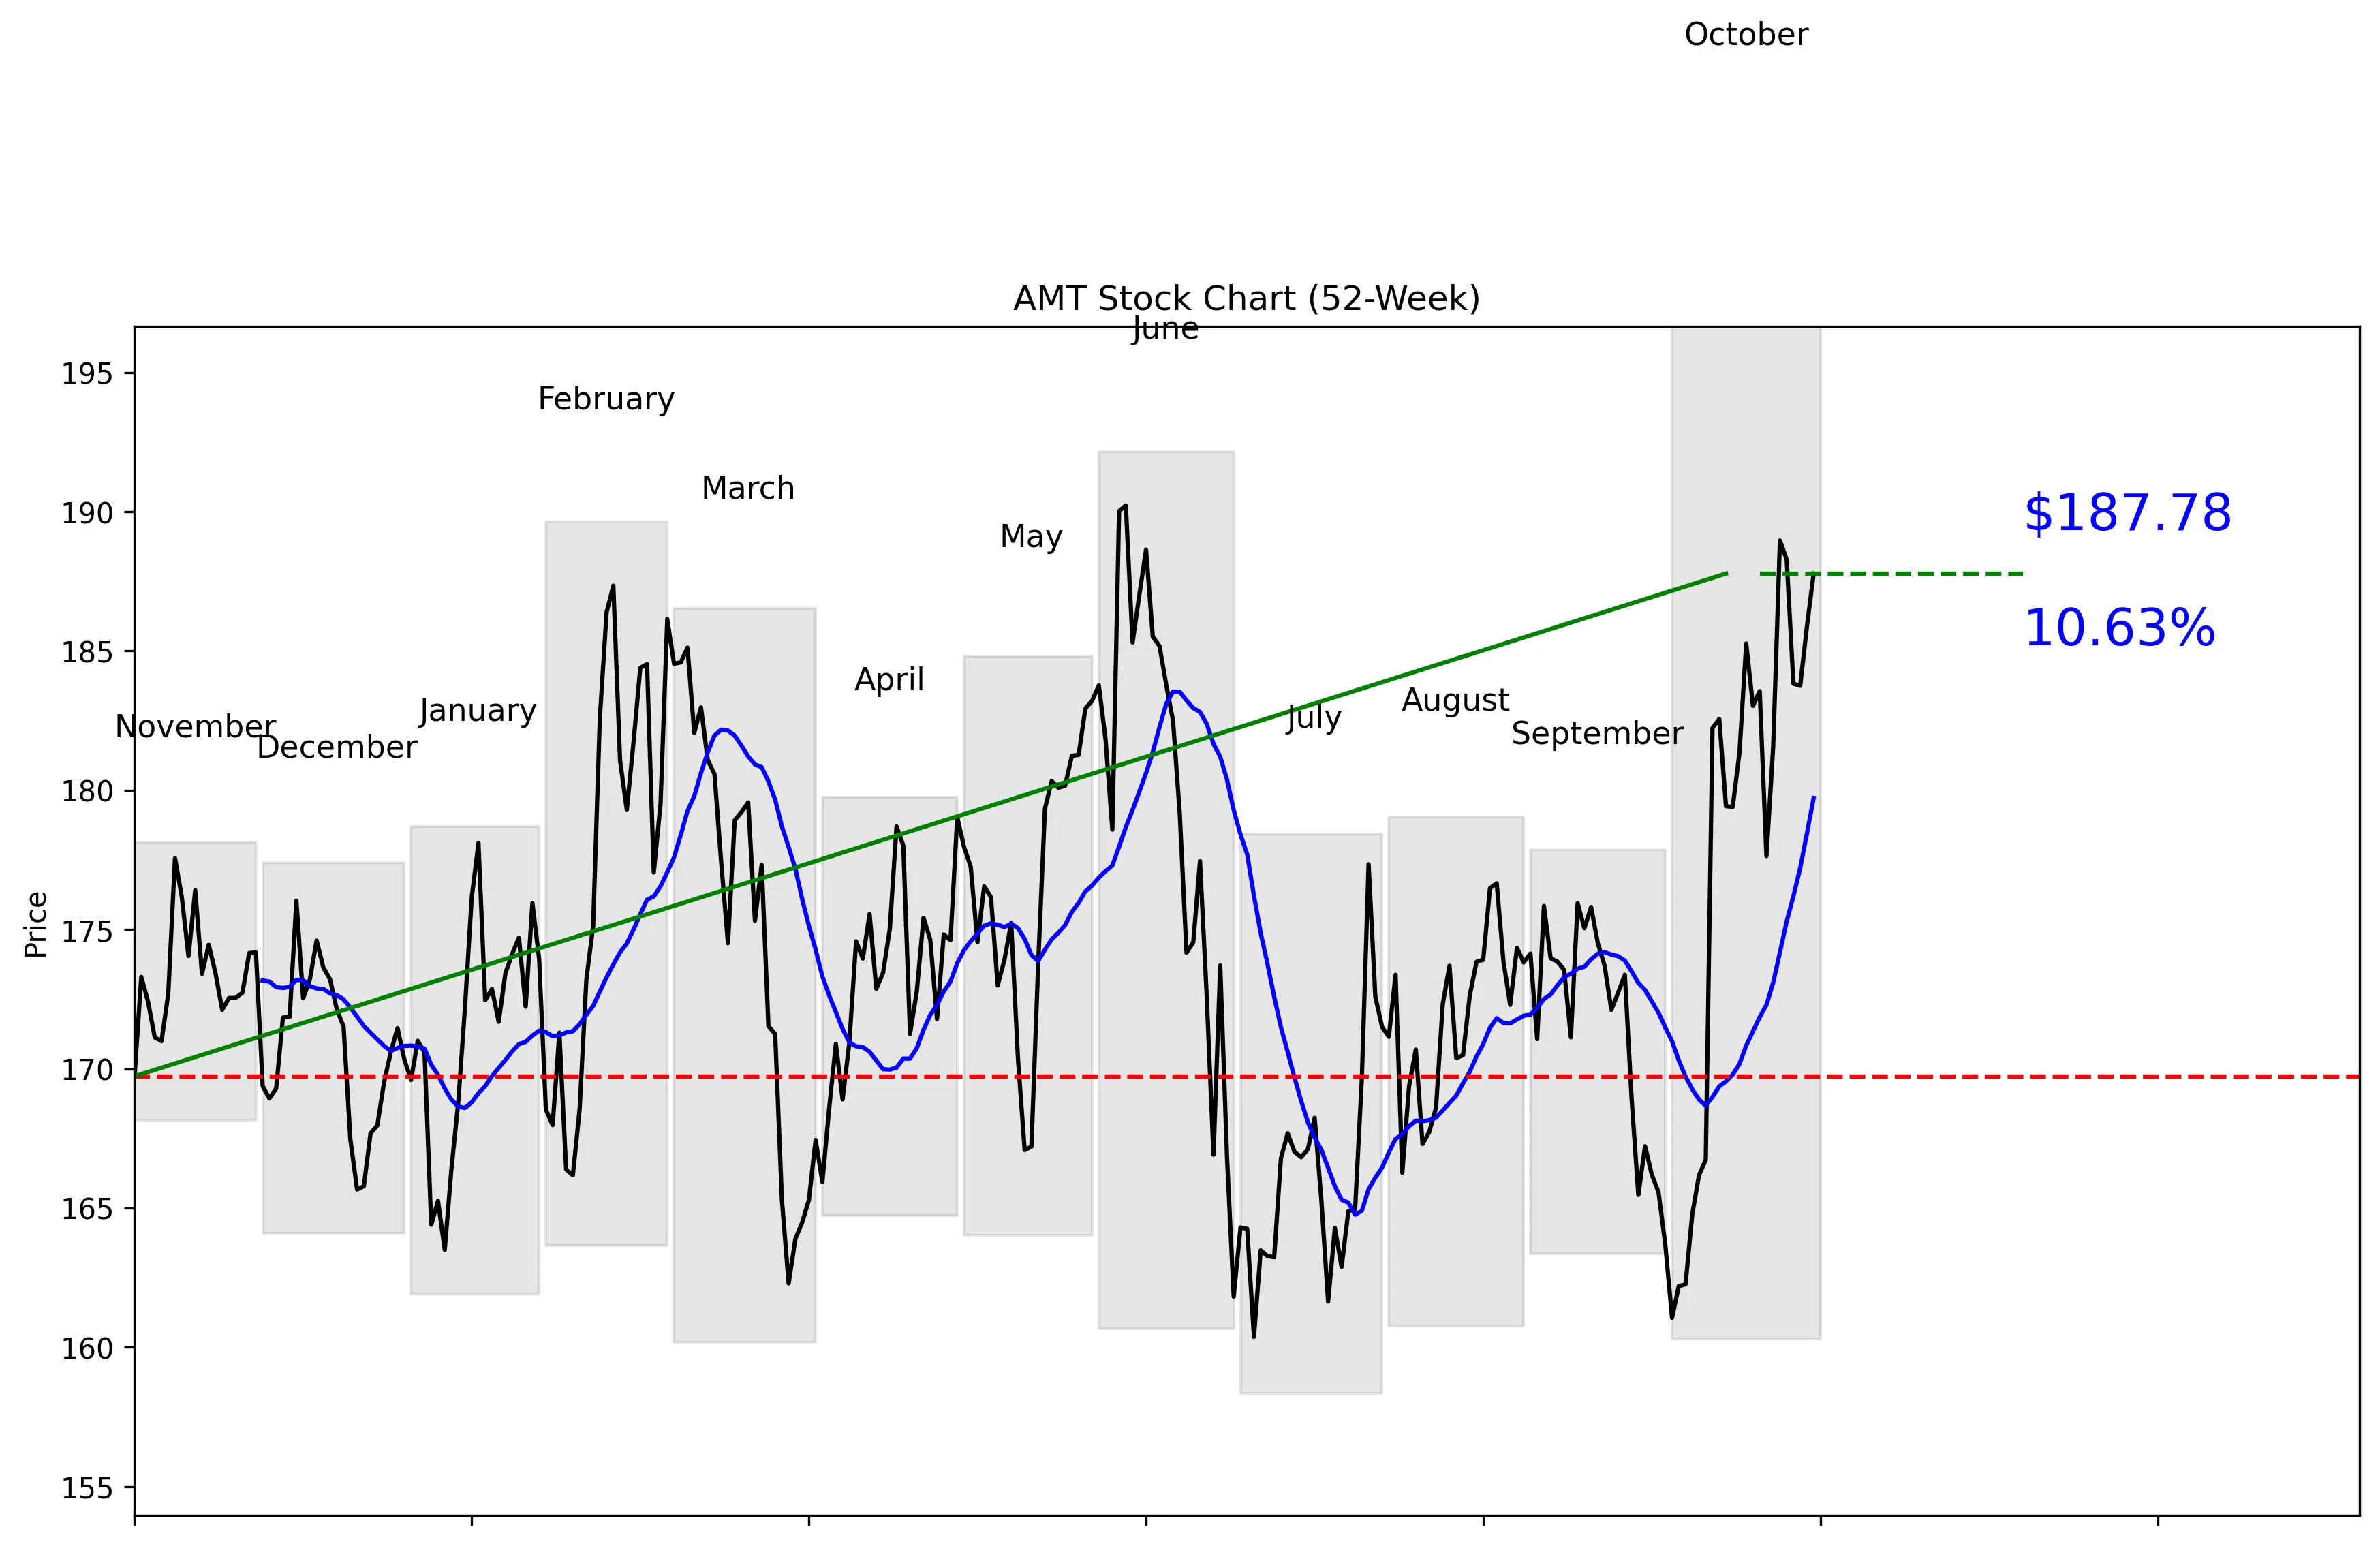
AMT 52-Week Stock Chart
Technical Analysis
AMT trades at $187.78, 67% of the way from its exact 52-week low of $158.35 to its $202.50 high. The stock is 7.27% below that high and 18.59% above the low. Price sits 4.48% above the 20-day moving average of $179.72, supported by a 15.77% gain over the last 20 trading days. Five-day momentum has cooled to -0.63%, showing that the recent rally is losing some force. Near-term support is $161.06, while $188.97 is the immediate resistance level.


Recent News and Developments

American Tower beats Q3 estimates

Q3 revenue rose 2.5% to $2.785 billion, beating the $2.761 billion consensus. AFFO reached $2.87 per share versus $2.68 expected, while net income fell 14.4% to $781 million. Source: Benzinga

AMT raises guidance and expands buybacks

American Tower raised its 2026 AFFO guidance to $11.04-$11.16 per share and increased the midpoint of its property-revenue outlook by $55 million. The board authorized another $2 billion in repurchases on top of roughly $1.1 billion remaining under the existing program. Source: American Tower Corporation

Citi and JPMorgan cut AMT price targets

Citigroup lowered its AMT target from $225 to $220 on October 28, while JPMorgan cut its target from $240 to $230. RBC Capital maintained a $205 target the same day. Source: Benzinga


Market Sentiment and Analyst Recommendations

Bull Case
American Tower beat Q3 expectations, with revenue reaching $2.785 billion versus the $2.761 billion consensus. AFFO was $2.87 per share, comfortably ahead of the $2.68 estimate. Management raised 2026 AFFO guidance to $11.04-$11.16 per share and increased the midpoint of its property-revenue outlook by $55 million. The company also authorized another $2 billion in share repurchases, adding to roughly $1.1 billion remaining under the existing program. Starlink could become a large-scale customer because its proposed U.S. wireless network would still need terrestrial infrastructure, although no agreement exists. At $187.78, AMT trades below the $215.74 analyst target, and 23 analysts currently rate it a buy.
Bear Case
AMT carries $45.29 billion in total debt against just $1.87 billion in cash. That balance-sheet gap leaves little room for operational disappointment. The stock trades at 26.45 times earnings despite revenue growth of only 2.5%. Q3 net income fell 14.4% to $781 million even as revenue increased, which puts pressure on the quality of the growth story. Citigroup cut its target from $225 to $220, JPMorgan reduced its target from $240 to $230, and RBC held at $205. Starlink is not a confirmed catalyst because management announced no agreement or deployment timeline and excluded satellite-carrier demand from its long-term assumptions.
What to Watch
The first test is whether AMT can deliver within its raised 2026 AFFO guidance of $11.04-$11.16 per share. Investors should also track whether the $55 million increase in the property-revenue outlook translates into stronger reported growth. Q3 revenue grew 2.5% to $2.785 billion, so growth above or below 2.5% would materially affect the thesis. Net income needs attention after its 14.4% decline to $781 million. Watch whether AMT begins using the new $2 billion repurchase authorization and the roughly $1.1 billion left under the existing program. Technically, a move above $188.97 would clear near-term resistance, while a drop below the $179.72 moving average would weaken the recent momentum.
Analyst Consensus
BUY

Based on 23 analyst opinions
Low Target
$188.00
Mean Target
$215.74
High Target
$260.00


Earnings and Financial Data

Sector
Real Estate
Industry
REIT – Specialty
Employees
4,866
Earnings & Dividends
Next Earnings
Oct 27, 2026
EPS (Trailing)
$7.10
Dividend Yield
381.0%
Payout Ratio
99.6%

Frequently Asked Questions

Is AMT a good stock to buy?
The stated recommendation is buy based on 23 analysts, while the stock trades at $187.78. The clear takeaway is that analyst sentiment is positive.
What is AMT’s price target?
The analyst target is $215.74, with estimates ranging from $188.00 to $260.00. The takeaway is that the consensus target sits above the current $187.78 price.
What is AMT’s 52-week range?
The key data lists a 52-week range of $160.06 to $202.50, while the technical price series records an exact low of $158.35 and high of $202.50. The takeaway is that AMT currently sits 67% of the way from the technical low to the high.
Is AMT stock overvalued?
AMT has a P/E ratio of 26.45 and revenue growth of 2.5%. The takeaway is that investors are paying a substantial earnings multiple for modest revenue growth.
Does AMT pay a dividend?
The provided key and technical data do not include dividend information. The takeaway is that no dividend conclusion can be made from this dataset.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated November 01, 2026.