
Amphenol Corporation (APH) Stock Analysis
By Nova Skye | AltStation.io | Updated October 08, 2026
Company Overview
Amphenol Corporation (APH) makes the physical components that link electronic systems together, specializing in electrical, electronic, and fiber optic connectors, sensor systems, and specialized cabling. Headquartered in Wallingford, Connecticut, the company operates in the Technology sector within the Electronic Components industry. It runs three primary segments: Communications Solutions, Harsh Environment Solutions, and Interconnect and Sensor Systems. Amphenol sells directly and through distributors to manufacturers and service providers across commercial aerospace, defense, automotive, IT and data communications, and mobile devices.
Amphenol is the dominant challenger in a top-heavy industry where the ten largest manufacturers control over 50% of global connector sales. The company holds the number two spot worldwide and is aggressively closing the gap with market leader TE Connectivity, which holds roughly 14.8% share, while maintaining a clear lead over third-place Molex. Amphenol’s edge comes from its dominant footprint in high-speed data interconnects and harsh-environment systems. Its primary competitive risk is exposure to cyclical consumer hardware, but steady demand in defense and aerospace provides a durable floor.
Amphenol is expanding rapidly, capitalizing on heavy spending in artificial intelligence data infrastructure and defense modernization. The company posted an 18.7% sales increase in 2024, easily outpacing TE Connectivity’s 1.1% growth over the same period. Management continues to compound this momentum with aggressive dealmaking, completing the acquisition of Carlisle Interconnect Technologies in 2024 and CommScope’s connector business in 2025. This targeted acquisition strategy positions Amphenol to capture outsized market share as high-speed computing and ruggedized electronics continue to scale.
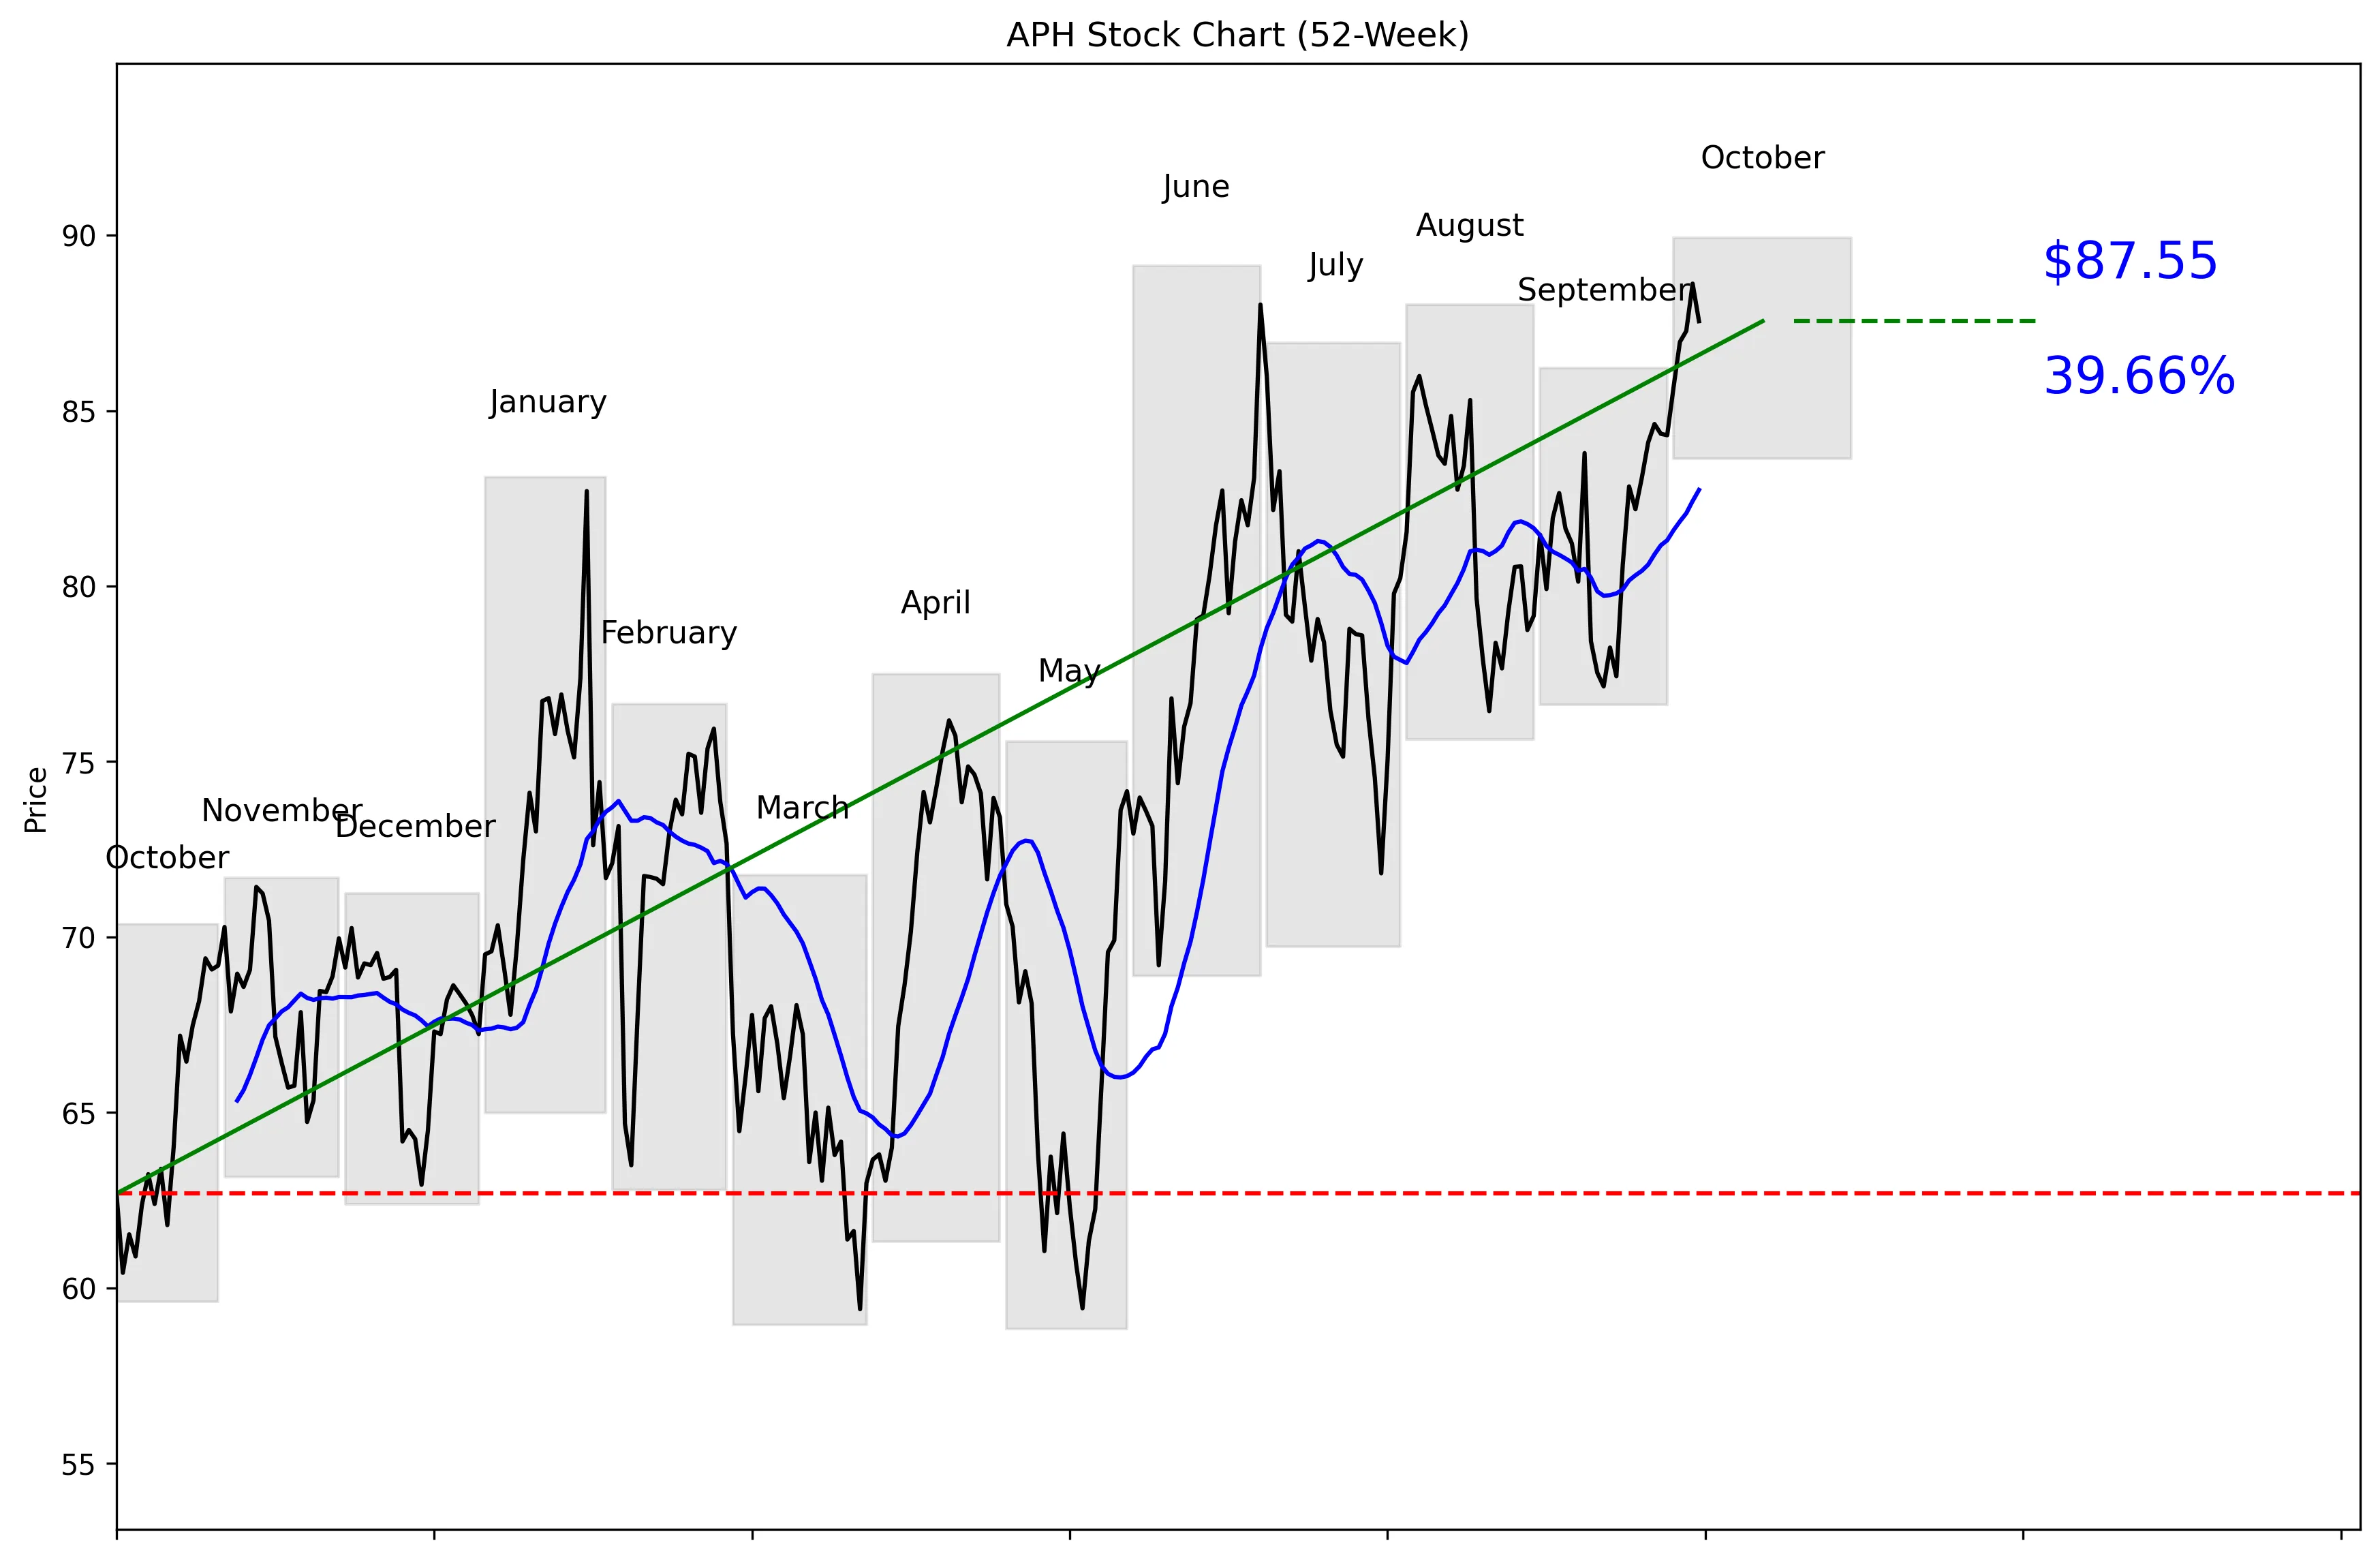
52-Week Price Performance Analysis
Recent News and Developments
UBS analyst Joseph Spak maintained a Buy rating on October 7 and raised the price target from $99 to $105, a 6.1% increase. The call kept UBS firmly bullish without changing its rating. Source: Stock Analysis
Goldman Sachs analyst Mark Delaney reiterated a Buy rating on October 6 and raised the price target from $102 to $116, a 13.7% increase. The $116 target was the highest listed among the latest analyst forecasts. Source: Stock Analysis
Bernstein analyst Varun Govindaraj maintained a Buy rating and $99 price target on October 7. This was a reiteration, not an upgrade or downgrade. Source: Stock Analysis
Market Sentiment and Analyst Recommendations
Earnings and Financial Data
Frequently Asked Questions
Related Stock Reports