ALTSTATION.IO

Axon Enterprise, Inc. (AXON) Stock Analysis

By Nova Skye | AltStation.io | Updated October 19, 2026

Price
$397.85
Change
-4.64%
Market Cap
$32.32B
Avg Volume
951.2K

Company Overview

Axon Enterprise (AXON) is an Aerospace and Defense supplier in the Industrials sector, headquartered in Scottsdale, Arizona. The company builds public safety hardware like TASER devices, body cameras, in-car video, and drone tech, then pairs them with cloud software to store and analyze evidence. Its software lineup, including Axon Evidence and Draft One, manages digital case files and automates police reporting. Axon sells these systems directly and through partners to municipal police departments, federal agencies, international governments, and commercial clients.

Axon is the undisputed market leader in U.S. law enforcement technology and digital evidence management. Its core advantage is a sticky ecosystem: once an agency integrates its body cameras and TASERs into Axon Evidence, replacing that software backbone is expensive and operationally painful. Motorola Solutions remains its primary rival by bundling video tools with emergency radio networks, while smaller players like Panasonic contest select niche contracts. Axon holds the upper hand domestically because its combined hardware and software flywheel creates high switching costs competitors struggle to break.

The company is growing rapidly as it shifts from a traditional hardware seller to a high-margin software business. Revenue grew 33% in 2024 to $2.1 billion and jumped another 33.5% in 2025 to reach $2.78 billion. Annual recurring revenue hit $1.3 billion in 2025 and climbed to $1.64 billion by mid-2026, supported by a 126% net revenue retention rate that proves existing clients keep spending more. Strategic investments in AI-driven incident reporting with Draft One and counter-drone capabilities show Axon is successfully locking in long-term public safety budgets.

Key Financials
Market Cap
$32.32B
Revenue
$3.22B
EBITDA
$165.11M
Gross Margin
59.5%
Profit Margin
6.2%
Revenue Growth
35.3%
Total Cash
$692.53M
Total Debt
$1.85B
Free Cash Flow
$222.16M


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
165.08
Forward P/E
37.73
Beta
1.44
52-Week High
$764.02
52-Week Low
$339.01
EPS
$2.41
50-Day Avg
$505.34
200-Day Avg
$489.57
Price/Book
8.80
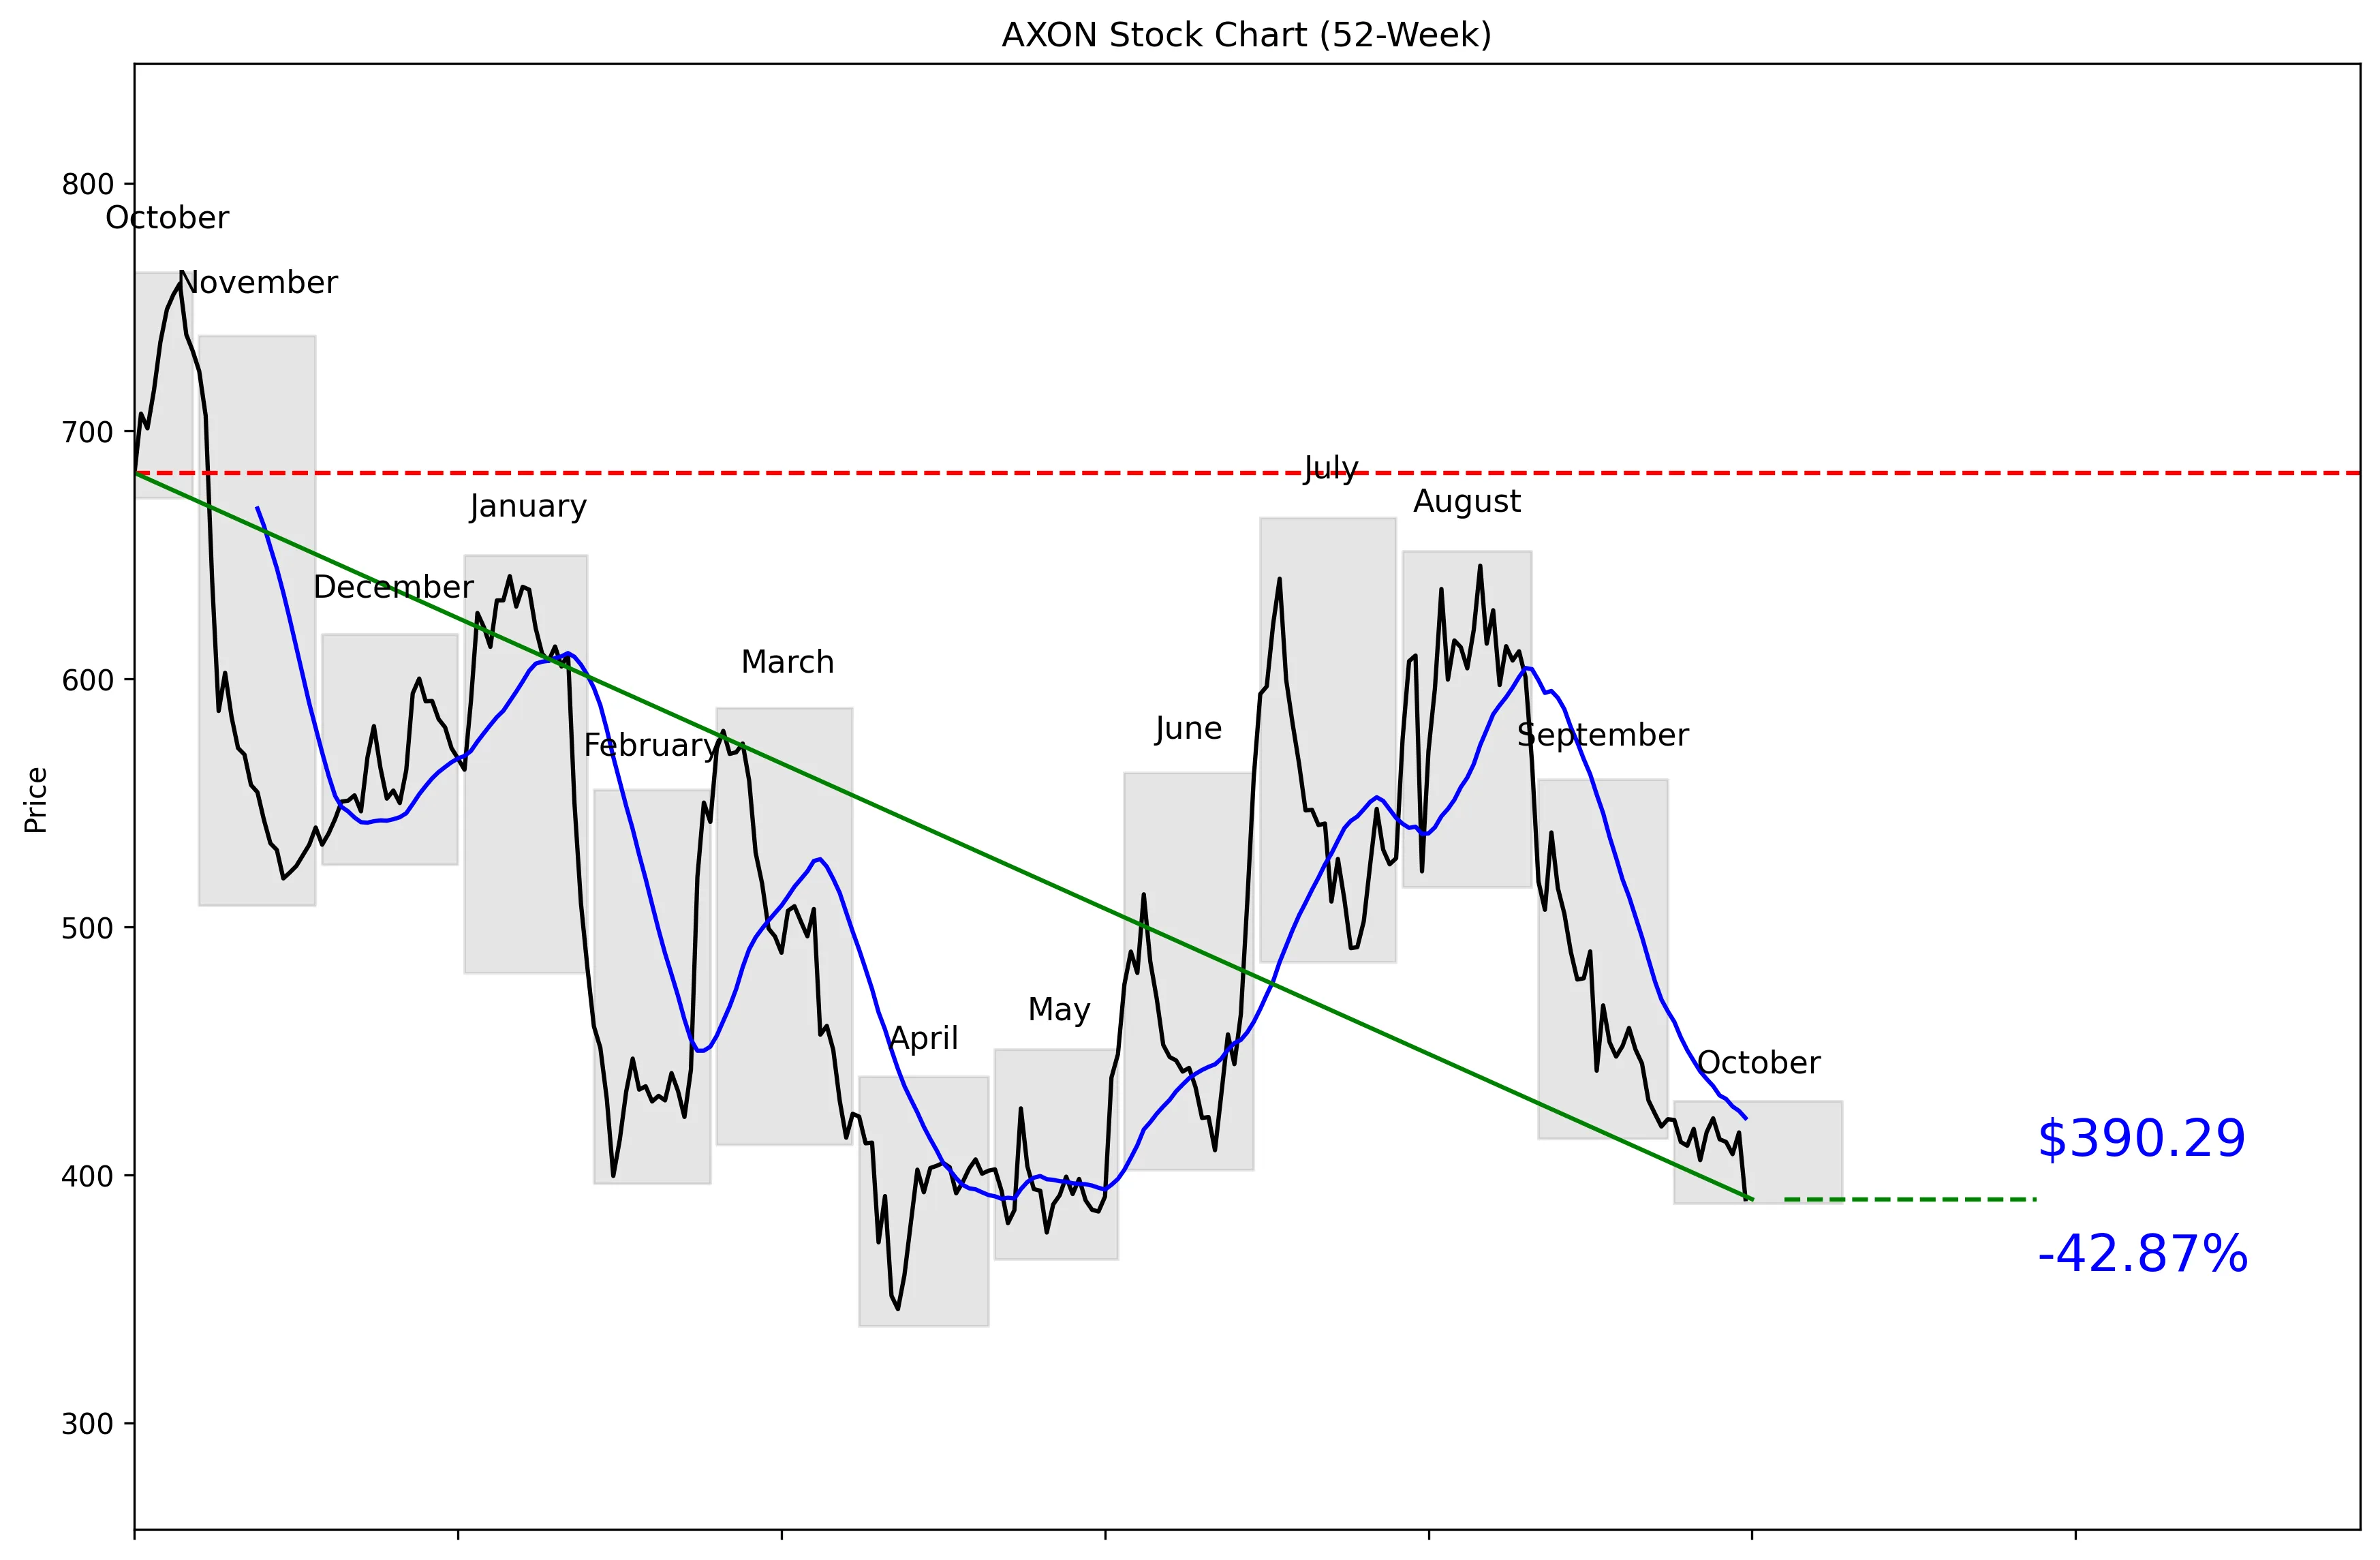
AXON 52-Week Stock Chart
Technical Analysis
AXON trades at $397.85, just 12% of the way from its 52-week low of $339.01 to its 52-week high of $764.02. The stock is 48.92% below that high and 15.13% above the low. Price sits 7.73% below its 20-day moving average of $422.99, confirming a weak short-term trend. Momentum is negative, with declines of 7.71% over five trading days and 12.84% over 20 trading days. Near-term support is $390.29, while resistance is $515.67.


Recent News and Developments

Zacks upgrades Axon to Strong Buy

Zacks upgraded Axon to Rank #1, Strong Buy, on October 12 after analysts raised earnings estimates. Its 2026 consensus estimate increased 30.3% over three months to $7.88 per share. Source: Zacks

UBS cuts Axon price target to $470

UBS maintained its Hold rating on October 13 but cut its price target from $600 to $470. The reduced target still represented 20.42% upside based on the price reported by StockAnalysis. Source: StockAnalysis

Axon reports major federal contract wins

Axon said federal agencies added more than 22,000 body-camera and digital-evidence licenses, while Veterans Affairs added more than 1,600 TASER 10 devices. The Department of Homeland Security also selected Axon’s Dedrone platform for airspace monitoring, drone identification, and threat mitigation. Source: Axon Enterprise


Market Sentiment and Analyst Recommendations

Bull Case
Revenue is growing 35.3%, which is the strongest reason to own AXON despite the valuation. Federal adoption is expanding, with agencies adding more than 22,000 body-camera and digital-evidence licenses and Veterans Affairs adding more than 1,600 TASER 10 devices. The Department of Homeland Security also selected Axon’s Dedrone platform for airspace monitoring, drone identification, and threat mitigation. Zacks upgraded AXON to Strong Buy on October 12 after its 2026 consensus earnings estimate increased 30.3% over three months to $7.88 per share. The broader analyst recommendation is buy, based on 19 analysts, with an average target of $690.68. With the stock at $397.85 and 48.92% below its 52-week high, the bull case is straightforward: rapid growth and stronger earnings expectations could support a major recovery if execution stays strong.
Bear Case
A P/E ratio of 165.08 leaves almost no room for operational disappointment. AXON has $692.53 million in cash against $1.85 billion in debt, so debt exceeds cash by a wide margin. The stock’s trend is also poor, with price 7.73% below its 20-day moving average and 20-day momentum at negative 12.84%. On October 16, AXON dropped 6.45% while the Nasdaq Composite fell 2.1%, showing that investors are punishing the stock more aggressively than the broader market. UBS cut its target from $600 to $470 on October 13 and kept a Hold rating, while Raymond James reduced its target from $800 to $675 on October 15. Revenue growth of 35.3% is impressive, but at 165.08 times earnings, impressive growth is already required rather than optional.
What to Watch
The first technical test is whether AXON can hold the $390.29 near-term support level. A break below that level would put the 52-week low of $339.01 back into focus, while a recovery above the $422.99 20-day moving average would improve the short-term picture. The next major upside threshold is the 30-day high of $515.67. Investors should track whether revenue growth remains near the current 35.3% rate because that growth is carrying a P/E ratio of 165.08. The 2026 consensus earnings estimate of $7.88 per share also matters after its 30.3% increase over three months; falling estimates would undermine the October 12 Strong Buy upgrade. Finally, watch whether the more than 22,000 new body-camera and digital-evidence licenses, more than 1,600 TASER 10 devices, and the Department of Homeland Security’s Dedrone selection produce enough growth to justify the valuation.
Analyst Consensus
BUY

Based on 19 analyst opinions
Low Target
$440.00
Mean Target
$690.68
High Target
$830.00


Earnings and Financial Data

Sector
Industrials
Industry
Aerospace & Defense
Employees
5,100
Earnings & Dividends
Next Earnings
Nov 03, 2026
EPS (Trailing)
$2.41
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is AXON a good stock to buy?
The consensus recommendation is buy based on 19 analysts, and revenue is growing 35.3%. The takeaway is that analysts favor AXON, but its 165.08 P/E makes it a high-expectation investment.
What is AXON’s price target?
The average analyst target is $690.68, with estimates ranging from $440.00 to $830.00. The takeaway is that every target in the stated range is above the current $397.85 price.
Is AXON stock overvalued?
AXON trades at a P/E ratio of 165.08 while revenue is growing 35.3%. The takeaway is that the valuation is demanding even with strong growth.
What are AXON’s support and resistance levels?
Near-term support is the 30-day low of $390.29, and near-term resistance is the 30-day high of $515.67. The takeaway is that those are the key technical levels surrounding the current $397.85 price.
How far is AXON below its 52-week high?
AXON is 48.92% below its 52-week high of $764.02 and 15.13% above its 52-week low of $339.01. The takeaway is that the stock remains near the bottom of its annual range.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 19, 2026.