ALTSTATION.IO

Coinbase Global, Inc. (COIN) Stock Analysis

By Nova Skye | AltStation.io | Updated September 11, 2026

Price
$172.84
Change
-1.08%
Market Cap
$45.60B
Avg Volume
8.4M

Company Overview

Founded in 2012 and based in New York, Coinbase Global operates in the financial services sector under financial data and stock exchanges. The company runs an international platform for crypto assets, selling access and tools to retail consumers, institutional investors, and onchain developers. Everyday users treat Coinbase as their primary crypto account and brokerage, institutions rely on its deep-liquidity trading pool, and developers use its suite of products to build decentralized applications. They generate revenue through transaction fees on trades alongside subscription and services products.

Coinbase is the clear market leader among regulated US crypto exchanges, holding a significant trust moat over offshore rivals like Binance and broad fintech platforms like Robinhood. That compliance reputation lets them charge retail traders premium fees, which generate nearly 49% of company revenue even though institutions drive roughly 84% of total trading volume. The biggest risk here is long-term fee compression as lower-cost competition tests those retail take rates. However, Coinbase protects its turf by serving as the primary custodian for the vast majority of US spot Bitcoin ETFs.

Right now, the company is growing rapidly after doubling its top line, with revenue climbing over 100% from roughly $3.1 billion in 2023 to more than $6.3 billion in 2024. A major strategic shift is their successful revenue diversification, where subscriptions and services like stablecoin interest and staking now account for approximately 45% of total sales. Coinbase is no longer just a high-beta bet on retail trading volume; it is becoming the foundational infrastructure layer for the entire digital asset economy.

Key Financials
Market Cap
$45.60B
Revenue
$6.04B
EBITDA
$699.55M
Gross Margin
85.8%
Profit Margin
-16.3%
Revenue Growth
-17.3%
Total Cash
$8.79B
Total Debt
$6.67B
Free Cash Flow
$2.67B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
N/A
Forward P/E
63.13
Beta
3.39
52-Week High
$402.16
52-Week Low
$139.11
EPS
$-3.86
50-Day Avg
$164.21
200-Day Avg
$191.93
Price/Book
3.49
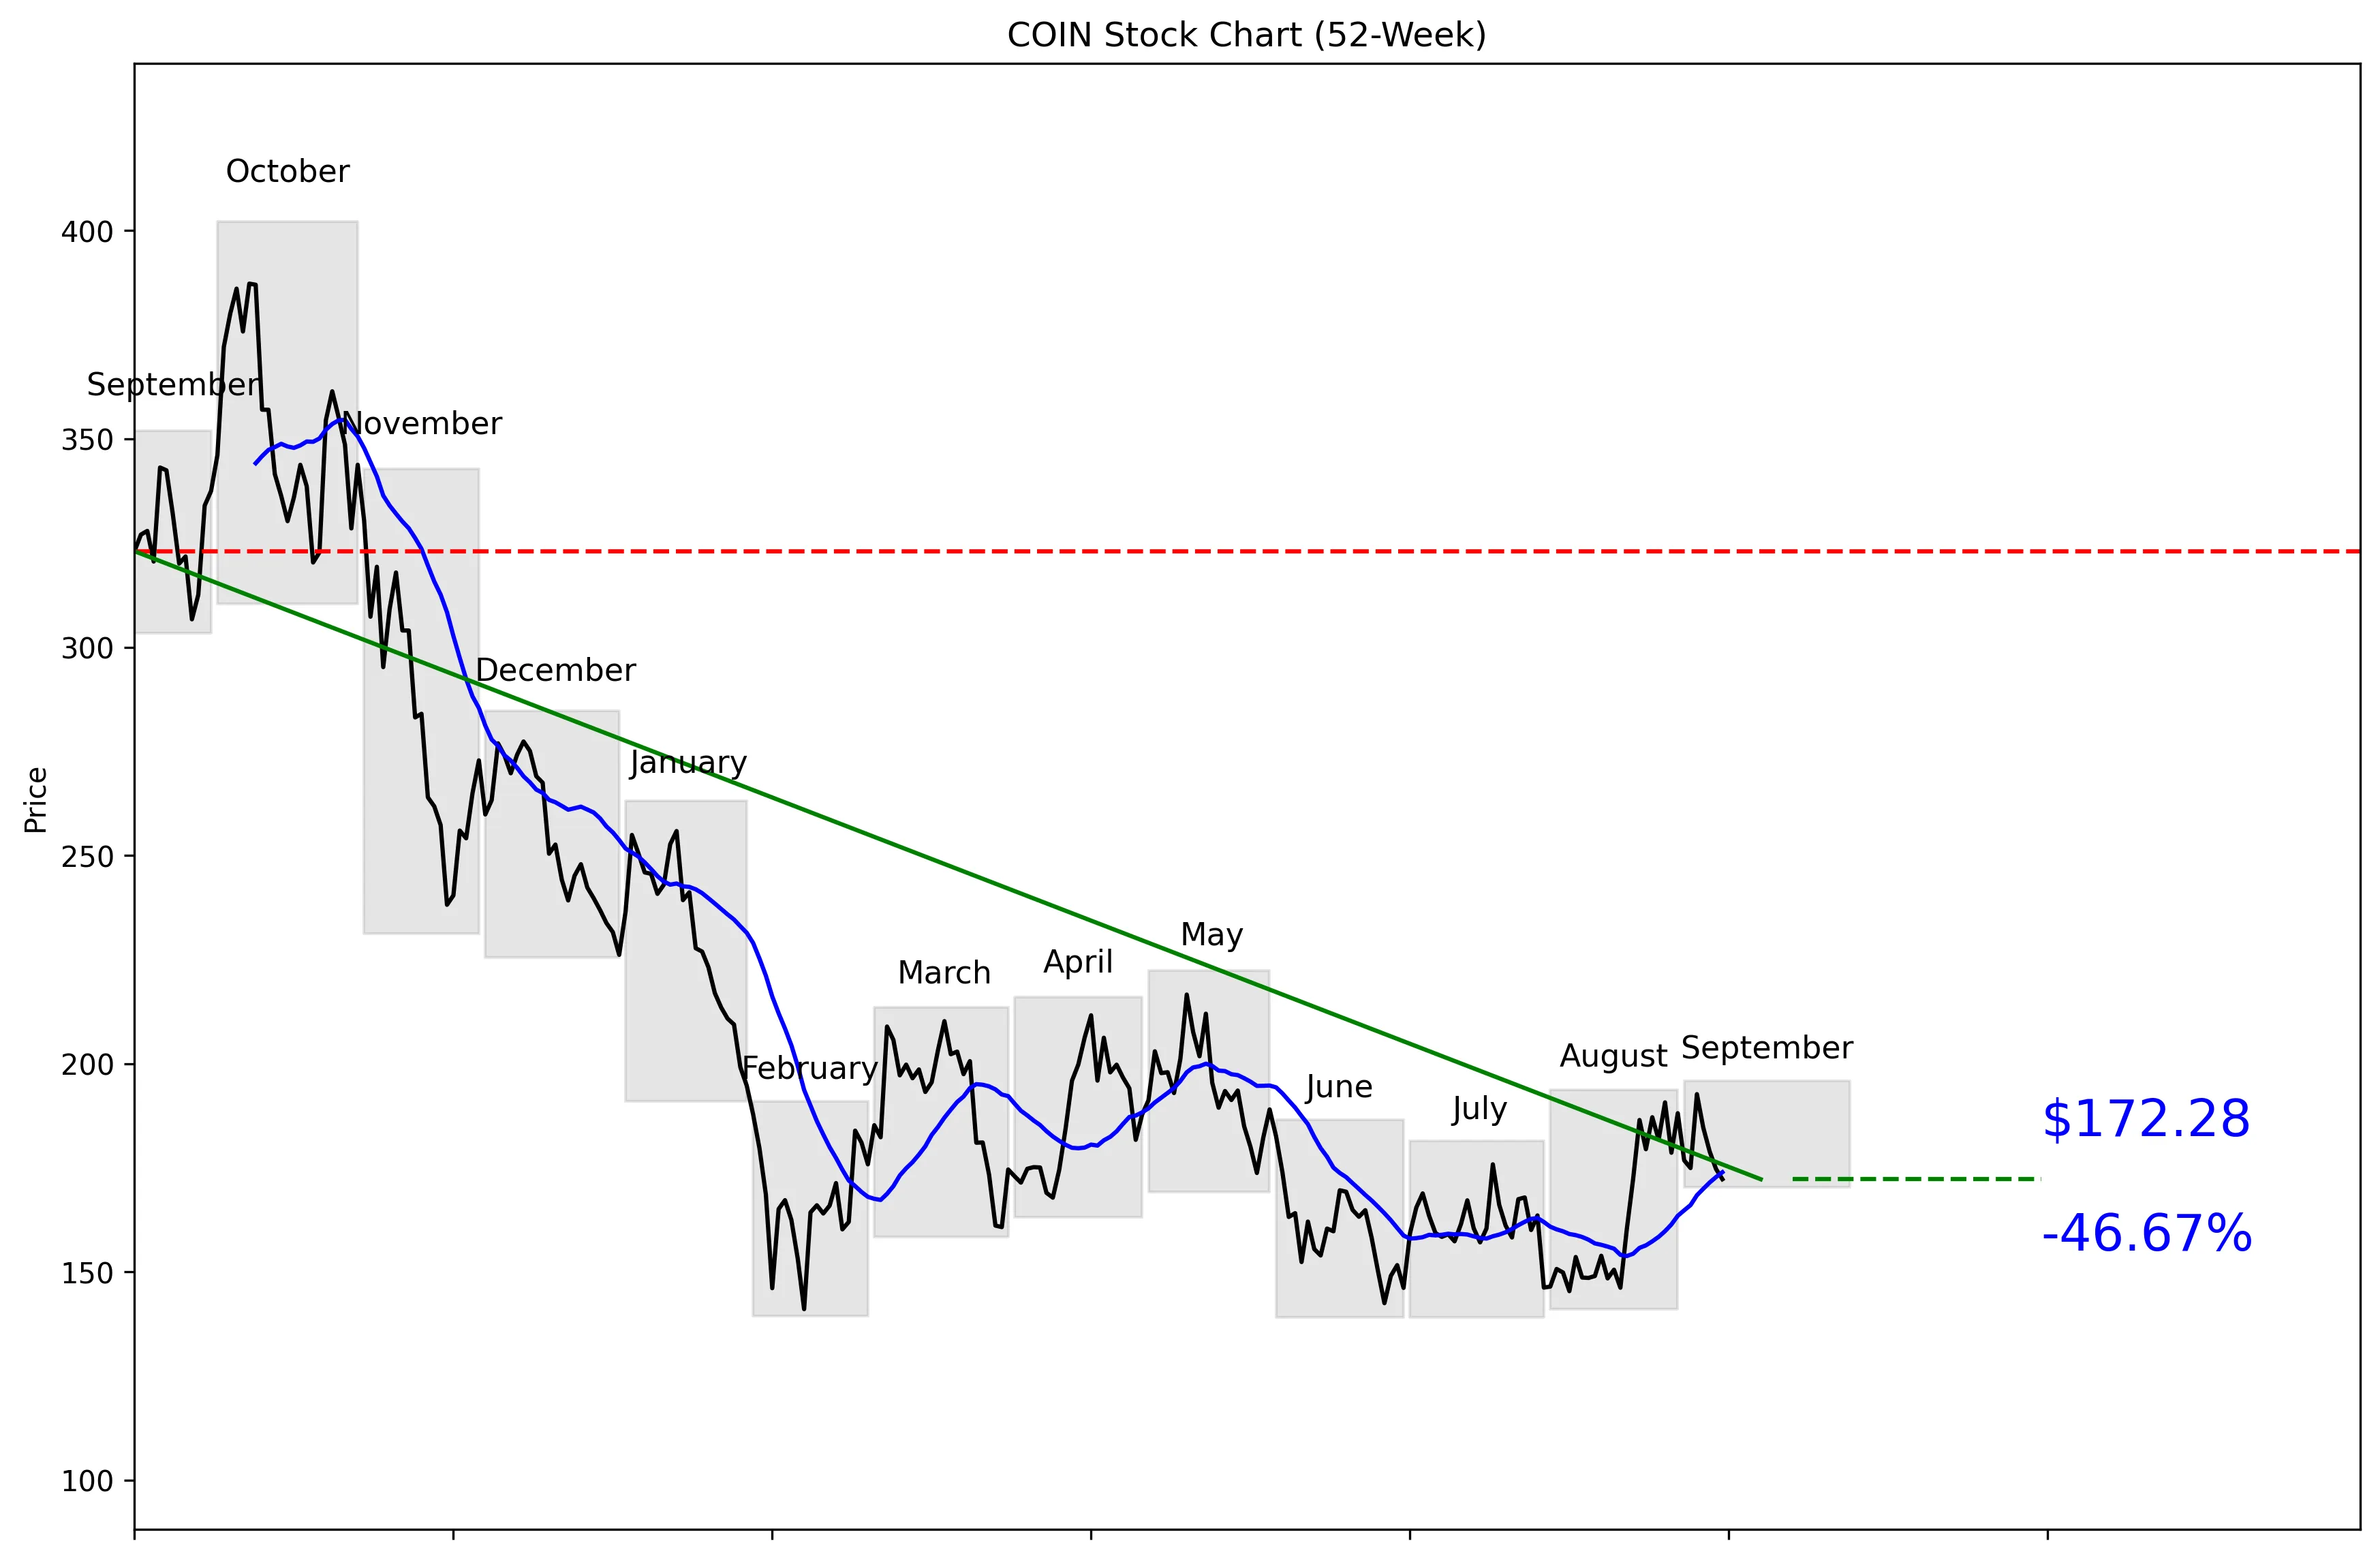
COIN 52-Week Stock Chart
Technical Analysis
COIN trades at $172.84, just 13% of the way from its 52-week low of $139.11 to its high of $402.16. The stock is 57.16% below that high but remains 23.84% above the low. Price sits 0.96% below the 20-day moving average of $173.96, while five-day momentum is negative at 1.53%. The stronger 20-day gain of 15.59% shows the broader rebound is still intact despite recent weakness. Near-term support is $145.41, while $192.70 is the resistance level buyers need to clear.


Recent News and Developments

Morgan Stanley starts COIN at Equalweight with a $250 target

Morgan Stanley initiated coverage of Coinbase with an Equalweight rating and a $250 price target on September 10. The firm likes Coinbase’s scale and product breadth but sees crypto-cycle exposure and less-proven growth businesses as real constraints. Source: Investing.com

Prediction markets reach a $100 million annualized run rate

Coinbase told the Goldman Sachs Communacopia + Technology Conference that prediction-market revenue and contract volume doubled from the first quarter to the second quarter. The product reached a $100 million annualized revenue run rate, while subscription services grew to roughly $2.5 billion annualized. Source: Investing.com

SEC acknowledges Coinbase Derivatives exchange registration

The SEC acknowledged Coinbase Derivatives’ Form 1-N registration notice on September 8. The filing registers the subsidiary as a national securities exchange solely for trading security-futures products under Section 6(g). Source: U.S. Securities and Exchange Commission


Market Sentiment and Analyst Recommendations

Bull Case
Coinbase has $8.79 billion in cash against $6.67 billion in debt, giving it financial room to invest through a volatile crypto cycle. The company generated $6.04 billion in revenue, and its market position is backed by scale and broad product coverage. Subscription services have reached roughly a $2.5 billion annualized run rate, reducing some dependence on transaction activity. Prediction markets reached a $100 million annualized revenue run rate after revenue and contract volume doubled from the first quarter to the second quarter. The SEC’s September 8 acknowledgment of Coinbase Derivatives’ exchange registration could expand its opportunity in security-futures products. Analysts rate COIN a buy across 29 opinions, with a $198.97 consensus target and Morgan Stanley setting a separate $250 target. At $172.84 and 57.16% below its 52-week high, the stock offers meaningful upside if diversification keeps working.
Bear Case
Revenue growth is negative at 17.3%, which is the clearest fundamental weakness in the data. COIN also has no available P/E ratio, making standard earnings-based valuation comparisons difficult. The $6.67 billion debt load is manageable against $8.79 billion in cash, but it is still substantial. Morgan Stanley’s Equalweight rating reflects real concerns about crypto-cycle exposure and less-proven growth businesses. The stock remains below its 20-day moving average, and five-day momentum is negative at 1.53%. Its 57.16% decline from the 52-week high shows how quickly sentiment and valuation can collapse. The analyst target range of $95.00 to $330.00 is unusually wide and signals major disagreement about what the business is worth.
What to Watch
The first test is whether COIN can reclaim its 20-day moving average of $173.96 and then break above near-term resistance at $192.70. A drop toward $145.41 would put the 52-week low of $139.11 back into focus. Investors should watch whether the 15.59% 20-day rebound survives the current five-day decline of 1.53%. Revenue growth needs to improve from negative 17.3% for the bull case to strengthen. The next quarter should show whether prediction markets can build on their $100 million annualized revenue run rate and whether subscription services hold near their roughly $2.5 billion annualized pace. Progress following the SEC’s September 8 acknowledgment of the Coinbase Derivatives registration is another concrete catalyst. Analyst revisions also matter because the current $198.97 consensus target spans an extreme range from $95.00 to $330.00.
Analyst Consensus
BUY

Based on 29 analyst opinions
Low Target
$95.00
Mean Target
$198.97
High Target
$330.00


Earnings and Financial Data

Sector
Financial Services
Industry
Financial Data & Stock Exchanges
Employees
4,951
Earnings & Dividends
Next Earnings
Oct 29, 2026
EPS (Trailing)
$-3.86
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is COIN a good stock to buy?
The analyst recommendation is buy based on 29 analysts, and the consensus target is $198.97 versus a current price of $172.84. Revenue growth is negative at 17.3%, so the takeaway is that COIN offers upside but carries clear fundamental risk.
What is COIN’s price target?
The consensus analyst target is $198.97, with estimates ranging from $95.00 to $330.00. The takeaway is that analysts see potential upside, but their wide target range reflects substantial uncertainty.
Is COIN undervalued?
COIN trades 57.16% below its 52-week high and 23.84% above its 52-week low, but its P/E is unavailable. The takeaway is that the stock looks depressed relative to its yearly peak, though the provided data does not establish that it is fundamentally undervalued.
What are COIN’s support and resistance levels?
Near-term support is the 30-day low of $145.41, while near-term resistance is the 30-day high of $192.70. The takeaway is that these are the key price levels to monitor.
Is COIN stock gaining momentum?
COIN has gained 15.59% over the last 20 trading days but lost 1.53% over the last five trading days. It also trades 0.96% below its 20-day moving average of $173.96, so the takeaway is that the broader rebound has weakened in the short term.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated September 11, 2026.