ALTSTATION.IO

Corpay, Inc. (CPAY) Stock Analysis

By Nova Skye | AltStation.io | Updated October 15, 2026

Price
$392.01
Change
-1.78%
Market Cap
$25.74B
Avg Volume
502.5K

Company Overview

Corpay, Inc. is an Atlanta-based payment infrastructure company in the technology software sector that automates expense management for corporate clients, commercial fleets, and consumers. The business operates across four main segments: Corporate Payments, Vehicle Payments, Lodging Payments, and Other. They sell tools like commercial fuel cards, automated accounts payable systems, cross-border payment platforms, and specialized lodging booking services for mobile workforces and airline crews. Founded in 1986, the company sells directly to enterprises, merchant networks, and fleet operators looking to eliminate manual expense processing and control employee spending.

Corpay holds a market-leading position in specialized fleet and commercial disbursements, standing as the primary heavyweight alongside chief rival WEX Inc. Its competitive edge comes from deeply entrenched closed-loop fuel networks and specialized travel logistics that create steep switching costs for corporate customers. However, the company faces persistent headwinds from fuel price volatility and aggressive competition from newer fintech platforms targeting corporate card spend. While vehicle payment rails generate reliable cash flow, Corpay must continuously defend its moat against nimbler software competitors.

Right now, Corpay is actively pivoting from a traditional fleet card vendor into a higher-margin corporate payments powerhouse. The strategic rebranding from FLEETCOR Technologies to Corpay formalized this transition toward software-driven accounts payable and cross-border solutions. The numbers confirm the shift: full-year 2024 revenue grew 5.8% to roughly $3.97 billion from $3.75 billion in 2023, fueled by a 20% surge in its Corporate Payments division. The base business is steady, but CPAY’s trajectory hinges on maintaining double-digit expansion in corporate AP automation and cross-border transfers.

Key Financials
Market Cap
$25.74B
Revenue
$5.02B
EBITDA
$2.80B
Gross Margin
80.5%
Profit Margin
22.7%
Revenue Growth
21.5%
Total Cash
$3.18B
Total Debt
$10.74B
Free Cash Flow
$1.95B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
23.83
Forward P/E
12.44
Beta
0.89
52-Week High
$427.46
52-Week Low
$252.84
EPS
$16.45
50-Day Avg
$404.13
200-Day Avg
$349.91
Price/Book
7.27
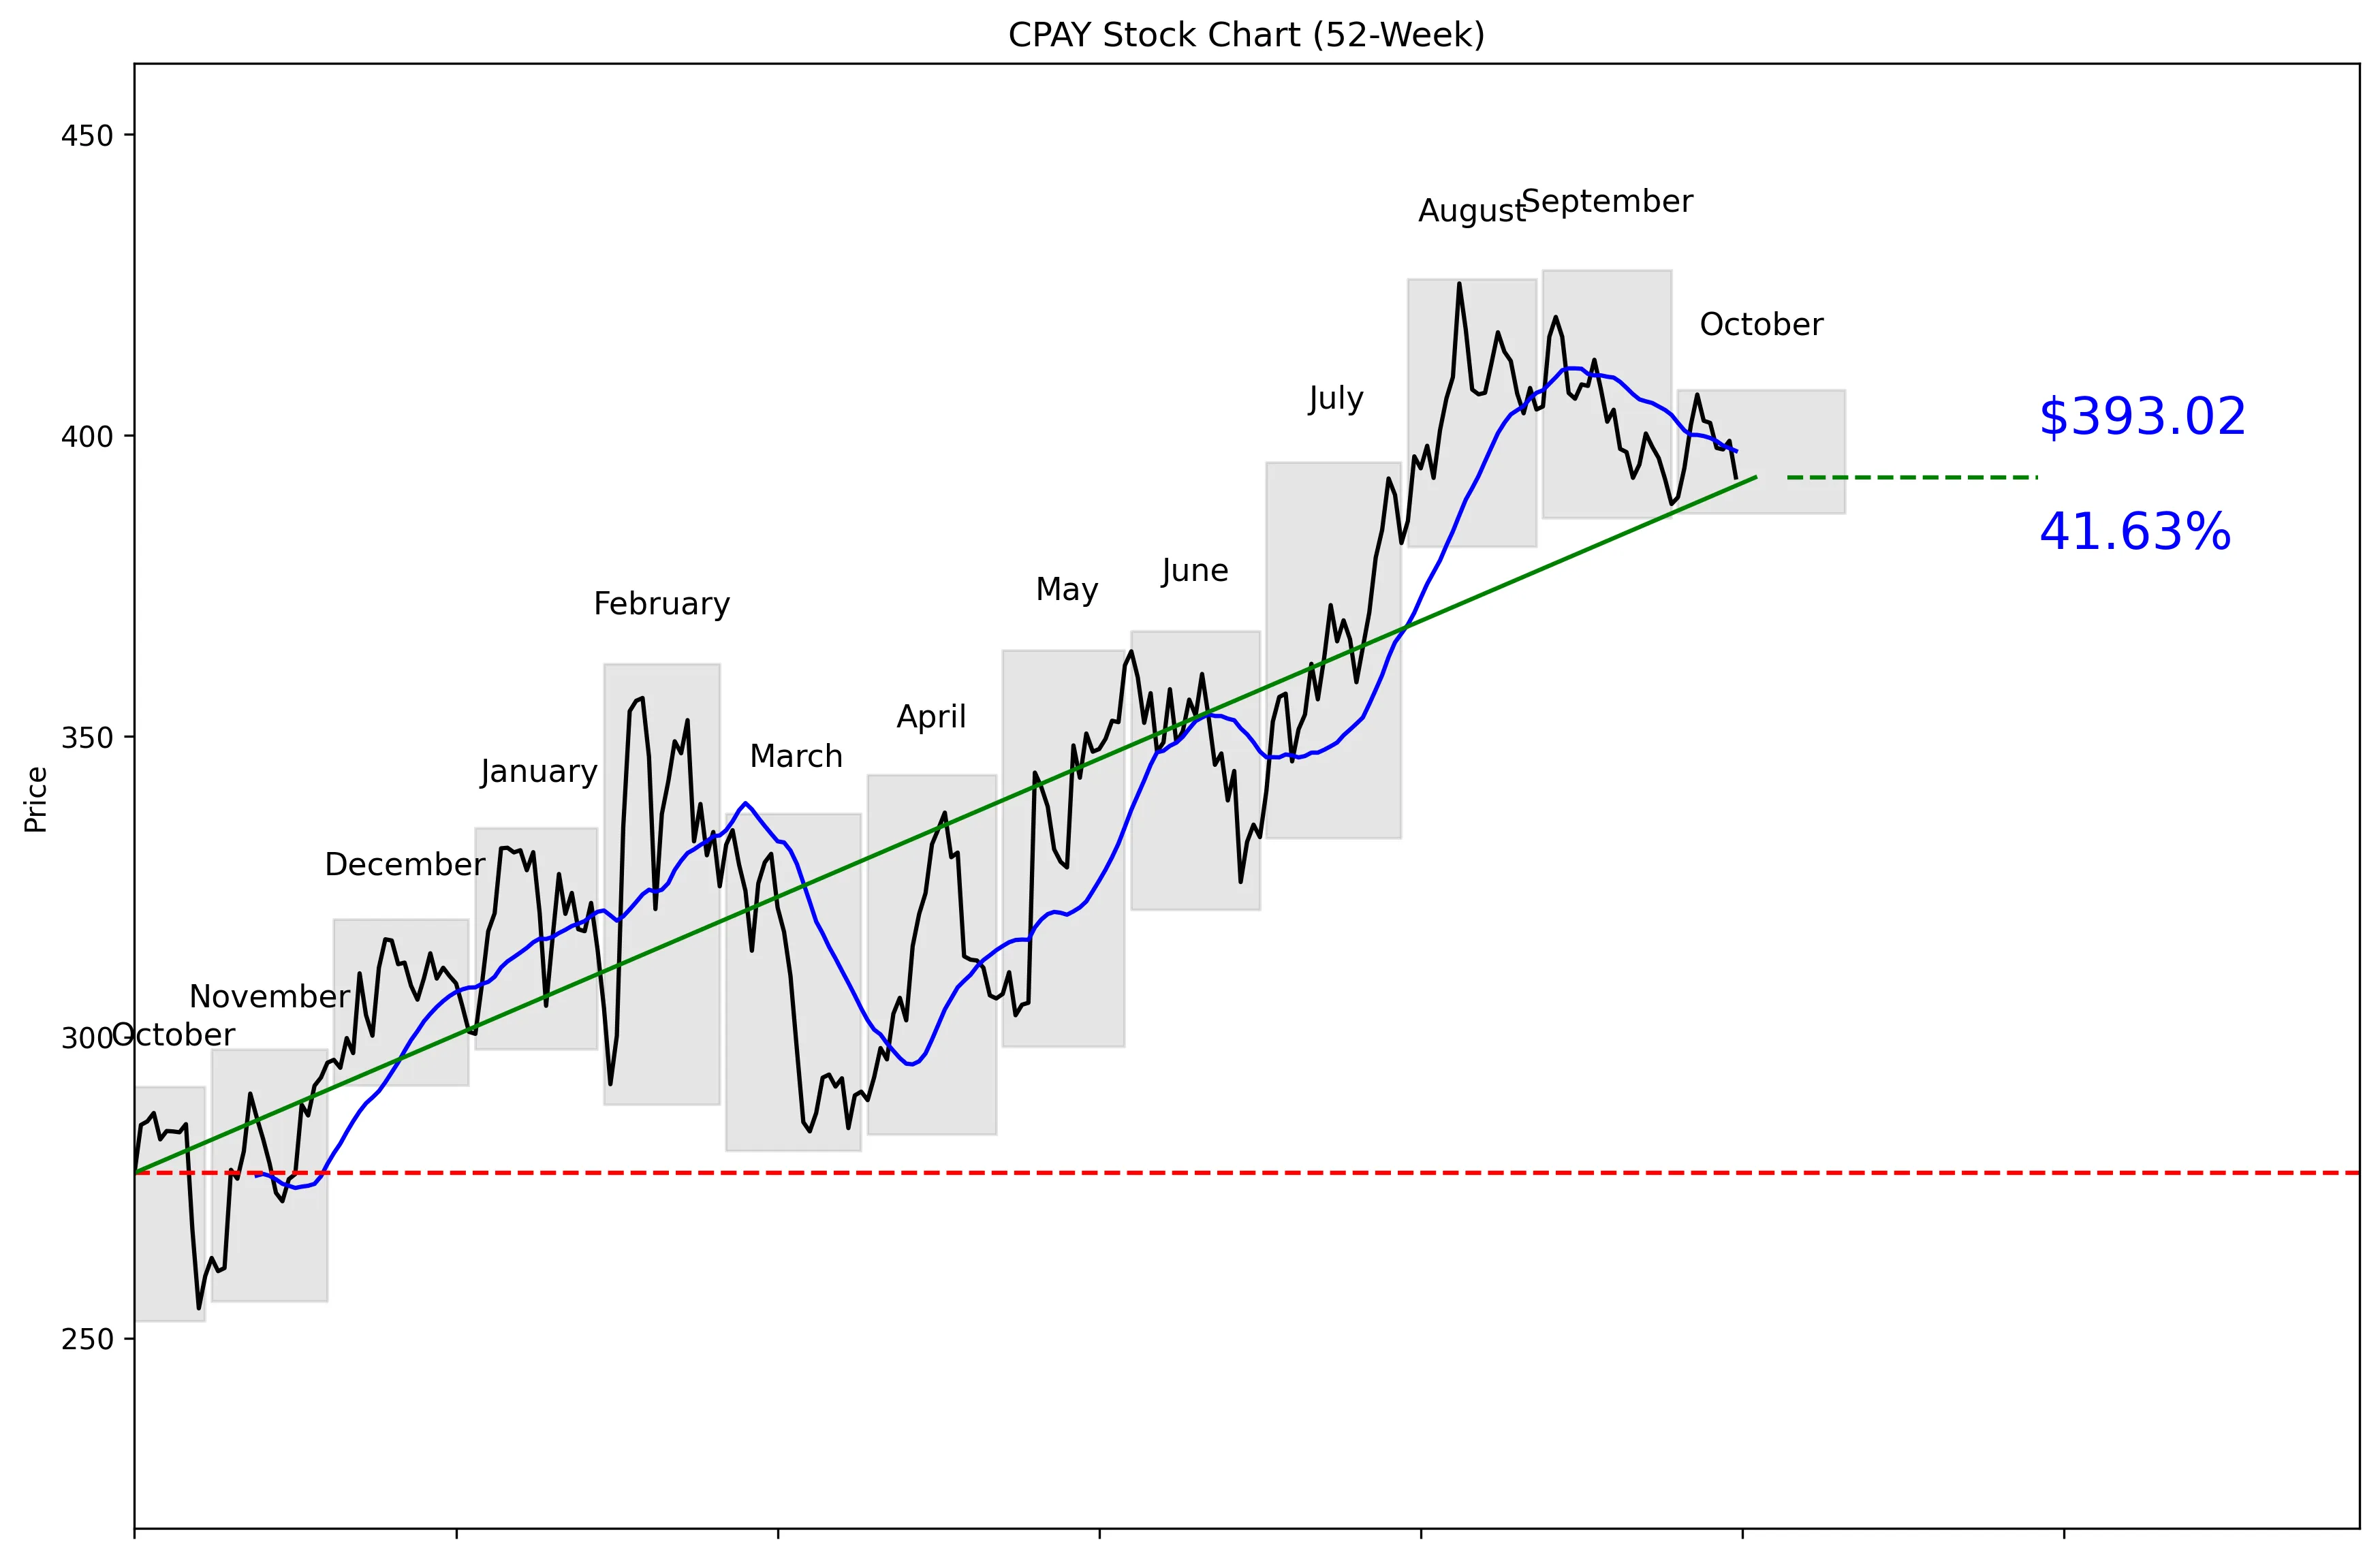
CPAY 52-Week Stock Chart
Technical Analysis
CPAY trades at $392.01, 80% of the way from its 52-week low of $252.84 to its 52-week high of $427.46. The stock is 8.06% below that high and 55.44% above the low. Price sits 1.11% below the 20-day moving average of $397.42. Momentum is negative, with declines of 2.34% over five trading days and 2.30% over 20 trading days. Near-term support is $388.60, while resistance is $419.68.


Recent News and Developments

Corpay takes AP automation pitch to SuiteWorld

Corpay said on October 13 that it will showcase its full-service AP Automation platform at SuiteWorld. The Built for NetSuite SuiteApp covers supplier payments, vendor servicing, exception handling, reconciliation support, and payment fraud monitoring. Source: Corpay

Weiss Ratings upgrades CPAY

Weiss Ratings upgraded Corpay on October 8 from Buy (B-) to Buy (B). No price target was listed with the upgrade. Source: MarketBeat

CPAY loses 2.25% over four sessions

Corpay closed at $402.08 on October 8 and $393.02 on October 14, a 2.25% decline. The October 14 session alone cut 1.52% from the stock, with 441,826 shares traded. Source: Quiver Quantitative


Market Sentiment and Analyst Recommendations

Bull Case
Revenue growth of 21.5% is the strongest part of the CPAY story. The company generates $5.02 billion in revenue and carries a $25.74 billion market capitalization. Corpay is also pitching a broad accounts-payable automation platform covering supplier payments, vendor servicing, exception handling, reconciliation support, and payment fraud monitoring. The analyst consensus is buy across 15 analysts, with a $461.00 target compared with the current $392.01 price. That target implies approximately 17.60% upside, while the high-end target of $536.00 leaves substantially more room. The bull case is straightforward: strong revenue growth, a clear automation offering, and analyst targets above the current price make CPAY worth considering despite the recent pullback.
Bear Case
CPAY trades at 23.83 times earnings, so buyers are paying a meaningful multiple for continued growth. The balance sheet carries $10.74 billion in total debt against $3.18 billion in total cash. That leaves debt well above the company’s reported cash position and makes financial discipline important. Price momentum has weakened, with CPAY down 2.34% over five trading days and 2.30% over 20 trading days. The stock is also below its $397.42 20-day moving average and only $3.41 above near-term support at $388.60. No competitive or macroeconomic data was provided, so the measurable risks here are valuation, leverage, and deteriorating short-term price action.
What to Watch
The first level to watch is $388.60, the 30-day low and identified near-term support. A move back above the $397.42 20-day moving average would improve the short-term setup. Beyond that, $419.68 is the 30-day high and the clearest listed resistance level. Investors should watch whether Corpay’s October 13 SuiteWorld push produces measurable traction for its AP Automation platform, although no customer or revenue targets were provided. The October 8 Weiss Ratings upgrade from Buy (B-) to Buy (B) supports the positive view, but it came without a price target. Over the next quarter, the thesis strengthens if 21.5% revenue growth holds and price reclaims $419.68; it weakens if growth slows or the stock breaks below $388.60.
Analyst Consensus
BUY

Based on 15 analyst opinions
Low Target
$390.00
Mean Target
$461.00
High Target
$536.00


Earnings and Financial Data

Sector
Technology
Industry
Software – Infrastructure
Employees
11,800
Earnings & Dividends
Next Earnings
Nov 04, 2026
EPS (Trailing)
$16.45
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is CPAY a good stock to buy?
CPAY has a buy recommendation from 15 analysts and reported revenue growth of 21.5%. The takeaway is that the fundamental outlook is positive, but the stock’s negative short-term momentum deserves attention.
What is CPAY’s price target?
The analyst target is $461.00, with estimates ranging from $390.00 to $536.00. The takeaway is that the consensus target sits above the current $392.01 price.
What is CPAY’s 52-week range?
CPAY’s 52-week range is $252.84 to $427.46, and the stock is currently 80% of the way from the low to the high. The takeaway is that CPAY trades near the upper end of its annual range.
What are CPAY’s support and resistance levels?
Near-term support is $388.60, while near-term resistance is $419.68. The takeaway is that those are the key listed thresholds for the next major price move.
How much debt does Corpay have?
Corpay has $10.74 billion in total debt and $3.18 billion in total cash. The takeaway is that debt materially exceeds cash and should remain a central risk consideration.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated October 15, 2026.