ALTSTATION.IO

GoDaddy Inc. (GDDY) Stock Analysis

By Nova Skye | AltStation.io | Updated November 04, 2026

Price
$113.73
Change
-2.47%
Market Cap
$14.40B
Avg Volume
2.1M

Company Overview

GoDaddy Inc. is a Tempe, Arizona-based technology firm operating in software infrastructure that sells domain registration, web hosting, and digital commerce tools. Founded in 1997, the business divides its operations into two distinct units: Core Platform and Applications & Commerce. The Core segment generates revenue from domain registrations, aftermarket auctions, shared hosting, and SSL certificates for individuals, developers, and domain investors. The Applications & Commerce segment sells website builders, Managed WordPress, Microsoft 365 integrations, and commerce hardware like the dual-screen Smart Terminal point-of-sale system to small businesses.

GoDaddy is an established market leader in domain registrations and basic infrastructure that defends its turf against specialized web builders and modern commerce platforms. The company’s massive installed base of domain owners provides a built-in top-of-funnel customer acquisition advantage. However, standalone domain registrations and shared hosting are commoditized, low-margin products vulnerable to customer churn and pricing pressure. To maintain its edge, GoDaddy relies on aggressively cross-selling higher-margin add-ons, locking in domain owners with integrated security tools, Microsoft 365 email plans, and GoDaddy Payments.

The company is actively executing a strategic pivot from a commoditized domain registrar into an integrated commerce and business software provider. Growth now hinges on the Applications & Commerce segment, driven by customer adoption of GoDaddy Payments, Smart Terminal hardware, and automated digital marketing tools. This expansion targets higher revenue per user by capturing in-store and online transaction fees alongside recurring software subscriptions. The primary risk is whether micro-merchants will stick with GoDaddy’s bundled ecosystem rather than migrate to dedicated retail and payment specialists.

Key Financials
Market Cap
$14.40B
Revenue
$5.18B
EBITDA
$1.43B
Gross Margin
63.7%
Profit Margin
18.6%
Revenue Growth
6.0%
Total Cash
$1.16B
Total Debt
$3.84B
Free Cash Flow
$1.21B


52-Week Price Performance Analysis

Price Statistics
P/E Ratio
15.64
Forward P/E
10.12
Beta
0.94
52-Week High
$136.29
52-Week Low
$71.59
EPS
$7.27
50-Day Avg
$101.82
200-Day Avg
$91.97
Price/Book
-100.20
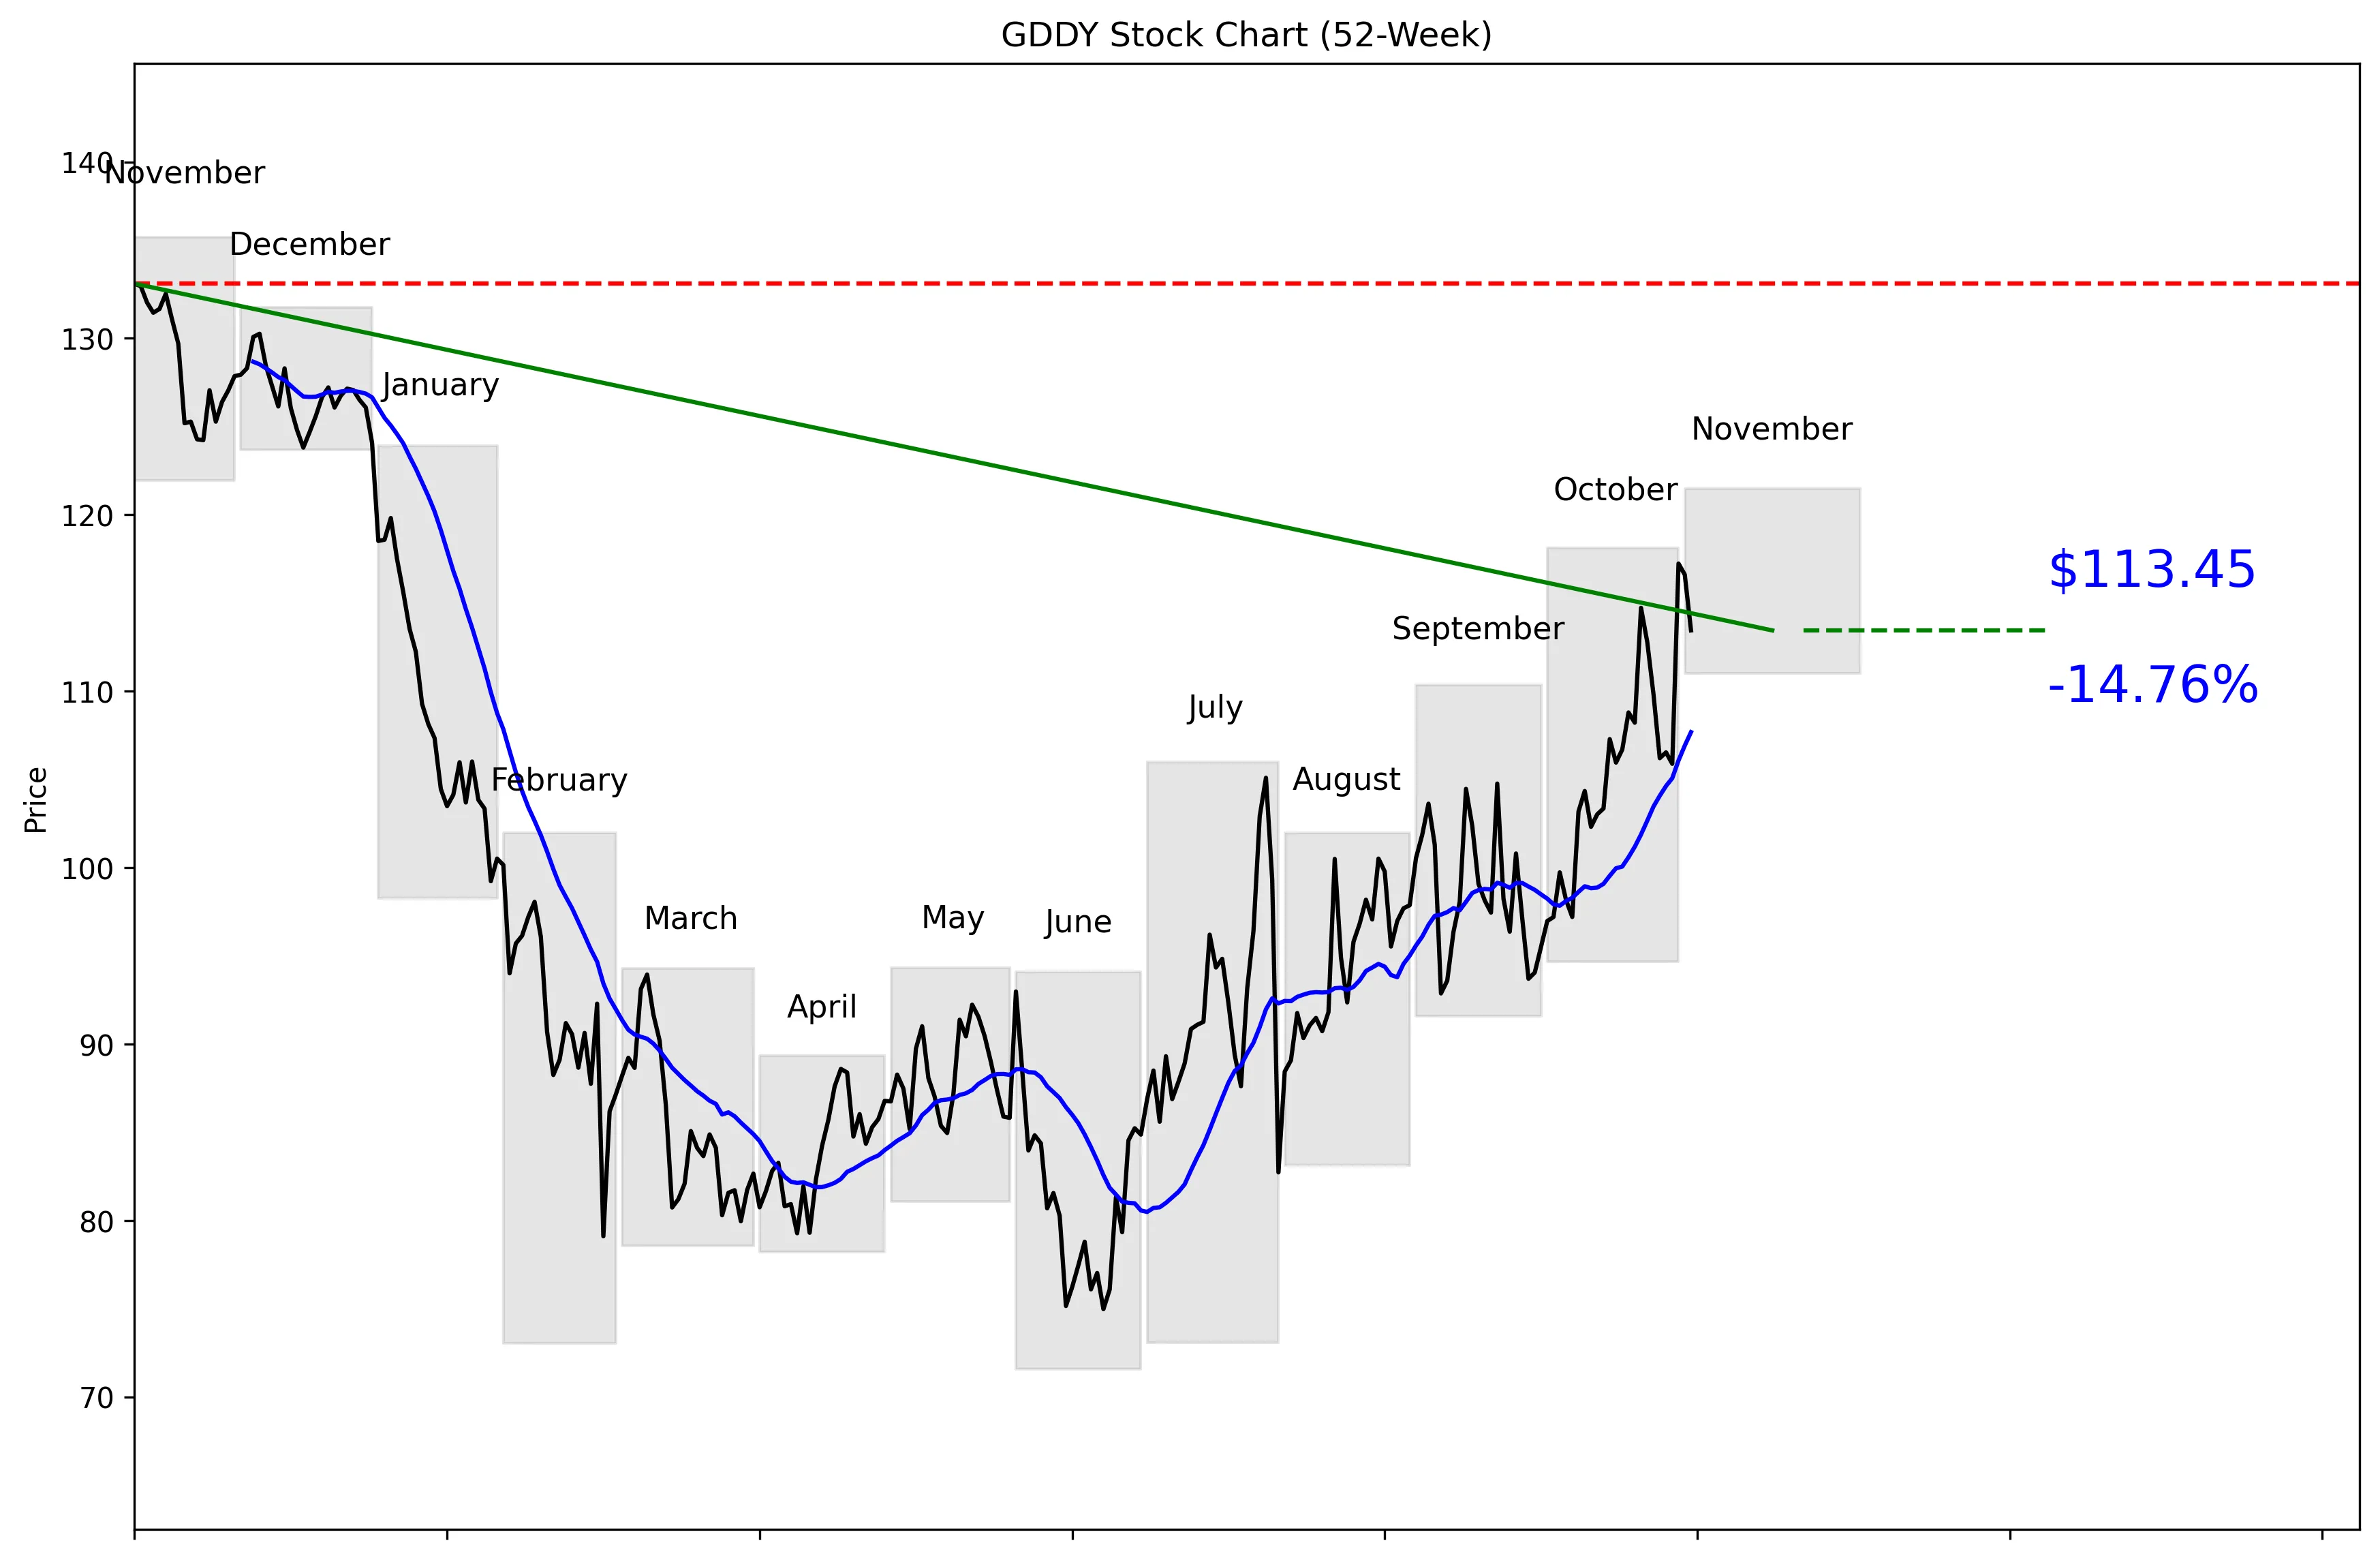
GDDY 52-Week Stock Chart
Technical Analysis
GDDY trades at $113.73, 65% of the way through its technical 52-week range of $71.59 to $135.71. The stock is 16.41% below its 52-week high and 58.47% above its low. Price is 5.35% above the 20-day moving average of $107.69. Momentum is strong, with gains of 6.82% over five trading days and 15.55% over 20 trading days. Near-term support is $93.71, while $117.24 is the resistance level buyers need to clear.


Recent News and Developments

GoDaddy posts 6% revenue growth and lifts profit

Third-quarter revenue reached $1.3418 billion, up 6%, while net income rose 24% to $261.8 million. Free cash flow increased 9% to $480.8 million, and GoDaddy expects full-year revenue near the high end of its $5.215 billion to $5.255 billion range. Source: U.S. Securities and Exchange Commission

UBS raises GoDaddy target as Airo accelerates

UBS raised its price target from $100 to $112 while keeping a Neutral rating. Airo’s annualized bookings run rate exceeded $100 million, more than double the roughly $50 million reported for the second quarter. Source: Investing.com

Analysts reprice GoDaddy after earnings

Wedbush raised its target from $93 to $146 and kept an Outperform rating, while Citigroup moved from $105 to $135 and Jefferies increased its target from $100 to $115. Evercore ISI also raised its target from $85 to $105. Source: MarketScreener


Market Sentiment and Analyst Recommendations

Bull Case
GoDaddy’s third-quarter revenue reached $1.3418 billion, up 6%, while net income increased 24% to $261.8 million. Free cash flow rose 9% to $480.8 million, showing profit and cash generation growing faster than revenue. Management expects full-year revenue near the high end of its $5.215 billion to $5.255 billion range. Airo’s annualized bookings run rate exceeded $100 million, more than double the roughly $50 million reported for the second quarter. Analysts have responded by raising targets, including Wedbush from $93 to $146 and Citigroup from $105 to $135. The broader analyst recommendation is buy from 16 analysts, with an average target of $117.69 and a high estimate of $170.00. At a P/E of 15.64, the stock offers a reasonable entry for investors who believe GoDaddy can keep converting moderate revenue growth into stronger profit and free cash flow growth.
Bear Case
Revenue growth is only 6.0%, which leaves little room for operational mistakes or a slowdown. The average analyst target of $117.69 is close to the current $113.73 price, so the consensus case offers limited upside. Analyst estimates are unusually wide, ranging from $76.00 to $170.00, which signals major disagreement about the stock’s value. GoDaddy carries $3.84 billion in total debt against $1.16 billion in cash, making the balance sheet a real constraint. UBS kept a Neutral rating even after raising its target from $100 to $112, and that target sits below the current price. The stock also gave back part of its 10.72% October 30 earnings jump, falling from a $117.24 close to $116.61 on November 2 and $113.45 on November 3. Investors should not assume Airo’s bookings momentum automatically translates into durable revenue and profit growth.
What to Watch
The next quarter needs to confirm that GoDaddy can keep revenue near the high end of its $5.215 billion to $5.255 billion full-year range. Net income growth should remain closer to the recent 24% rate than the company’s 6% revenue growth rate. Free cash flow is another key test after rising 9% to $480.8 million in the third quarter. Watch whether Airo’s annualized bookings run rate continues above $100 million after more than doubling from roughly $50 million in the second quarter. On the chart, a sustained move above $117.24 would clear near-term resistance, while a decline toward $93.71 would break the current momentum. The October 30 earnings reaction also matters: buyers need to recover the $117.24 close after the pullback to $116.61 on November 2 and $113.45 on November 3. Further analyst target changes will show whether the post-earnings optimism is holding or fading.
Analyst Consensus
BUY

Based on 16 analyst opinions
Low Target
$76.00
Mean Target
$117.69
High Target
$170.00


Earnings and Financial Data

Sector
Technology
Industry
Software – Infrastructure
Employees
5,845
Earnings & Dividends
Next Earnings
Oct 29, 2026
EPS (Trailing)
$7.27
Dividend Yield
None
Payout Ratio
0%

Frequently Asked Questions

Is GDDY a good stock to buy?
GDDY has a buy recommendation from 16 analysts and trades at a P/E of 15.64. Revenue growth is 6.0%, but the average $117.69 target is only modestly above the current $113.73 price, so the takeaway is that the stock looks reasonable rather than deeply undervalued.
What is GDDY’s price target?
The average analyst target is $117.69, with estimates ranging from $76.00 to $170.00. The takeaway is that analysts see some upside, but their wide range shows substantial disagreement.
What are GDDY’s support and resistance levels?
Near-term support is the 30-day low of $93.71, while near-term resistance is the 30-day high of $117.24. The takeaway is that $117.24 is the immediate level GDDY needs to clear.
Is GDDY trading near its 52-week high?
GDDY is 16.41% below its technical 52-week high of $135.71 and sits 65% of the way from its $71.59 low to that high. The takeaway is that the stock is in the upper half of its range but is not close to a breakout high.
How much debt does GoDaddy have?
GoDaddy has $3.84 billion in total debt and $1.16 billion in total cash. The takeaway is that debt materially exceeds available cash and should remain part of the investment risk assessment.

Related Stock Reports

Disclaimer: This report is for informational purposes only and does not constitute financial advice. The analysis and opinions expressed are those of AltStation.io and should not be relied upon as the sole basis for investment decisions. Always conduct your own research and consult with a qualified financial advisor before making investment decisions. Past performance does not guarantee future results. Updated November 04, 2026.